Blog

  • The Full-Price Check: Five Numbers to See Before You Buy Online

    The Full-Price Check: Five Numbers to See Before You Buy Online

    A product can look affordable until the final checkout screen adds delivery, a payment surcharge or a currency-conversion cost. The useful habit is to compare the amount you will actually pay, not just the large number beside the product picture.

    New Zealand’s Consumer Protection guidance recommends checking the full cost of an online purchase, including delivery, fees and currency. This five-number check turns that advice into a small decision routine.

    1. What is the item price?

    Start with the advertised price, then check what you are actually buying. Confirm the size, quantity, model or service level. A low price for a smaller quantity is not automatically a better deal. If a promotion says “from” or shows a discount, find the conditions before comparing it with another option.

    2. What will delivery add?

    Write down the delivery cost and the expected timeframe. Some sellers offer free delivery only above a minimum order, while others add a charge at the final step. If an item is needed by a particular date, the cheapest option may not meet the deadline. Consumer Protection says a retailer remains responsible for delivery of an order until it reaches you, so keep the order confirmation and promised timeframe.

    3. Are there fees or surcharges?

    Look for payment surcharges, service fees, booking charges and any optional add-ons that have been selected. A fee is easier to notice when it is written on the same comparison sheet as the item price. Consumer Protection notes that payment surcharges can appear when using some contactless card payments, so check the payment method as well as the product.

    4. Is the price in New Zealand dollars?

    If the seller is overseas, check the currency before doing the maths. A number that looks like dollars may not be NZD. Consumer Protection also points shoppers to possible GST, border or currency-conversion costs for some online purchases. Treat the displayed conversion as an estimate until you know which amount your provider will charge.

    5. What happens if you change your mind?

    Read the returns, cancellation and refund information before you buy. A change of mind may have different rules from a faulty or incorrectly described product. Check who pays return delivery, how long a refund takes and whether the item has exclusions. Save a copy of the product description and your receipt.

    Make the decision visible

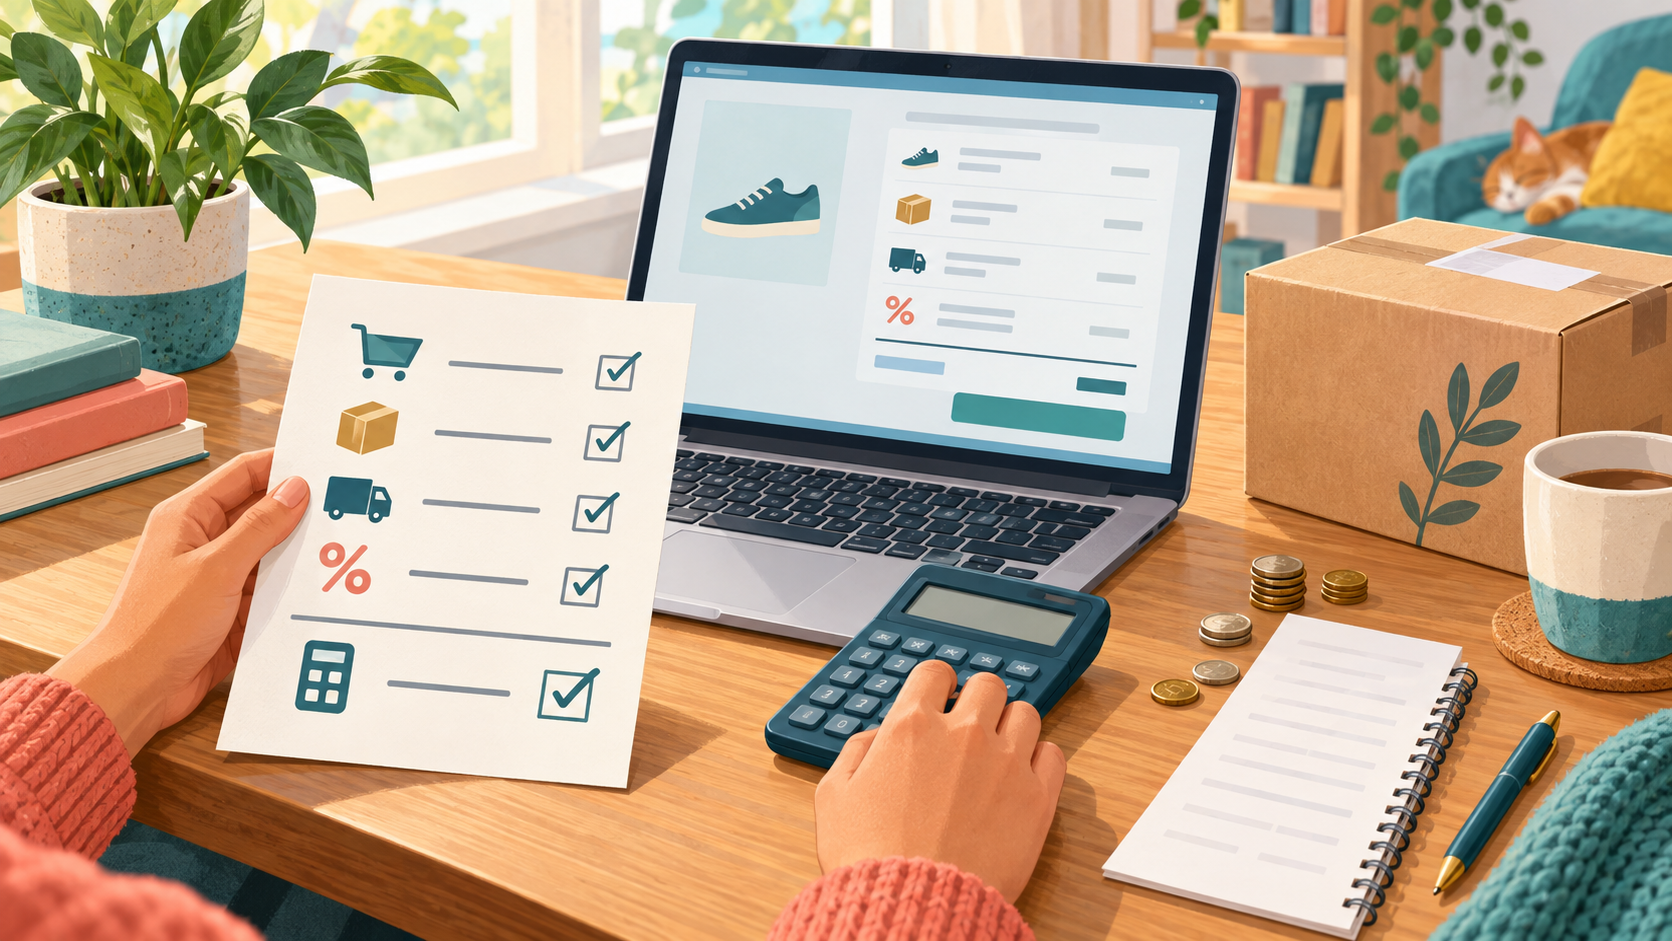
    For two options, write five lines: item price, delivery, fees, currency or tax notes, and return conditions. Then add the first three numbers to estimate the amount leaving your account. If the options are close, quality, timing and the seller’s reliability may matter more than a tiny price difference. If the final total is not clear, pause and ask the seller before paying.

    The Fair Trading Act protects consumers from misleading prices and important costs being left out, but a careful buyer still benefits from checking the checkout details. The Full-Price Check is not a promise that an online purchase is safe or suitable; it is a way to make the decision less surprising.

    Sources and further reading

    Consumer Protection: Know your rights when shopping online; Consumer Protection: Cash and EFTPOS; Consumer Protection: Fair Trading Act.

    FAQs

    What does “full price” mean online?

    It means the amount you expect to pay after considering the item, delivery, fees and any currency or tax information shown by the seller.

    Should delivery be part of my comparison?

    Yes. Delivery changes the amount leaving your account and may affect whether the item arrives when you need it.

    What if the website uses a currency I do not recognise?

    Pause and confirm the currency and possible conversion costs before relying on the displayed number.

    Are payment surcharges always illegal?

    Rules depend on the payment and the circumstances. Check the surcharge information before paying and ask the seller if it is unclear.

    Does a change-of-mind return work the same as a faulty-product return?

    No. They can have different rights and conditions, so read the seller’s policy and the relevant consumer guidance.

    What should I save after buying online?

    Keep the order confirmation, receipt, product description, delivery promise and any return instructions.
  • A MoneyCQ Debrief: Five Questions for Parents and Teachers

    A MoneyCQ Debrief: Five Questions for Parents and Teachers

    A MoneyCQ session can end with a number on a screen, but a score is not the whole conversation. The most useful follow-up may be a learner explaining what they noticed, what information they used, and what they might try next time. Parents, whānau and teachers can help by asking before advising.

    These questions work with a fictional scenario or a shared game experience. No one needs to disclose their family income, account balance or private financial decisions to take part.

    1. What surprised you?

    This invites the learner to name an event, cost or choice they did not expect. Listen for the detail that caught their attention rather than correcting the answer immediately.

    2. What information helped you decide?

    The learner might mention a price, a due date, a goal or the effect of an earlier choice. Ask how they found that information and what else they would want to know in a similar scenario.

    3. Which trade-off felt hardest?

    Money choices can involve competing priorities. Instead of asking whether the choice was right or wrong, invite the learner to describe what they gained and what they gave up. More than one answer can make sense depending on the goal and circumstances.

    4. What would you like to test next time?

    Let the learner choose one small experiment, such as checking a recurring cost, saving toward a goal before optional spending, or comparing two options. Keep the experiment within the simulation; do not turn it into a real-world financial instruction unless an adult has checked that it is suitable.

    5. What is different in real life?

    A simulation makes choices visible, but real people have different responsibilities, opportunities and support. Ask which parts of the scenario feel simplified. This helps the learner practise judgement rather than copying a game outcome as a universal rule.

    Keep the chat short, use plain words, stay on the topic the learner chose, and avoid treating a score as a judgement of character. Sorted’s guide to good money conversations recommends listening, avoiding judgement and keeping the discussion focused. A calm debrief gives families and classrooms room to notice learning without requiring personal disclosures.

    MoneyCQ is a place to practise decisions. A thoughtful question can help a learner carry the reasoning—not a single answer—into the next scenario.

    FAQs

    Should a debrief focus on the learner’s score?

    A score can be one starting point, but the conversation can focus on the choices, information and trade-offs behind it rather than treating it as a grade.

    Do learners need to share real family finances?

    No. Use the simulation or a fictional example. Personal balances, income and household decisions can remain private.

    What if the learner made a choice I disagree with?

    Ask what they were trying to achieve and what information they used before offering another perspective.

    How long should the conversation take?

    There is no required length. A few focused questions can be enough for one session; let the learner’s interest guide the discussion.

    Can a teacher use these questions with a class?

    Yes. Keep examples fictional or from the simulation, and make it clear that students do not need to disclose personal or family finances.

    Is a MoneyCQ outcome advice for real life?

    No. Treat it as practice in reasoning through a simulated situation, not as a universal financial recommendation.

  • Lost Track of Spending? Try This Ten-Minute Money Reset

    Lost Track of Spending? Try This Ten-Minute Money Reset

    You meant to check your spending on Sunday. Then the week filled up, a few receipts disappeared, and your budget page now feels like another thing you have failed to do. Pause there. A missed check-in is information about the routine, not a verdict on you.

    This ten-minute reset is for getting oriented again. It does not require a perfect record or a promise to fix everything at once.

    Minute 1–2: gather the next facts

    Open the account or notes you normally use. Write down the money currently available for the spending decisions you control, plus the next expected income date if you know it. If you share finances, only access the information you are authorised to see.

    Minute 3–5: look at the next seven days

    List the bills and essential costs you expect before the next check-in: for example, transport, food, a phone plan or a payment you already agreed to make. Mark a due date beside each one. Keep estimates clearly labelled as estimates; do not turn a guess into a fact.

    Minute 6–8: compare, then choose one action

    Put the available amount beside the near-term commitments. If the plan looks workable, choose a day and time for the next short review. If the numbers do not fit, choose one practical next step: check a bill date, pause an optional purchase, contact the provider to ask about options, or talk with a trusted adult or whānau member. You do not have to solve every longer-term question in this one sitting.

    Minute 9–10: restart with a tiny record

    Pick a format you will actually use: a phone note, a paper page, or a spreadsheet. Record one category or a few transactions until the next check-in. Sorted’s guide to tracking spending notes that starting with one month is better than not starting, and that a longer period can reveal irregular costs such as car bills or gifts. Treat a short reset as a restart, not a complete picture.

    When your routine is steady again, review what made the old one hard to keep. Was the reminder at the wrong time? Was the form too detailed? Change one part so the next check-in is easier. Resilience is not never losing track; it is having a small way back.

    FAQs

    What if I missed more than one week?

    Start with what is due next and what you can verify now. You can rebuild the longer record gradually instead of trying to recreate every detail at once.

    Does a ten-minute reset replace a full budget?

    No. It is a short orientation check. A fuller budget can be built or updated when you have more complete information.

    What should I check first?

    Check the amount available to you, expected income timing if known, and the essential commitments coming up soon.

    What if the numbers do not fit?

    Choose one next step, such as confirming a bill date, pausing an optional purchase, asking a provider about options, or speaking with a trusted person.

    Do I need an app to track money?

    No. A phone note, spreadsheet or paper record can work. Use a method you can maintain and keep private details secure.

    How long should I track spending?

    A short record can help you restart. Sorted suggests that tracking for longer, such as three months, can include irregular costs and provide a broader picture.

  • The Group Gift Ledger: A Fictional Story About Agreeing on a Fair Spend

    The Group Gift Ledger: A Fictional Story About Agreeing on a Fair Spend

    This is a fictional teaching story, not a real testimonial.

    Aria, Ben and Kiri want to give a teammate a farewell present. They find a set they all like for $54. Aria suggests splitting the price three ways. Ben pauses: $18 is more than he planned to spend. Kiri offers to cover the difference, but nobody has yet agreed what “split it” means.

    They agree on the question first

    Instead of asking who can pay the most, Aria asks, “What is the total amount we are comfortable spending, and does everyone want to join in?” Ben says he would prefer to keep his contribution at $10. Kiri is comfortable paying more, but she does not want the others to owe her later. They agree that contributions are optional, and nobody has to explain a private reason for a limit.

    They compare ways to contribute

    The friends write down two choices. They could each contribute the same amount and choose a less expensive gift. Or they could agree to different voluntary amounts, provided the total cost and any leftover are clear before they buy. They decide the second option feels comfortable: Aria puts in $18, Ben $10, and Kiri $26. The agreed total is $54, so there is no expected payback between them.

    That is not a universal formula for fairness. Equal shares, different shares, or choosing a lower-cost gift can all be reasonable. The important step is agreeing before anyone spends money, not assuming that everyone has the same budget or preference.

    The tiny ledger prevents a bigger mix-up

    One friend records the item, price, who has contributed, and whether the purchase is complete. If the price changes, they check with the group again. If money is left over, they decide in advance whether it will be returned or used for a card. Nobody silently covers an extra amount and then expects repayment.

    Money conversations can feel personal, so keep the discussion focused on the shared decision, use plain language, and avoid blame. Sorted’s guide to good money conversations recommends staying on topic, listening, and avoiding judgement. The group-gift story lets learners rehearse those skills without revealing anyone’s real finances.

    What the story teaches

    A shared purchase has two parts: the item and the agreement around it. A clear total, voluntary contributions and a simple record can make expectations visible. In MoneyCQ, a group choice like this can prompt learners to notice how communication changes the money decision—not just the final number.

    FAQs

    Is this story about real people?

    No. Aria, Ben and Kiri are fictional characters used to explore a group-spending decision.

    Is an equal split always the fairest choice?

    No. Friends can choose equal contributions, different voluntary amounts, or a lower-cost gift. They should agree before buying.

    Should someone have to explain why they cannot contribute more?

    No. A person can set a spending limit without sharing private details about their finances.

    Why write down the contributions?

    A simple record makes the agreed total, payments and any leftover money clear to everyone.

    What if the gift costs more than expected?

    Pause and ask the group before paying more. Do not assume anyone has agreed to cover the difference.

    What is the main money skill in this story?

    It is agreeing on a shared plan before spending, while respecting different limits and preferences.

  • The Subscription Check: Find the Renewal, Cost and Cancellation Route

    The Subscription Check: Find the Renewal, Cost and Cancellation Route

    A digital purchase can be a one-off payment, a subscription, or an ongoing cost for extra features or in-game items. If the payment happens automatically, it can be easy to forget which service is being paid for, when the next charge is due, or which account controls the renewal.

    A subscription check is not about declaring every service good or bad. It is a short inventory that lets the people paying decide whether each service still fits their priorities and budget.

    Make a simple subscription list

    For each service, record its name, who uses it, the current price, how often it is charged, the next renewal date if known, and where the cancellation instructions are. Check the provider’s account page and recent bank or card statements. Use the actual charge interval: weekly, monthly, annually, or another term.

    To make costs easier to compare, convert them to one period. If a service costs $12 every month, twelve monthly charges would total $144 over a year if the price stays the same and the subscription remains active. Treat this as arithmetic, not a prediction: providers can change terms or prices, so check the current details.

    Know who controls the payment

    A direct debit is approved by you but set up and controlled by the business being paid; its amount may vary. An automatic payment is set up and controlled by you and is usually the same amount each time. Some digital services instead charge a saved card or use an app-store account. These routes are not interchangeable. The Consumer Protection guide to direct debits and automatic payments explains the difference and how to change or cancel an automatic payment.

    Read the cancellation terms before acting

    Find out which company or platform manages the subscription and follow its stated cancellation steps. Save a confirmation or copy of your message. Stopping a payment instruction at the bank may not, by itself, end a separate service contract. Consumer Protection advises checking contract terms and sending cancellation notice in a way that can be kept as a record.

    For digital products, New Zealand’s Consumer Protection guidance says buyers have Fair Trading Act protections, including protection from unfair contract terms. Its streaming and downloads guide recommends checking subscription cancellation processes and how charges work. If a learner is under the account holder’s care, do the check with the adult who controls the account.

    Choose one next step

    For each service, choose keep, review, or cancel after checking who uses it and what the terms say. If you cancel, verify the end date and watch for the confirmation. If you keep it, add a reminder before the next renewal. In MoneyCQ, this kind of recurring-cost check shows how a small regular choice can occupy future room in a plan.

    FAQs

    Is a subscription the same as a one-off digital purchase?

    No. A subscription can charge repeatedly over an agreed period, while a one-off purchase is charged once. Check the terms for the product you use.

    Are direct debits and automatic payments the same?

    No. A direct debit is controlled by the business you approved, while an automatic payment is set up and controlled by you. The amount rules can differ.

    Does cancelling a bank payment always cancel the subscription?

    Not necessarily. Follow the provider’s cancellation process and check the service contract as well as the payment route.

    What details should go in a subscription audit?

    Record the service, user, cost, charge interval, next renewal date if known, payment route and cancellation instructions.

    What proof should I keep after cancelling?

    Keep the provider’s confirmation or a copy of your cancellation notice, and note the stated end date.

    What if I do not recognise a digital charge?

    Check the account and household users, then contact the platform or payment provider through its official support channel if it remains unclear.

  • The Unit-Price Hunt: A Family or Classroom Value Challenge

    The Unit-Price Hunt: A Family or Classroom Value Challenge

    A large packet can look like better value because it contains more. A bright sale label can make one option feel like the obvious choice. The Unit-Price Hunt is a short activity that slows the decision down: compare the cost per same amount, then ask whether you will use what you buy.

    New Zealand’s Consumer Protection guidance explains that unit prices let shoppers compare the same type of item across different sizes and packaging. Many covered grocery products must show a standard unit price, but the rules do not cover every product or every retailer. When a label is missing, you can still practise the calculation with sample cards.

    Set up the hunt

    Choose two or three similar products, such as rice, cereal or milk. Use a supermarket shelf, a printed flyer, or made-up price cards at home or in class. Do not photograph or record another shopper’s payment details. Give everyone a simple worksheet with four columns: item, total price, amount, and price per standard unit.

    Compare the same measure

    For a practice example, imagine a 500-gram bag costs $4.50. It costs 90 cents per 100 grams because five 100-gram portions fit in the bag and $4.50 divided by five is $0.90. Now imagine a 750-gram bag costs $6.00. Its unit price is 80 cents per 100 grams. The larger bag is cheaper per 100 grams in this invented example, but it still costs more at the checkout.

    Ask learners to check that both products use the same unit before comparing. Per 100 grams cannot be compared directly with per kilogram until the amounts are converted to a common measure. For liquids, the label may use litres or 100 millilitres.

    Add the real-life question

    Unit price is one clue, not the whole decision. Does the household need that much? Is there room to store it? Could some spoil or go unused? Is one option a different product or quality? Can the shopper afford the larger total today? A lower unit price does not make an unnecessary purchase worthwhile.

    Finish with a one-minute debrief

    Have each person share one surprise, one calculation they checked, and one reason they might choose the option with the higher unit price. A smaller pack can be a sensible choice when it matches the amount needed, fits the available cash, or avoids waste. The goal is not to crown a perfect shopper; it is to practise reading the information before deciding.

    Consumer Protection’s unit-pricing guide has examples of comparing package sizes and notes that not every product is covered. Keep the activity fictional if learners should not share family shopping details.

    FAQs

    What is a unit price?

    It is the cost expressed for a standard amount, such as a kilogram, litre or 100 grams, so similar items can be compared.

    Is the bigger package always better value?

    No. Compare the unit price, total checkout cost, amount needed and whether the product can be used before it is wasted.

    Can I compare different units directly?

    Convert them to the same measure first. For example, change kilograms to grams or litres to millilitres before comparing.

    Do all supermarket items have to show a unit price?

    No. New Zealand’s unit-pricing rules cover many grocery products and eligible retailers, but there are exceptions.

    Can we do the activity without visiting a shop?

    Yes. Use sample cards, a flyer or made-up prices so everyone can practise without sharing personal purchases.

    What is the lesson if the cheapest unit price is not chosen?

    The decision can still be thoughtful if the shopper considered total cost, amount needed, storage and likely waste.

  • Your First Bank Account: Six Questions to Ask Before You Choose

    Your First Bank Account: Six Questions to Ask Before You Choose

    Your first bank account is more than a place for money to land. It can be the route your pay or allowance takes, the card you use for everyday purchases, and the place you keep savings for a goal. The useful question is not simply which account has the biggest number beside it. It is which account fits the job you need it to do.

    In New Zealand, account names and rules differ between providers. Treat this as a comparison checklist, not a recommendation for a particular bank. Read the current account terms and ask the provider if anything is unclear.

    1. What job will this account do?

    An everyday transaction account is designed for money moving in and out: card purchases, transfers and bills. A savings account may be designed to hold money longer and may have different withdrawal or interest conditions. Some people use one account; others find it easier to separate spending money from savings. Pick the setup that you can understand and keep track of.

    2. What could you pay in fees?

    Look for monthly account fees and charges linked to the way you actually bank. Check card purchases, ATM use, branch transactions, overseas purchases, overdrafts and returned payments where those apply. A fee that looks small per transaction can matter if you use that service often. Consumer NZ’s bank-fees guide explains why reviewing your own transaction pattern is a useful starting point.

    3. How easy is it to reach your money?

    Check how you can access funds: an app, online banking, a card, an ATM, a branch, or another route. Ask whether a savings account limits withdrawals, requires notice, or changes its interest conditions when you take money out. A higher advertised rate is not automatically a better fit if the access rules do not suit your goal.

    4. What are the interest conditions?

    If an account pays interest, find out how the rate is calculated and when it is paid. Look for minimum balances, monthly deposits, withdrawal limits, bonus-rate rules and any fees. These details can change, so use the provider’s current terms rather than an old comparison table. The Financial Markets Authority explains that cash products can carry conditions and withdrawal consequences; the Reserve Bank’s monthly call-savings data is useful context, not a promise about a particular account.

    5. What happens if something goes wrong?

    Find the provider’s contact and lost-card process before you need them. Use a unique PIN and strong sign-in details, keep them private, and turn on security options the provider offers. If an account is shared or supervised, agree who can see it and who is allowed to make transfers.

    6. Can you explain the choice?

    Try describing the account in one sentence: “This is where my spending money goes because…” or “This is where I keep my goal money because…”. Then compare two options on the same sheet: job, likely fees, access, interest conditions and security. In MoneyCQ, this is the kind of decision that turns a headline offer into a real-life trade-off.

    The best account for a learner is the one whose costs and rules they can explain—not necessarily the one with the most exciting headline. Recheck the terms when your needs change.

    Sources and further reading

    Consumer NZ: Bank accounts and fees; Financial Markets Authority: Cash investments; Reserve Bank of New Zealand: Call-savings interest-rate data.

    FAQs

    Is an everyday account the same as a savings account?

    Not always. Everyday accounts are generally used for payments and regular activity; savings accounts can have different access and interest conditions. Check the provider’s terms.

    Should I choose the account with the highest interest rate?

    Compare the rate with fees, access rules and conditions. A headline rate alone does not show whether an account suits your needs.

    What fees should I look for?

    Check the current schedule for charges that could apply to how you use the account, including card, ATM, branch and overdraft services.

    Can a savings account limit withdrawals?

    Some accounts have withdrawal or notice conditions, while others are more flexible. Read the specific account terms before opening it.

    How often should I compare my account?

    Review it when your banking habits or goals change, and recheck the provider’s current fees and terms from time to time.

    What should I do if I do not understand a condition?

    Ask the provider to explain it in plain language before you decide. Do not rely on a guess about fees, interest or access.

  • How to Read Your First MoneyCQ Week Beyond the Score

    How to Read Your First MoneyCQ Week Beyond the Score

    Your first MoneyCQ week can produce a number that feels like a verdict. It is better understood as a dashboard. The score is a signal about the choices you made, the pressures you faced, and the systems you built. To improve, look underneath the number and ask which decisions moved it.

    Start with the four visible questions

    MoneyCQ describes financial health through four practical lenses: earn, manage, grow, and survive. They are connected but not identical. You may earn more without managing well. You may save consistently without taking enough care of resilience. The score becomes useful when you can see the balance between them.

    After your first week, write one sentence for each lens. What brought money in? What did you spend or reserve? Did anything grow over time? What protected you from a setback? This turns a score into a story you can act on.

    Earn: look at reliability, not only the headline pay

    A job with higher pay can also bring longer hours, more fatigue, less security, or higher costs. Review how your income fitted the life around it. Did the work cover basic costs? Did a side hustle require equipment or time that reduced the benefit? The best income decision is not always the largest number; it is the one that supports sustainable cash flow.

    Manage: follow the ledger

    The ledger is where the score meets reality. Look for repeated small outflows, large fixed commitments, and decisions that reduced flexibility. Ask whether you planned from net pay or spent as if gross income were available. If the week felt tight, identify the pressure point rather than blaming the whole plan.

    A strong management habit is to decide what each incoming dollar is for before the week becomes busy. Housing, bills, food, saving, debt, and optional spending all compete for the same pool. A visible plan makes the trade-offs easier to explain.

    Grow: separate progress from excitement

    Growth is not just finding a dramatic opportunity. It can mean adding to savings, reducing costly debt, building skills, or choosing a measured investment. Before taking risk, understand what could be lost, how quickly you might need the money, and whether the decision is diversified or concentrated.

    MoneyCQ uses a simulated world so you can test choices without placing real money at risk. Treat the result as practice, not a promise about what will happen outside the game.

    Survive: notice the protections you almost needed

    Resilience is often invisible when nothing goes wrong. Insurance, a cash buffer, a stable home, manageable debt, and enough recovery time may feel boring during a calm week. Their value becomes clear when a shock arrives.

    Review what would have happened if one event had been worse. Would you have had cash? Could you reduce a cost? Which asset or decision was exposed? This is not an invitation to fear every possibility. It is a way to build a plan before pressure makes the choice for you.

    Choose one experiment for week two

    Do not try to change everything at once. Choose one experiment: save before spending, compare a recurring cost, wait before an impulse purchase, review insurance, or find a way to improve income without adding unsustainable fatigue. At the end of the next week, compare the decision and the result.

    The score matters because it makes progress visible. It does not replace judgement. Your real advantage is learning to connect the number to the habit underneath it, then repeating the habits that make your future choices stronger.

    Sources and further reading

    MoneyCQ’s own Cash Quotient explanation describes the score as a blend of earning, managing, growing, and surviving with money. Use the in-game weekly summary as the primary record of your simulated decisions.

    FAQs

    Is a high CQ score a guarantee of success?

    No. It is a game measure of simulated financial decisions, not a guarantee about real-life outcomes.

    What should I inspect first after a week?

    Inspect the weekly summary and ledger, then connect the result to earn, manage, grow, and survive.

    Can earning more lower my score?

    It can if higher income is outweighed by new costs, debt, fatigue, or weaker management decisions in the simulation.

    What is a good week-two experiment?

    Choose one manageable change, such as saving first, pausing before impulse spending, or reviewing a recurring cost.

    Should I copy a successful in-game investment?

    No. Use the simulation to practise thinking about risk and trade-offs rather than treating it as a real-world recommendation.

    Why look at resilience during a calm week?

    Protections such as buffers and manageable commitments are easiest to build before a financial shock arrives.

  • Build a Small Emergency Fund Without Waiting for a Perfect Income

    Build a Small Emergency Fund Without Waiting for a Perfect Income

    Financial resilience does not begin when you have a huge balance. It begins when some money is deliberately kept available for a problem you did not plan for. A broken appliance, an urgent trip, a health cost, or a gap in income can turn a normal week into a difficult one. A small buffer cannot solve every problem, but it can create time and choices.

    Give the fund one clear job

    An emergency fund is for unplanned costs that are important enough to need attention and unusual enough not to belong in your normal weekly spending. Regular groceries and scheduled bills are part of a budget. A sudden repair or unexpected loss of income is the kind of event a buffer is designed to help with.

    Write the job down in plain language. “Money for surprises that protect my basic life” is more useful than a vague promise to save. A clear purpose also helps you decide when to use the money and when to leave it alone.

    Start with the first reachable milestone

    Choose a first target that feels possible, such as $25, $50, or the cost of one common repair. The exact amount depends on your situation. The important step is creating a visible reserve and a habit of adding to it.

    If income changes from week to week, use a flexible amount rather than a promise that will make the rest of the budget fail. A small regular transfer can be more sustainable than an ambitious plan that is abandoned after one difficult month.

    Make saving automatic when possible

    People often intend to save what remains after spending, but “what remains” can disappear. The Consumer Financial Protection Bureau suggests creating a savings plan and using automatic deposits as one way to make saving more consistent: saving for emergencies and the future.

    Automation is not magic. Check that the amount and timing fit your cash flow. If an automatic transfer causes an overdraft or makes an essential bill difficult to pay, reduce it and choose a safer schedule.

    Keep it safe and accessible

    The right home for emergency money should protect it from casual spending while keeping it available when a genuine need arrives. A separate savings account may help. Some people use a labelled envelope or another clear method while building the first milestone. Consider safety, access, fees, and local rules.

    An emergency fund is not the same as a long-term investment. The job of a small buffer is stability and access, not chasing the highest possible return. Money placed somewhere difficult to access may not help when the repair needs to happen today.

    Use it without shame when the emergency is real

    A buffer that is never used is not automatically a successful buffer. If a genuine unplanned cost arrives, using the money can be exactly what it was designed for. Afterward, review what happened, adjust the target if needed, and restart the habit.

    MoneyCQ models this lesson through financial shocks. Skipping protection can make a setback harder, while a reserve can give you a better recovery path. In real life, resilience is built from the same ingredients: planning, a little available cash, and the willingness to rebuild after a drawdown.

    Sources and further reading

    The CFPB’s essential emergency-fund guide explains what a fund is for, how to build one, and why even small savings can help. The examples here are general education, not personal financial advice.

    FAQs

    What is an emergency fund?

    It is money set aside for important, unplanned costs or a sudden change in income.

    How much should I save first?

    Choose a reachable first milestone based on your circumstances, such as the cost of a common repair or another meaningful small amount.

    Should emergency savings be invested?

    A small emergency reserve should prioritise safety and access, because it may be needed quickly.

    How can I make saving more consistent?

    Use a clear goal and, where it fits your cash flow, an automatic transfer on a suitable schedule.

    When should I use the fund?

    Use it for a genuine important expense that was not part of your normal planned spending.

    What should I do after using it?

    Review the event, adjust the target if necessary, and restart regular contributions when you can.

  • The $100 Decision: A Money Story About Trade-Offs

    The $100 Decision: A Money Story About Trade-Offs

    This is a fictional story, but the decision will feel familiar. A payment arrives. A tempting purchase appears. At the same time, something useful needs attention. The money is not enough for everything, so the real question becomes: what deserves the money first?

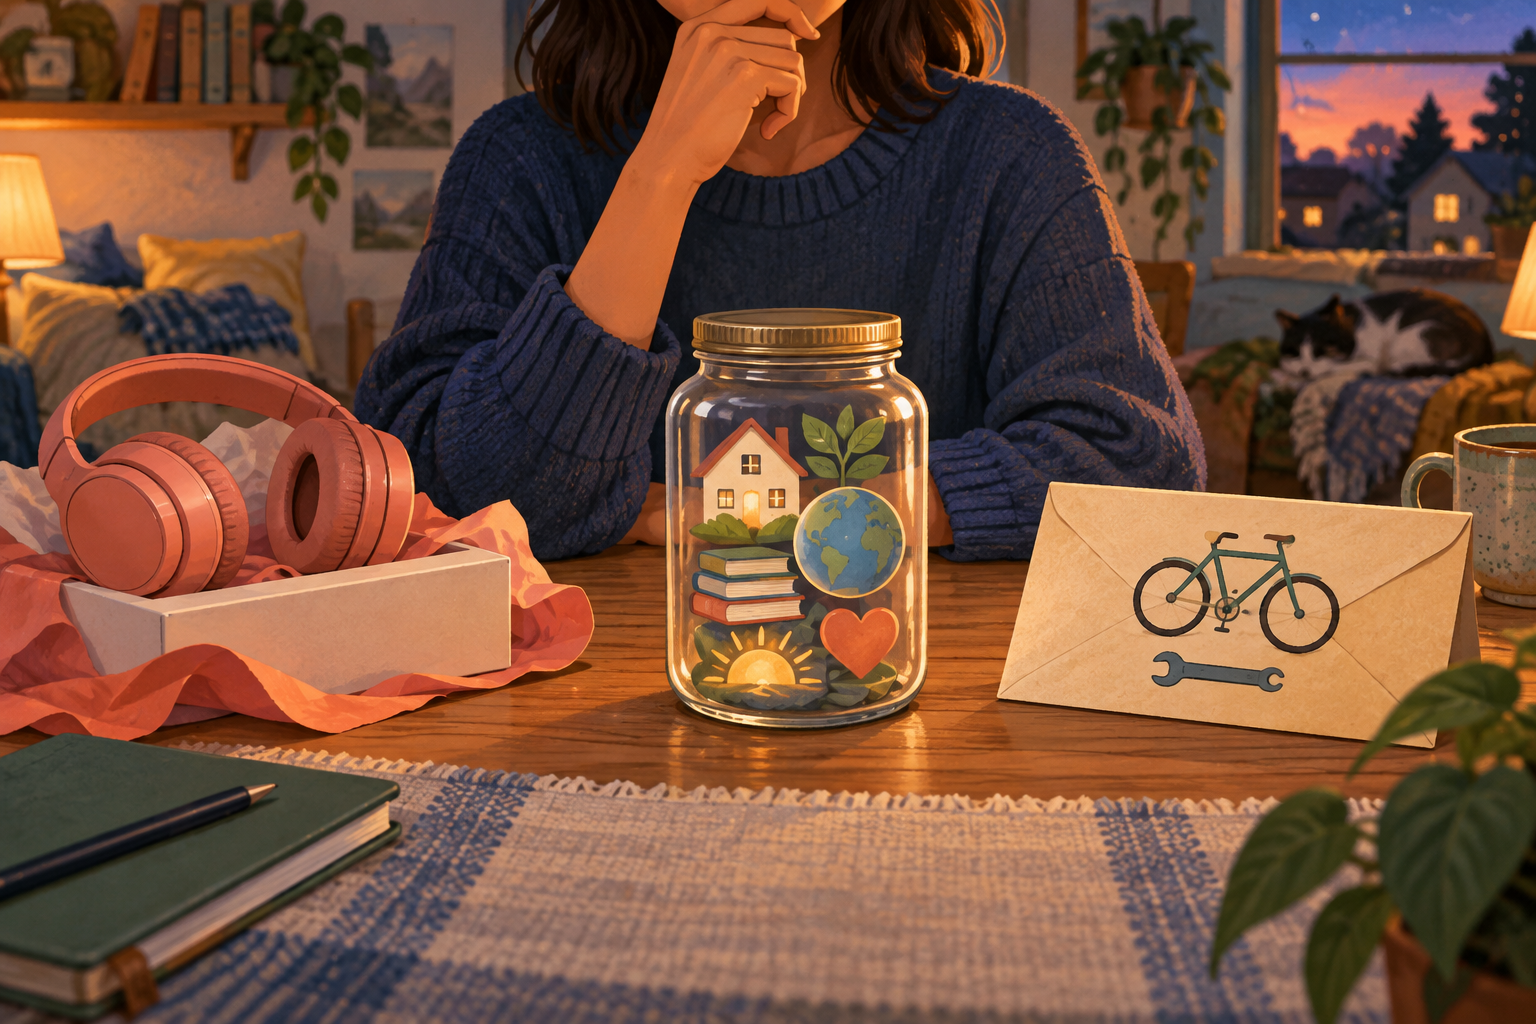
    Mia receives $100 for helping at a family event. She has been thinking about a pair of headphones, her bicycle needs a repair, and she wants to build up the savings jar she started last month. None of the choices is automatically perfect. Each one points her life in a different direction.

    The first reaction is to spend it all

    Mia opens a shopping app and finds headphones on sale. The price is $100, which makes the decision feel simple: the money covers the item. But “can pay” and “can afford” are not always the same question. If she spends everything, she also gives up the ability to handle the bicycle repair or add to savings.

    The discount creates urgency, but it does not create a need. Mia closes the app for a moment. That pause is not a refusal. It is a way to let priorities speak before the purchase button does.

    The repair changes the picture

    The bicycle is Mia’s main way to get to school and activities. The repair is not exciting, but it supports a responsibility she already has. If the bicycle becomes unsafe or unusable, the cost may become more than money: extra time, a different transport plan, or a missed activity.

    Mia decides the repair is the first claim on the $100. She asks for the exact price instead of guessing. The answer is $45. Now the decision is no longer “headphones or nothing.” She has $55 left and more information than she had ten minutes earlier.

    Saving turns the leftover into an option

    Mia puts $35 into her savings jar. The amount is not dramatic, but it gives future Mia more choices. A reserve can help with an unplanned cost, and a named goal can make saving feel connected to something real. The Consumer Financial Protection Bureau describes an emergency fund as money set aside for unplanned expenses such as repairs or a loss of income: emergency-fund guidance.

    That leaves $20. Mia still wants the headphones. She decides to wait a week and see whether she still wants the same pair. If she does, she can compare prices and decide whether the purchase fits her wider plan. If the excitement disappears, the money has already done useful work elsewhere.

    The decision is not about being “good”

    Mia did not win because she avoided every want. She made the trade-off visible. The bicycle supported a current responsibility. The savings created resilience. The headphones remained a possible future choice instead of an automatic present choice.

    This is how a money story becomes a skill. You name what the money can do, identify what matters most, and accept that choosing one path means postponing another. A budget works in the same way: it is a plan for allocating limited money across needs, goals, and wants.

    How MoneyCQ makes the trade-off visible

    In MoneyCQ, decisions feed several parts of the Cash Quotient at once. A purchase may support lifestyle but reduce savings. An emergency repair may lower cash today while protecting resilience. The point is not to find one answer that works for every player. It is to see the consequences clearly enough to choose on purpose.

    When a real-life decision arrives, try Mia’s three questions: What responsibility does this money protect? What option does saving create? If I wait, what information might I gain? The answers will not remove every trade-off, but they can make the next move calmer.

    Sources and further reading

    For practical budgeting ideas, read Sorted’s guide to building a budget. This story is fictional and does not describe a real person.

    FAQs

    Is Mia a real person?

    No. Mia and the events in this article are fictional examples used to explain trade-offs.

    Did Mia make the only correct choice?

    No. Different people can reasonably prioritise different needs and goals with the same amount of money.

    Why did Mia ask for the repair price first?

    She needed accurate information before deciding how much money the responsibility would require.

    Why save part of the money?

    Saving creates an option for a future goal or an unplanned cost instead of using every dollar immediately.

    Does choosing a want make someone bad with money?

    No. A want can be a valid choice when it is deliberate and fits the available money and priorities.

    What are the three questions in the story?

    Ask what responsibility the money protects, what option saving creates, and what information waiting might reveal.