Blog

  • What Really Happens When You Tap to Pay?

    What Really Happens When You Tap to Pay?

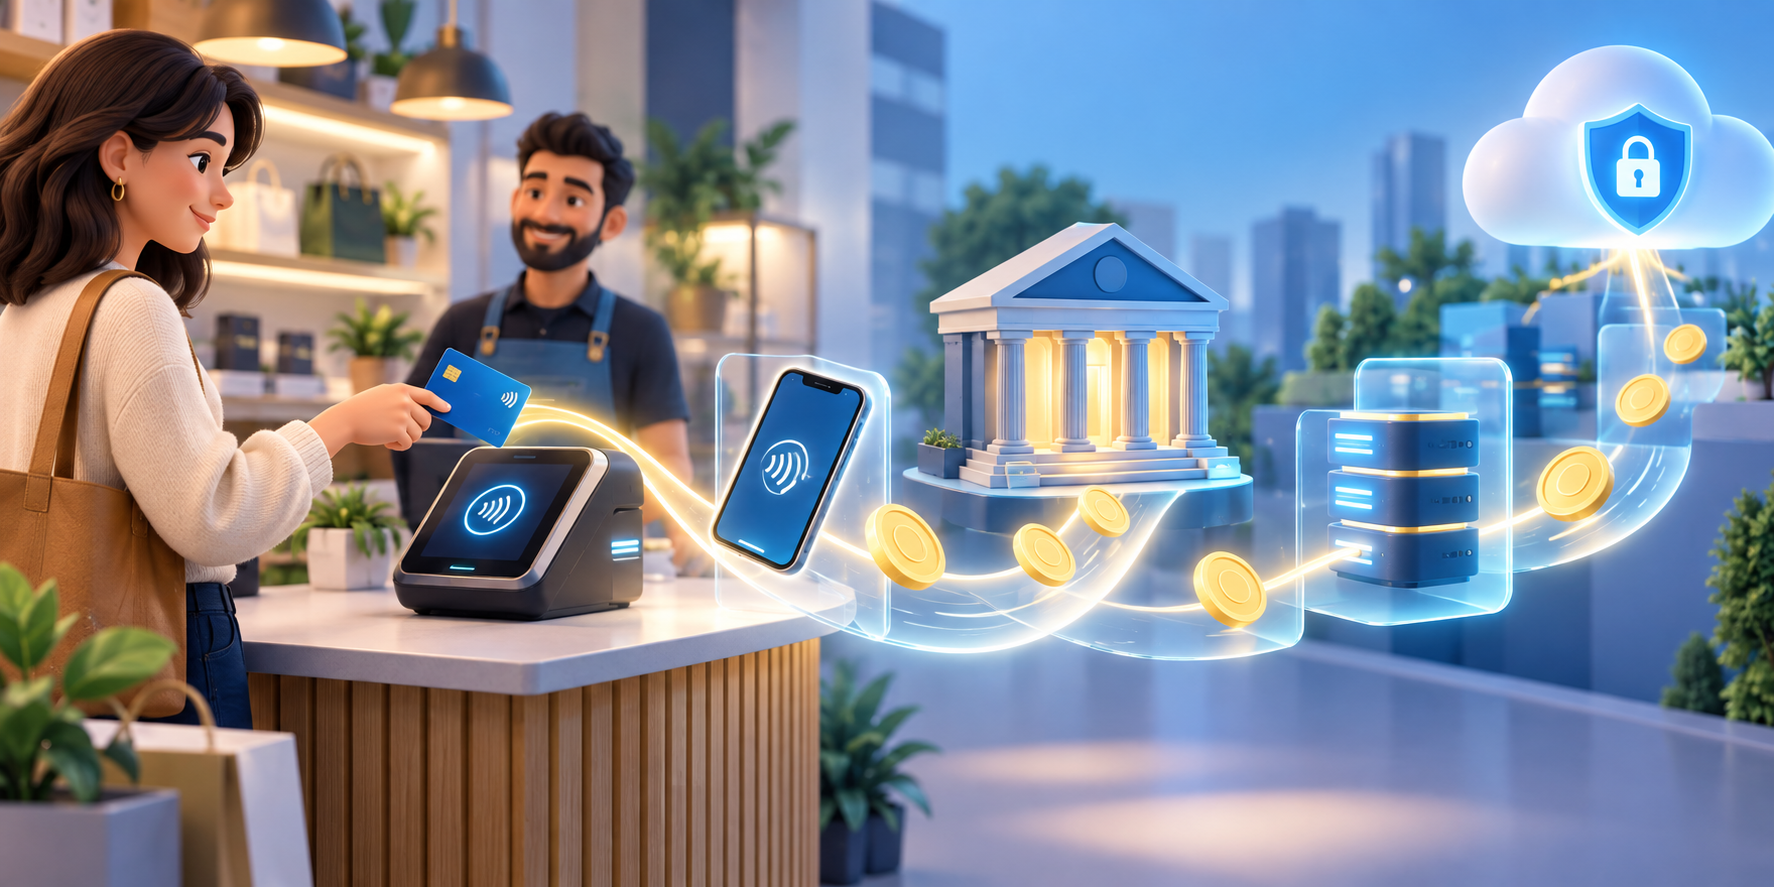
    A tap at a checkout can feel like money has jumped straight from your phone to the shop. In reality, the tap starts a chain of instructions, checks, and records. Understanding that chain helps explain why payments can be fast, why a transaction can be declined, and why the balance in your account changes after the purchase.

    The details vary between countries and payment providers, but the basic idea is consistent: a payment is a transfer of money in exchange for a good or service.

    Step one: choose a payment instrument

    You begin with a payment instrument, such as a debit card, bank payment, or mobile wallet. The instrument is the way you tell the system which account or balance should be used. It is not the same thing as the money itself; it is a way to give an instruction.

    Step two: the shop accepts the instruction

    The merchant uses a terminal or payment gateway to receive the instruction. A physical terminal reads the tap, while an online gateway collects payment details through a digital checkout. The merchant’s system sends the request into the payment network.

    Step three: authorisation checks the request

    Your bank or payment provider checks whether the instruction can be approved. It may check the account balance, security signals, limits, and whether the transaction appears valid. If the request is declined, the payment has not completed even though you may have seen a message on the terminal.

    Step four: clearing prepares the transaction

    After authorisation, clearing passes the transaction information between the relevant institutions. The payment network, your bank, and the merchant’s bank need to agree on what happened and how the transaction should be processed. This is one reason a payment can show as pending before it is final.

    Step five: settlement completes the movement

    Settlement is the stage where the funds are transferred and the transaction is completed in the accounts involved. The Reserve Bank of New Zealand describes the process as instruction, authorisation, clearing, and settlement, with the merchant ultimately receiving funds in its account: How do card payments work?

    Why a digital payment still needs a ledger

    No pile of coins moves through the air when you tap. Instead, records are updated across connected systems. Your account records a debit, the merchant’s records show a sale, and the payment system carries messages that allow the institutions to reconcile the transaction.

    That is why keeping track of digital spending matters. A tap can feel less tangible than handing over cash, but it still reduces the money available for later decisions. Notifications, account statements, and a simple spending log make the invisible movement visible again.

    What a tap can teach you about money

    Digital payment technology makes convenience possible, but convenience is not the same as affordability. Before tapping, check the price, the account you are using, and the trade-off with your current goal. After tapping, make sure the transaction appears as expected and keep your security details private.

    MoneyCQ turns this kind of invisible process into a visible decision. The ledger shows money arriving, leaving, and being reserved for different purposes. The more clearly you can see the path, the easier it is to manage the next choice.

    Sources and further reading

    For a deeper overview of New Zealand’s payment infrastructure, read the Reserve Bank’s payments landscape primer. Payment rules and timing can differ by country and provider.

    FAQs

    Does tapping move physical cash?

    No. It sends an electronic instruction that results in account records and funds being transferred.

    What is authorisation?

    Authorisation is the check by a bank or payment provider to decide whether the payment request can be approved.

    What is clearing?

    Clearing is the process of passing and checking payment information between the institutions involved.

    Why can a payment be pending?

    A pending status can mean the transaction has been authorised but has not yet completed final processing and settlement.

    Why should I watch digital spending?

    Digital payments are convenient but still reduce the money available for future spending, saving, or emergencies.

    What should I do if a tap is declined?

    Check the account, payment method, limits, or security requirements, and use the provider’s official support channel if the problem continues.
  • The Seven-Day Needs vs Wants Challenge

    The Seven-Day Needs vs Wants Challenge

    “Is this a need or a want?” is a useful question, but it can become a lecture if it never reaches real decisions. The Seven-Day Needs vs Wants Challenge turns it into a small experiment. For one week, notice the choices you make, pause before optional spending, and see what changes when you give every purchase a job.

    The aim is not to label every want as wrong. Wants make life enjoyable. The aim is to become better at choosing them deliberately instead of letting a hurry, a discount, or someone else’s excitement choose for you.

    What counts as a need?

    A need is something that supports health, safety, basic living, or an important responsibility. Food, necessary transport, a place to live, and essential school or work items are common examples. Needs still have choices inside them: one food option may cost more than another, and a need can sometimes be met in several ways.

    A want is something you would like but could postpone, replace, borrow, or live without for now. Entertainment, treats, upgrades, and impulse purchases often sit here. A want is not silly or shameful. Naming it honestly gives you control over when and how you buy it.

    The challenge rules

    For seven days, keep a simple note on your phone or a sheet of paper. Record each purchase or planned purchase, whether it was a need or a want, how you felt before buying, and whether the purchase helped with a goal. If you do not spend, record one moment when you chose not to.

    Use five labels: need now, need later, want planned, want impulse, and not sure. The “not sure” label matters. It gives you room to learn without pretending every decision is obvious.

    Day one: notice without changing

    On the first day, simply observe. Do not try to be perfect. Notice the trigger: hunger, boredom, a notification, a friend, a time limit, or a convenient checkout button. You are collecting clues about how decisions happen.

    Days two and three: add a pause

    Before buying a want, wait ten minutes. Ask three questions: What problem does this solve? What else could I do with the same money? Will I still want it tomorrow? A short pause separates a real preference from a passing feeling.

    Days four and five: connect spending to goals

    Choose one small goal, such as a game, a book, a trip, or an emergency buffer. Put the price beside the goal. When you skip or delay a want, write down the amount you kept available. You are not “missing out”; you are making the trade-off visible.

    Days six and seven: design your own rule

    Look back at the week. Which purchases felt worth it? Which were forgotten quickly? Create one personal rule, such as “I wait overnight for unplanned purchases,” “I compare two prices,” or “I save part of every payment before spending.” A good rule is small enough to repeat.

    What the challenge teaches

    The challenge shows that budgeting is not only arithmetic. It is attention, timing, and priorities. Sorted describes a budget as a plan for where incoming money should go, including regular and irregular costs; see Sorted’s budgeting guide. Your seven-day notes provide the evidence for building a plan that reflects real behaviour.

    In MoneyCQ, each choice feeds the wider story. A small purchase can affect saving, resilience, and the options available later. The challenge works the same way outside the game: one decision rarely changes everything, but repeated decisions create a pattern you can see and improve.

    Sources and further reading

    Use the Sorted money-mindset guide for more on habits, goals, and the emotional side of spending.

    FAQs

    Does calling something a want mean I should never buy it?

    No. A want can be a sensible purchase when it fits your priorities and available money.

    What if I cannot tell whether something is a need?

    Use the “not sure” label and ask whether the purchase supports health, safety, basic living, or a real responsibility.

    How long should the pause before buying last?

    The challenge suggests ten minutes for a quick experiment, while an overnight pause can help with larger or unplanned wants.

    What should I write down during the challenge?

    Record the purchase, its label, the feeling or trigger before buying, and whether it supported a goal.

    Can children do this activity?

    Yes. Adults can help children use simple labels and discuss choices without shaming them.

    What is the best result after seven days?

    The best result is a repeatable personal rule based on what you noticed, not a perfect record with no spending.

  • Gross Pay vs Take-Home Pay: Where Your Money Goes First

    Gross Pay vs Take-Home Pay: Where Your Money Goes First

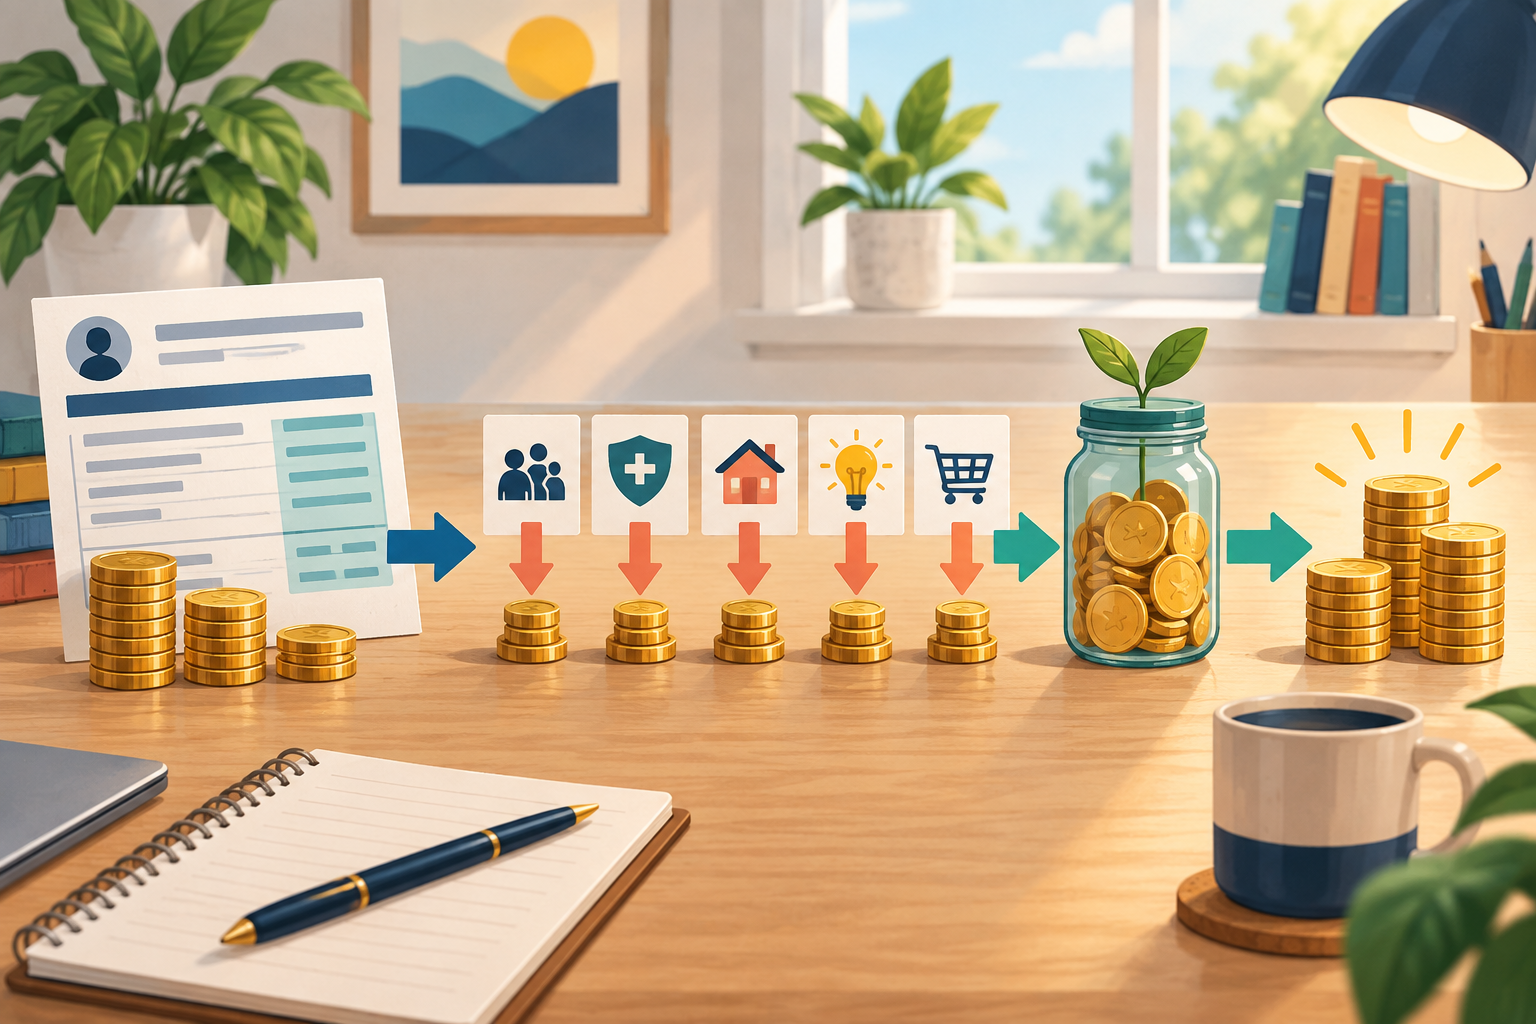
    A new job can come with a number that looks wonderfully large. Then payday arrives and the amount in your account is smaller. That is not a trick, and it does not mean someone has lost your money. It means your gross pay has passed through the deductions that apply before you receive your take-home pay.

    Understanding the journey from salary to spendable money is one of the most useful money skills you can build. It helps you plan honestly, compare jobs fairly, and make sense of the payslip in MoneyCQ or in real life.

    Gross pay is the starting number

    Gross pay is the amount agreed before deductions. It might be shown as an annual salary, an hourly rate, or a weekly amount. If a job pays $25 an hour and you work 20 hours, the gross pay for that week is $500 before anything is taken out.

    Gross pay is useful for comparing the size of different jobs, but it is not the amount you can automatically spend. A salary offer can look attractive while a different job with better hours, lower travel costs, or more reliable income leaves you with more useful money overall.

    Take-home pay is what reaches your account

    Take-home pay, sometimes called net pay, is the amount left after the deductions that apply to you. It is the number that should anchor your weekly or monthly spending plan. Rent, food, transport, saving, and fun all have to fit inside this amount.

    The exact deductions depend on where you live, your income, your tax settings, and the choices you make. In New Zealand, an employer generally deducts PAYE and the ACC earners’ levy from salary or wages. Other deductions may include KiwiSaver contributions, student-loan repayments, charitable payroll giving, or other authorised amounts. Inland Revenue explains that the tax code supplied to an employer affects how much PAYE is deducted: IRD guidance on salary and wages.

    Why the difference matters when you plan

    Imagine two people each seeing a gross weekly pay of $900. One has a long commute, a student-loan deduction, and higher insurance costs. The other works close to home and has fewer deductions. Their gross pay is identical, but their available cash is not.

    A realistic plan begins with take-home pay. First list regular commitments such as housing, utilities, transport, and debt payments. Then allow for flexible essentials such as groceries. After that, give saving and irregular costs a place. Only then should you decide how much is available for optional spending.

    Read a payslip like a money map

    When you receive a payslip, look for four landmarks: the pay period, gross earnings, deductions, and net pay. Check whether the hours or salary shown match what you expected. Notice whether deductions are fixed, percentage-based, or changing. If a number is unfamiliar, ask the employer or payroll team rather than guessing.

    A payslip is also a record of trade-offs. A retirement contribution may reduce today’s cash while building a locked or long-term balance. A student-loan repayment may feel like a loss from the week’s budget, but it is reducing a liability. Seeing every line helps you understand why your cash flow looks the way it does.

    How this appears in MoneyCQ

    In MoneyCQ, the payslip flow turns an abstract salary into a lived decision. Gross pay comes in, deductions are shown, and the amount available for the week becomes real. That makes it easier to test choices: Can you afford a higher rent? What happens if you save first? Does a second income stream actually cover the extra costs it creates?

    The lesson is simple: build your life around money you can use, not money that only appears at the top of an offer letter. Gross pay tells you the size of the starting pool. Take-home pay tells you what the next decision can actually be.

    Sources and further reading

    For a New Zealand example of progressive income tax rates and PAYE deductions, see Inland Revenue tax rates. Rules differ by country, so use the official tax authority for the region that applies to you.

    FAQs

    What is gross pay?

    Gross pay is the amount earned before tax and other deductions are taken out.

    What is take-home pay?

    Take-home pay is the amount left after the deductions that apply to your pay have been made.

    Which number should I use for a budget?

    Use take-home pay because it is the amount available to cover spending and saving.

    Why can two people with the same salary receive different amounts?

    Tax settings, retirement contributions, student-loan payments, and other deductions can differ between people.

    What should I check on a payslip?

    Check the pay period, earnings, deductions, and net amount against what you expected.

    Are pay deductions always bad?

    No. Some deductions fund taxes, insurance, retirement saving, or debt repayment, even though they reduce the cash available today.

  • How CQ Is Different From IQ and EQ

    Three letters. One of them actually goes up when you learn.

    IQ measures how smart you are. EQ measures how well you handle people. CQ — Cash Quotient — measures how well you handle money. And unlike IQ, CQ isn’t fixed at birth: it’s a skill, which means it can be trained.

    The eight factors

    Your CQ is built from eight factors, each one a slice of how you handle money:

    • Spending habits — groceries to lifestyle creep; overdrafts drag you down.
    • Saving discipline — buffers, deposit streaks, and the emergency fund.
    • Risk tolerance — measured exposure, not gambling.
    • Income streams — salary, side business, rentals, investments.
    • Debt management — loans, student debt, vehicle finance.
    • Investment behaviour — diversification and holding beats churning.
    • Financial resilience — weeks of buffer, recovery after a crash.
    • Lifestyle choices — health, fatigue, reputation, and the consequences.

    The nine bands

    The score runs 0–1000 across nine bands, from Ruined all the way to Mogul — with a monthly delta so you can see the trend, not just the number. That means progress is visible: every good decision nudges the score, and every bad one shows up too.

    Why a simulated life is the safest place to learn

    Nobody gets good at money without making mistakes. The question is where you make them. In a simulated life, the car breakdown costs you in-game dollars and the lessons are real — but the consequences stay on the screen. You get to feel why the emergency fund matters, why insurance exists, and why debt compounds, all before it’s your actual money on the line.

    IQ is what you’re born with. EQ is what you learn from people. CQ is what you level up by living — week by week, decision by decision.

    Where to start

    MoneyCQ is a two-year life-sim that turns your money choices into one living number. Start your first week at app.moneycq.com — 104 weeks, one score, and the safest place to make your first financial mistakes.

    Want to see how these choices move your score? MoneyCQ is a life-sim where your Cash Quotient rises and falls with decisions just like these. Start your first life now at app.moneycq.com.

  • The Real Meaning of Being ‘Rich’

    What does it mean to be rich? Most people picture the same image: big house, fancy car, expensive stuff. But that image is misleading — because looking rich and being rich are completely different things, and the real meaning is much better.

    Rich-looking vs rich

    Rich-looking means spending money in ways other people can see. Being rich means having money — saved, invested, working for you. The rich-looking person can be one paycheque from trouble; the rich person can be quietly comfortable in an ordinary house. One is a performance. The other is a position.

    Income vs wealth

    A big income isn’t the same as wealth. Wealth is what’s left — the assets, the savings, the buffer. Someone earning a fortune and spending it all is rich-looking. Someone earning modestly and keeping more than they spend is building wealth. The gap between what you earn and what you keep is where richness actually lives.

    The real definition

    The truest meaning of rich: options. The freedom to say no to a bad deal, to survive a shock without panic, to choose work you care about, to help people you love. Money buys these options. A person with options is rich, no matter what their house looks like. A person trapped by payments isn’t, no matter what they drive.

    Rich in other ways

    There’s more to richness than money: time, health, relationships, freedom, purpose. Money is a tool for buying some of those — but only some. The richest people usually understand that money serves a life worth living; they don’t mistake the tool for the goal.

    What it means for you

    You can start being rich right now — not in the flashy sense, but in the real one: save first, keep your plan, build your options. The kid who learns to be rich-in-options becomes the adult who actually is.

    How this lifts your CQ

    Every lever of your Cash Quotient points the same direction: building options. The score isn’t about looking good with money. It’s about being good with money — and that’s what real richness is.

    Rich-looking is what you spend. Rich is what you keep. Wealthy is what you can do with what you keep.

    Try it in class

    Debate the question: if you couldn’t show anyone your money, would you still want to be rich? Then write the class definition of richness and compare it with the ads they see every day. The gap between the two is the lesson.

    Want to see how these choices move your score? MoneyCQ is a life-sim where your Cash Quotient rises and falls with decisions just like these. The game is live — build a life and watch your CQ move at app.moneycq.com.

  • How to Build a Money Plan for School

    School runs on a rhythm — terms, trips, events, and the regular costs that come with them. Most students react to that rhythm, scrambling when a cost lands. A money plan for school flips it: you know what’s coming, and you’re ready before it arrives.

    Step 1: Map the school year’s money moments

    Write down the predictable costs: lunch money or lunches, bus fares, school supplies, trips and excursions, uniform items, fundraising events, birthday gifts for friends, and the ‘fun’ costs — school socials, mufti days, canteen treats. Some are big, some small, but they’re all predictable if you look at the calendar.

    Step 2: Build the term bucket

    Instead of dealing with each cost as it hits, create a term bucket: a separate jar or account fed weekly with a small amount. When the trip fee arrives, it comes out of the bucket — no panic, no asking, no borrowing. Even $5 a week becomes a quiet $60–70 by the end of the term.

    Step 3: Separate the regular from the one-offs

    • Regular costs (lunches, transport) come out of the weekly plan.
    • One-offs (trips, events, supplies) come out of the term bucket.
    • Fun money is separate and allowed to run out — that’s the point.

    Step 4: Review each term

    At the end of every term, look back: what did the plan miss? What cost more than expected? Adjust the weekly amount and the bucket for next term. One term of data makes the next term’s plan much better.

    The unexpected bonus

    The plan does more than cover costs. When the trip fee arrives and you’re ready, you feel the calm that most people never experience around money. That calm is the skill you’re really practising — and it carries into every future money situation.

    How this lifts your CQ

    Saving discipline and financial resilience are two levers of your Cash Quotient. A school-year plan is a real budget, on a real timescale, with real consequences — the perfect training ground.

    School teaches you a lot. A money plan for school teaches you the part they don’t test: being ready.

    Try it in class

    Build a class calendar of the school year’s money moments, then have every student draft their term bucket amount. Compare the plans — the costs most people forgot are the best part of the discussion.

    Want to see how these choices move your score? MoneyCQ is a life-sim where your Cash Quotient rises and falls with decisions just like these. The game is live — build a life and watch your CQ move at app.moneycq.com.

  • Why Money Doesn’t Grow on Trees

    You’ve heard it a hundred times: ‘money doesn’t grow on trees.’ It’s usually said as a gentle no — but the saying is actually a complete lesson in disguise. Unpack it, and you’ll understand more about money than most adults do.

    The literal part

    Money isn’t a crop. It doesn’t ripen, fall, and get picked. It has to be made — earned through work, or created through value. Nothing in your pocket arrived by accident. Someone worked for it, traded for it, or saved it from other work. That’s the first layer: money is manufactured by effort.

    The deeper part: scarcity

    The saying is really about scarcity — the fact that money is limited and choices have costs. If money grew on trees, everyone could have everything and nothing would be scarce. It doesn’t, so we choose: spend here, not there; buy this, not that. Scarcity is the engine of every budget, every price, and every decision you’ll ever make with money.

    The part nobody says: value

    Here’s the twist the saying hides: money doesn’t grow on trees, but value can grow anywhere you plant it. Skills grow. Businesses grow. Knowledge grows. The people who understand the saying don’t just accept scarcity — they plant value. The money follows the value, not the other way around.

    What it means for you

    When someone says ‘money doesn’t grow on trees’, they’re really saying: this money is limited, it represents real work, and your choice matters. The respectful response is to treat money that way — and to plant your own trees: skills, habits, and value that will grow long after the pocket money is spent.

    How this lifts your CQ

    Income streams and lifestyle choices are two levers of your Cash Quotient. The kid who understands where money really comes from makes different choices than the kid who thinks it appears.

    Money doesn’t grow on trees — but value does. Plant skills, and the money follows the harvest.

    Try it in class

    Ask the class to find the ‘work’ inside everyday money: every item in the room has a chain of people behind it. Then flip it: what could each student ‘plant’ this term — a skill, a habit, a project — that will create value later?

    Want to see how these choices move your score? MoneyCQ is a life-sim where your Cash Quotient rises and falls with decisions just like these. The game is live — build a life and watch your CQ move at app.moneycq.com.

  • The Basics of Investing (Kid-Safe Version)

    Investing sounds like an adult thing — and mostly, it is. But the concepts are for everyone, and understanding them early is a superpower. Here’s the kid-safe version: what investing means, how it differs from saving, and what you can do with it now.

    What investing is

    Saving is putting money somewhere safe to use later. Investing is buying something you expect to grow in value — a tiny piece of a company (shares), a loan to a government (bonds), or a share in a basket of things (funds). The idea: your money works and grows, instead of just waiting.

    The honest risk warning

    Here’s the part adults sometimes skip: investing can lose money. Values go up and down, and there’s no guarantee. That’s why investing is usually for money you won’t need soon, and why savings accounts exist for the money you will. The rule: don’t invest money you can’t afford to watch fall.

    The three ideas that matter

    • Risk and reward travel together. Higher potential growth usually means higher potential loss. Savings are calm and modest; investing is bouncy and potentially bigger.
    • Time smooths the ride. The longer you hold, the more the ups and downs average out. That’s why investing is for years, not weeks.
    • Compounding does the heavy lifting. Growth grows — the snowball effect again. Time is the magic ingredient.

    Why owning is different from lending

    When you lend money (a bond, a savings account), you’re promised repayment plus interest. When you own (shares), you own part of the business — you rise and fall with it. Ownership is riskier and can grow more. Most people use both, in different amounts, depending on their age and goals.

    What a kid can do now

    You probably can’t open a real investment account yet — that needs a grown-up and real money. What you can do: save first (the base), learn the concepts (this article), follow a real market or company for fun, and discuss investing with your family. The knowledge is the investment that starts paying immediately.

    How this lifts your CQ

    Investment behaviour is one of the eight levers of your Cash Quotient. Understanding the basics now means you’ll never be the person who panics, gambles, or gets scammed later.

    Investing is letting your money work so you don’t have to — but first you have to understand how the work is done.

    Try it in class

    Follow a real company or a pretend ‘class fund’ for a month: track its value weekly, watch it move, and discuss why. No real money — just the experience of watching an investment breathe.

    Want to see how these choices move your score? MoneyCQ is a life-sim where your Cash Quotient rises and falls with decisions just like these. The game is live — build a life and watch your CQ move at app.moneycq.com.

  • How to Track Your Spending

    Spend-Tracker Week is the starter. Tracking your spending all the time is the system — and it’s simpler than it sounds. You don’t need to record every cent forever. You need a method so easy it survives real weeks.

    Pick a method that fits you

    • The notebook. A small book, one line per spend. Slow, visible, and completely private.
    • The app. Automatic tracking if you use cards; manual entries for cash. Choose one that takes under a minute a day.
    • The jar system. Physical money split into jars — the jars are the tracker; no writing required.
    • The weekly review. Even without detailed records, a weekly look at your balance and a mental recall of big spends keeps you honest.

    The best method is the one you’ll actually use. A rough notebook beats a perfect app you abandon in week two.

    Track in three categories

    Don’t over-engineer it. Three buckets capture almost everything: Needs (transport, food, school), Wants (fun, treats, extras), and Savings (moved out, so it’s easy to count). If a spend fits none of the three, it’s probably a leak — and the tracker just caught it.

    What the data tells you

    After two or three weeks of honest tracking, the patterns appear: the day you always spend, the trigger that starts the buying, the difference between what you planned and what happened. Tracking doesn’t judge you — it hands you a map. The map shows exactly which line to fix.

    The weekly review ritual

    Once a week, ten minutes: total in, total out, what surprised you, what to change next week. That’s it. The review is where tracking becomes improvement instead of record-keeping. Skip a week? Fine — restart the next week. The system forgives; only abandonment fails.

    How this lifts your CQ

    Spending habits are one of the eight levers of your Cash Quotient. Tracking is the instrument panel for that lever — you can’t steer what you can’t see.

    Tracking isn’t surveillance. It’s a mirror — and mirrors are how you fix your hair before it gets worse.

    Try it in class

    Have the class pick one tracking method and run it for two weeks, then bring the patterns to a discussion: the most common leak, the most common trigger, and the fix each student will try next.

    Want to see how these choices move your score? MoneyCQ is a life-sim where your Cash Quotient rises and falls with decisions just like these. The game is live — build a life and watch your CQ move at app.moneycq.com.

  • Why Sharing Money Can Feel Good

    Most money advice is about keeping money. But some of the best money feelings come from giving it away. Sharing money isn’t the opposite of managing it well — for many people, it’s a core part of managing it well.

    The warm glow is real

    Researchers call it the warm glow: giving activates the same reward centres as receiving. People who give regularly report feeling happier, more connected, and less anxious about money than people who keep everything. The science matches the experience — sharing money feels good because it’s good for you.

    Why giving changes your money story

    Money can feel like a source of worry: never enough, always more to want. Giving breaks that loop. When you choose to share, you’re proving to yourself that money is a tool you control — not a master that controls you. Generous people tend to feel richer, because they’re measuring wealth by what money can do, not just what it can buy.

    The give jar

    The simplest system: add a third jar. Spend. Save. Give. Even a small share — 5% or 10% — makes giving a normal part of every money decision instead of an afterthought. The jar fills, then you choose where it goes: a cause you care about, a person in need, a project that matters to you.

    Choosing where it goes

    • Pick something you actually care about — animals, the environment, people, your school.
    • Give where you can see the difference — a local cause beats a distant one for the feeling.
    • Give to people you know when you can — help a friend, a neighbour, a family member.

    You don’t need money to give

    The habit of giving includes time, skills, and attention: helping with homework, visiting a grandparent, volunteering, sharing what you’re good at. These cost nothing and build the same muscle — and they make the money version feel natural when it comes.

    How this lifts your CQ

    Lifestyle choices and financial resilience are two levers of your Cash Quotient. A healthy money story includes giving — it keeps money in perspective and makes the rest of the score feel less scary.

    Money is a tool, and tools are meant to be used. Sharing some of it is how you prove you own it — not the other way around.

    Try it in class

    Run a class give-jar for a term: the class chooses a cause, contributes a small share of any class earnings, and decides together where it goes. The deciding is as valuable as the giving.

    Want to see how these choices move your score? MoneyCQ is a life-sim where your Cash Quotient rises and falls with decisions just like these. The game is live — build a life and watch your CQ move at app.moneycq.com.