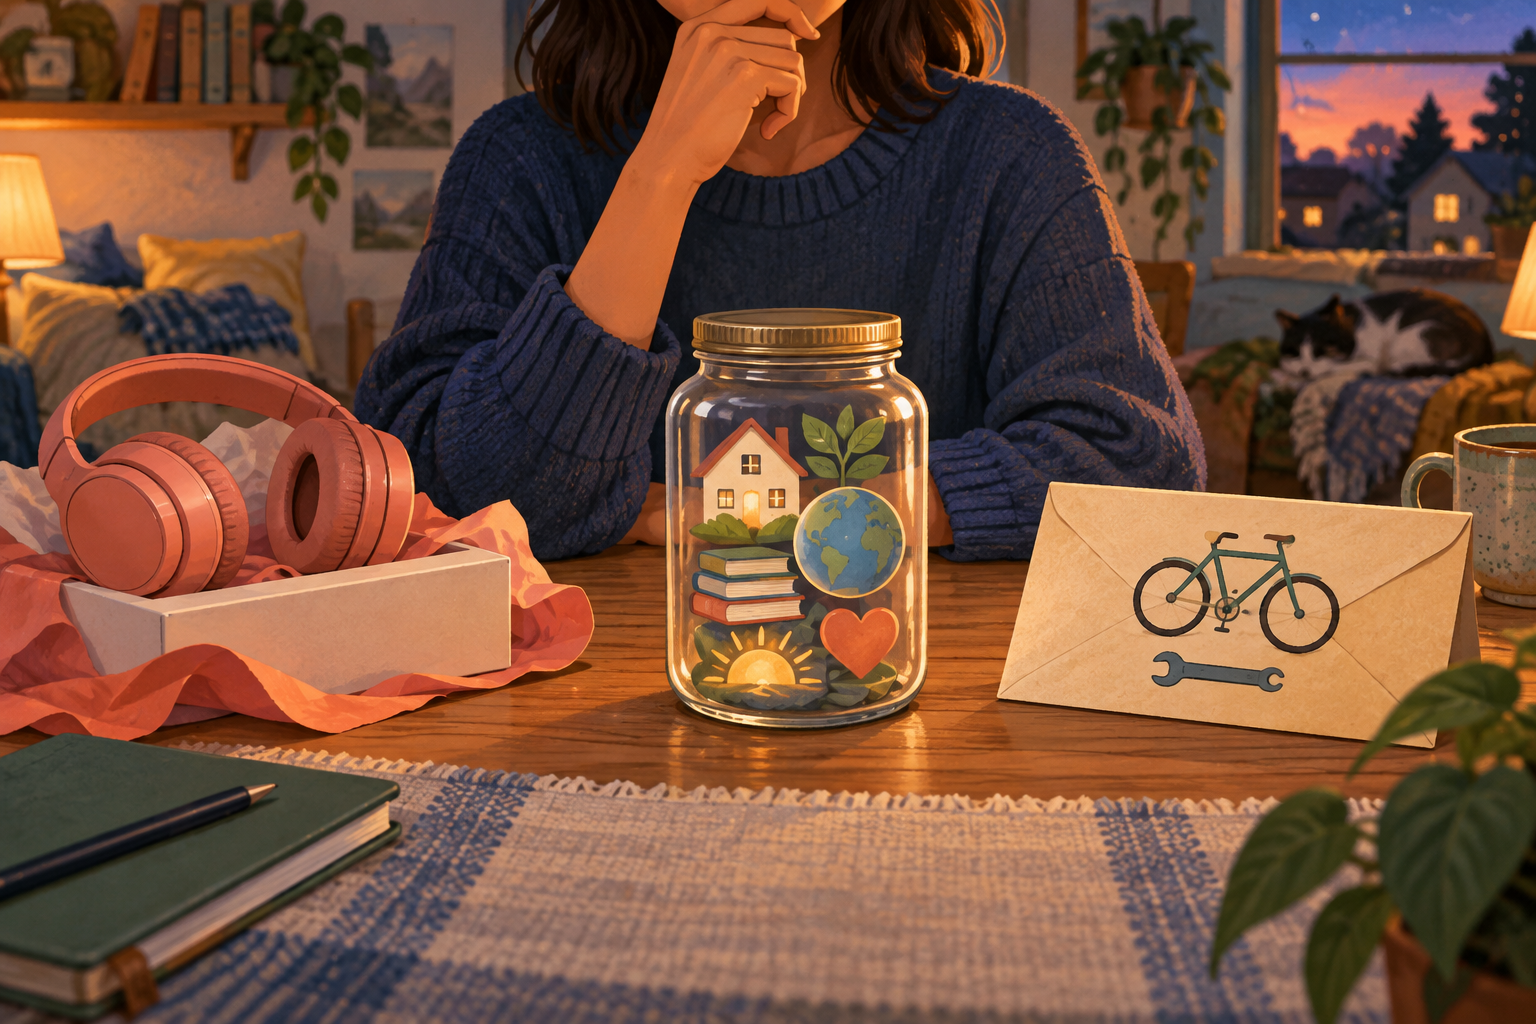
This is a fictional story, but the decision will feel familiar. A payment arrives. A tempting purchase appears. At the same time, something useful needs attention. The money is not enough for everything, so the real question becomes: what deserves the money first?
Mia receives $100 for helping at a family event. She has been thinking about a pair of headphones, her bicycle needs a repair, and she wants to build up the savings jar she started last month. None of the choices is automatically perfect. Each one points her life in a different direction.
The first reaction is to spend it all
Mia opens a shopping app and finds headphones on sale. The price is $100, which makes the decision feel simple: the money covers the item. But “can pay” and “can afford” are not always the same question. If she spends everything, she also gives up the ability to handle the bicycle repair or add to savings.
The discount creates urgency, but it does not create a need. Mia closes the app for a moment. That pause is not a refusal. It is a way to let priorities speak before the purchase button does.
The repair changes the picture
The bicycle is Mia’s main way to get to school and activities. The repair is not exciting, but it supports a responsibility she already has. If the bicycle becomes unsafe or unusable, the cost may become more than money: extra time, a different transport plan, or a missed activity.
Mia decides the repair is the first claim on the $100. She asks for the exact price instead of guessing. The answer is $45. Now the decision is no longer “headphones or nothing.” She has $55 left and more information than she had ten minutes earlier.
Saving turns the leftover into an option
Mia puts $35 into her savings jar. The amount is not dramatic, but it gives future Mia more choices. A reserve can help with an unplanned cost, and a named goal can make saving feel connected to something real. The Consumer Financial Protection Bureau describes an emergency fund as money set aside for unplanned expenses such as repairs or a loss of income: emergency-fund guidance.
That leaves $20. Mia still wants the headphones. She decides to wait a week and see whether she still wants the same pair. If she does, she can compare prices and decide whether the purchase fits her wider plan. If the excitement disappears, the money has already done useful work elsewhere.
The decision is not about being “good”
Mia did not win because she avoided every want. She made the trade-off visible. The bicycle supported a current responsibility. The savings created resilience. The headphones remained a possible future choice instead of an automatic present choice.
This is how a money story becomes a skill. You name what the money can do, identify what matters most, and accept that choosing one path means postponing another. A budget works in the same way: it is a plan for allocating limited money across needs, goals, and wants.
How MoneyCQ makes the trade-off visible
In MoneyCQ, decisions feed several parts of the Cash Quotient at once. A purchase may support lifestyle but reduce savings. An emergency repair may lower cash today while protecting resilience. The point is not to find one answer that works for every player. It is to see the consequences clearly enough to choose on purpose.
When a real-life decision arrives, try Mia’s three questions: What responsibility does this money protect? What option does saving create? If I wait, what information might I gain? The answers will not remove every trade-off, but they can make the next move calmer.
Sources and further reading
For practical budgeting ideas, read Sorted’s guide to building a budget. This story is fictional and does not describe a real person.
FAQs
Is Mia a real person?
No. Mia and the events in this article are fictional examples used to explain trade-offs.
Did Mia make the only correct choice?
No. Different people can reasonably prioritise different needs and goals with the same amount of money.
Why did Mia ask for the repair price first?
She needed accurate information before deciding how much money the responsibility would require.
Why save part of the money?
Saving creates an option for a future goal or an unplanned cost instead of using every dollar immediately.
Does choosing a want make someone bad with money?
No. A want can be a valid choice when it is deliberate and fits the available money and priorities.
What are the three questions in the story?
Ask what responsibility the money protects, what option saving creates, and what information waiting might reveal.
Leave a Reply