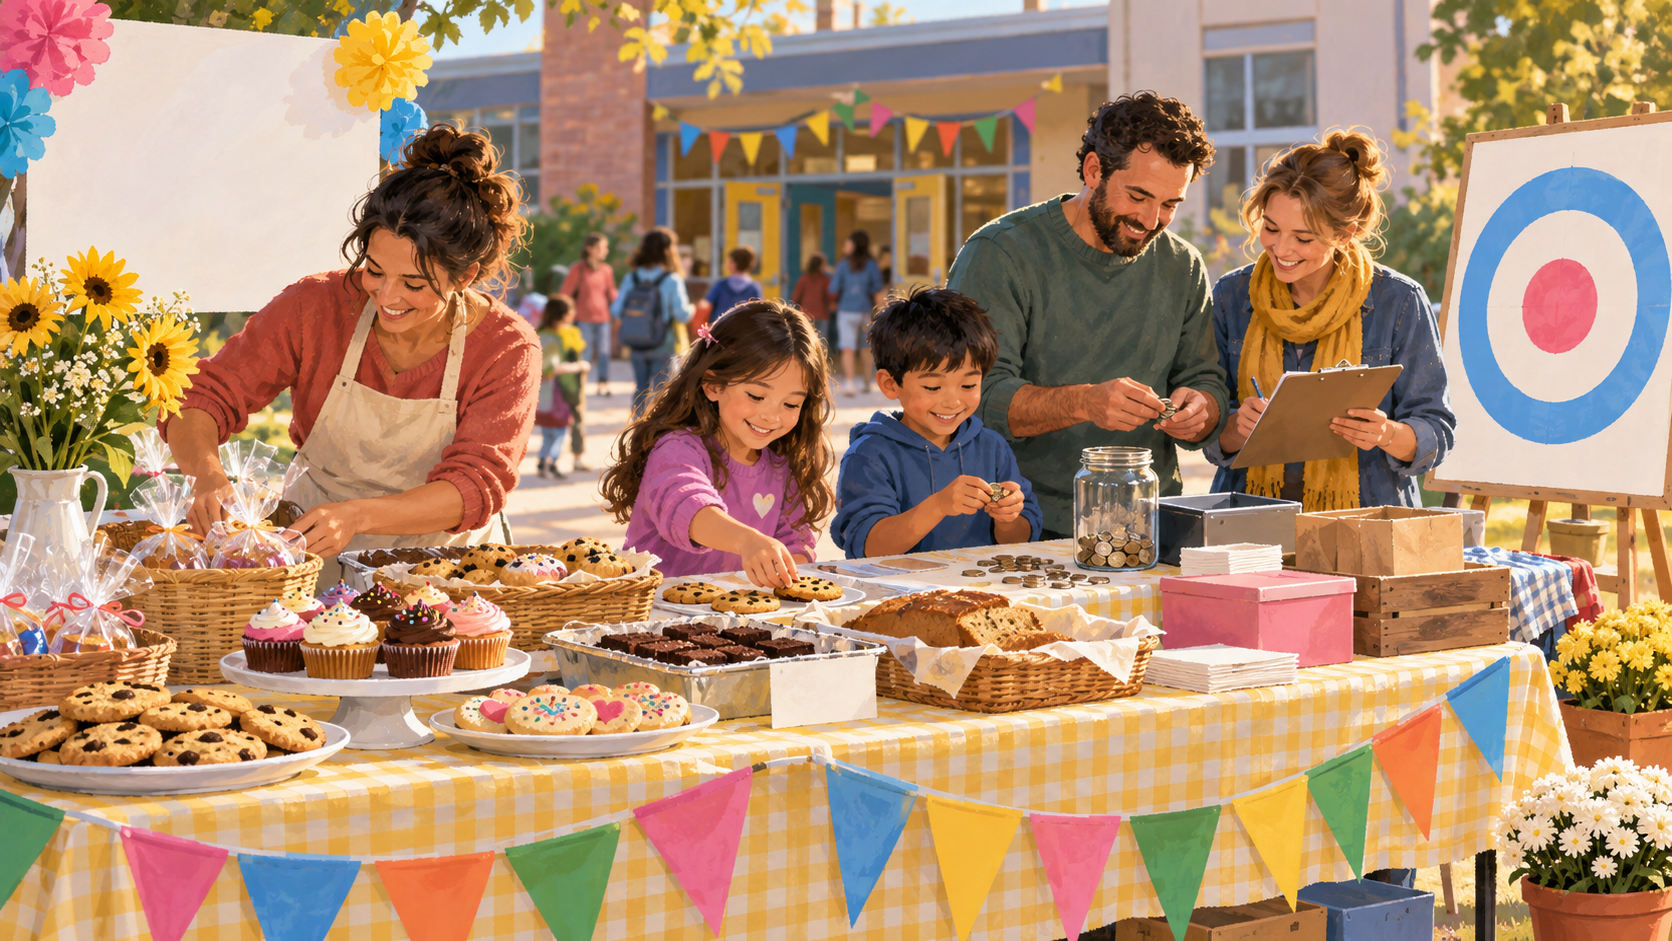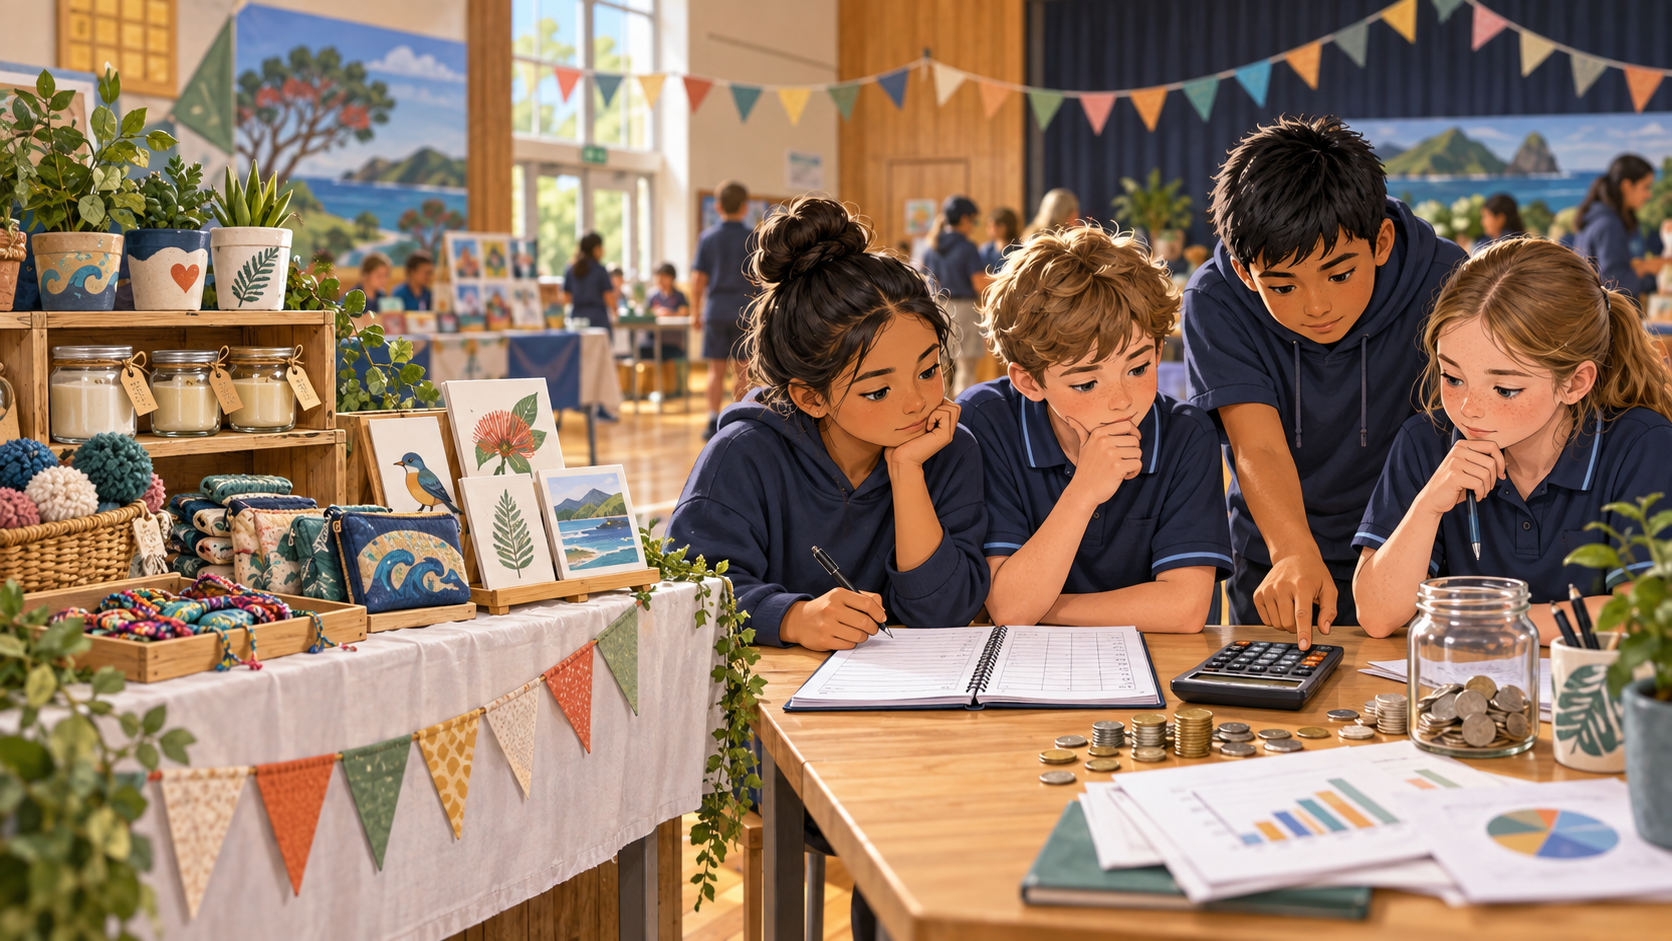
The school market looked like a triumph. By lunchtime, the student team had sold every decorated biscuit, plant pot and printed card. They counted $486 in sales and celebrated—until the treasurer opened the planning folder. The stall had sold out, but the team had not yet worked out whether it had made money.
The numbers behind the excitement
The fictional team spent $210 on ingredients and materials. They paid $48 for packaging, $35 for a stall fee and $22 for a last-minute replacement tablecloth. A family donated the table, so it did not appear as a cash cost. The team also promised to give $100 to the school library. Their cash result before the donation was $171: $486 minus $315 of recorded costs.
That result is not the same as the amount available to spend. The team still needs to check whether every sale was recorded, whether any supplier bill is outstanding and whether the promised donation is part of the plan. A full budget includes income, expenses and saving or giving goals.
The mistake was not selling out
The mistake was pricing from the ingredient cost alone. The team calculated that each packet cost $2 to make and priced it at $2.50. They forgot packaging, the stall fee and the cost of items that broke or were given away. Their price covered production, but it did not fully cover the event.
Sorted’s budget guide recommends listing income, spending and savings or goals, then comparing the totals. The class can apply that method to the market without treating the fictional figures as a real fundraising forecast.
The repair meeting
At the next meeting, the team makes three changes. They create a cost list before choosing a price. They keep a small buffer for breakage and unexpected purchases. They agree that “sales” and “money available for the goal” will be written on separate lines. The team also decides that a donated item should be recorded as support, even though no cash left the account.
None of this makes the market less fun. It makes the result easier to explain. The students can say what they sold, what it cost, what support they received and what will happen to the remaining cash.
Try the debrief
Ask students: Which cost was easiest to forget? What price would have covered the full event cost? When is a donation a cost, and when is it a goal? The best answer may depend on the plan, which is exactly why the team needs to write its assumptions down.
A busy day can be a success for learning even when the first margin is small. The team has discovered that money stories have a middle: after the sale, before the celebration ends, check the whole picture.
FAQs
Did the fictional market make a profit?
Before the planned donation, it had a fictional cash result of $171 after the listed costs, but the team still needed to confirm all obligations.
Why separate sales from money available?
Sales show money received. Available money must also account for costs, outstanding bills and agreed goals.
Why record donated items?
Recording support shows what helped the event and makes the plan easier to explain, even when no cash was paid.
What cost did the team forget at first?
They priced from production cost and overlooked packaging, the stall fee, a replacement item and other event costs.
Is selling out proof of a good price?
No. Selling out shows demand, but the price still needs to cover the full cost and the purpose of the event.
Can this story be used for a class?
Yes. Students can rebuild the ledger, test a new price and explain which assumptions changed.