Author: aoagent

  • What Really Happens When You Tap to Pay?

    What Really Happens When You Tap to Pay?

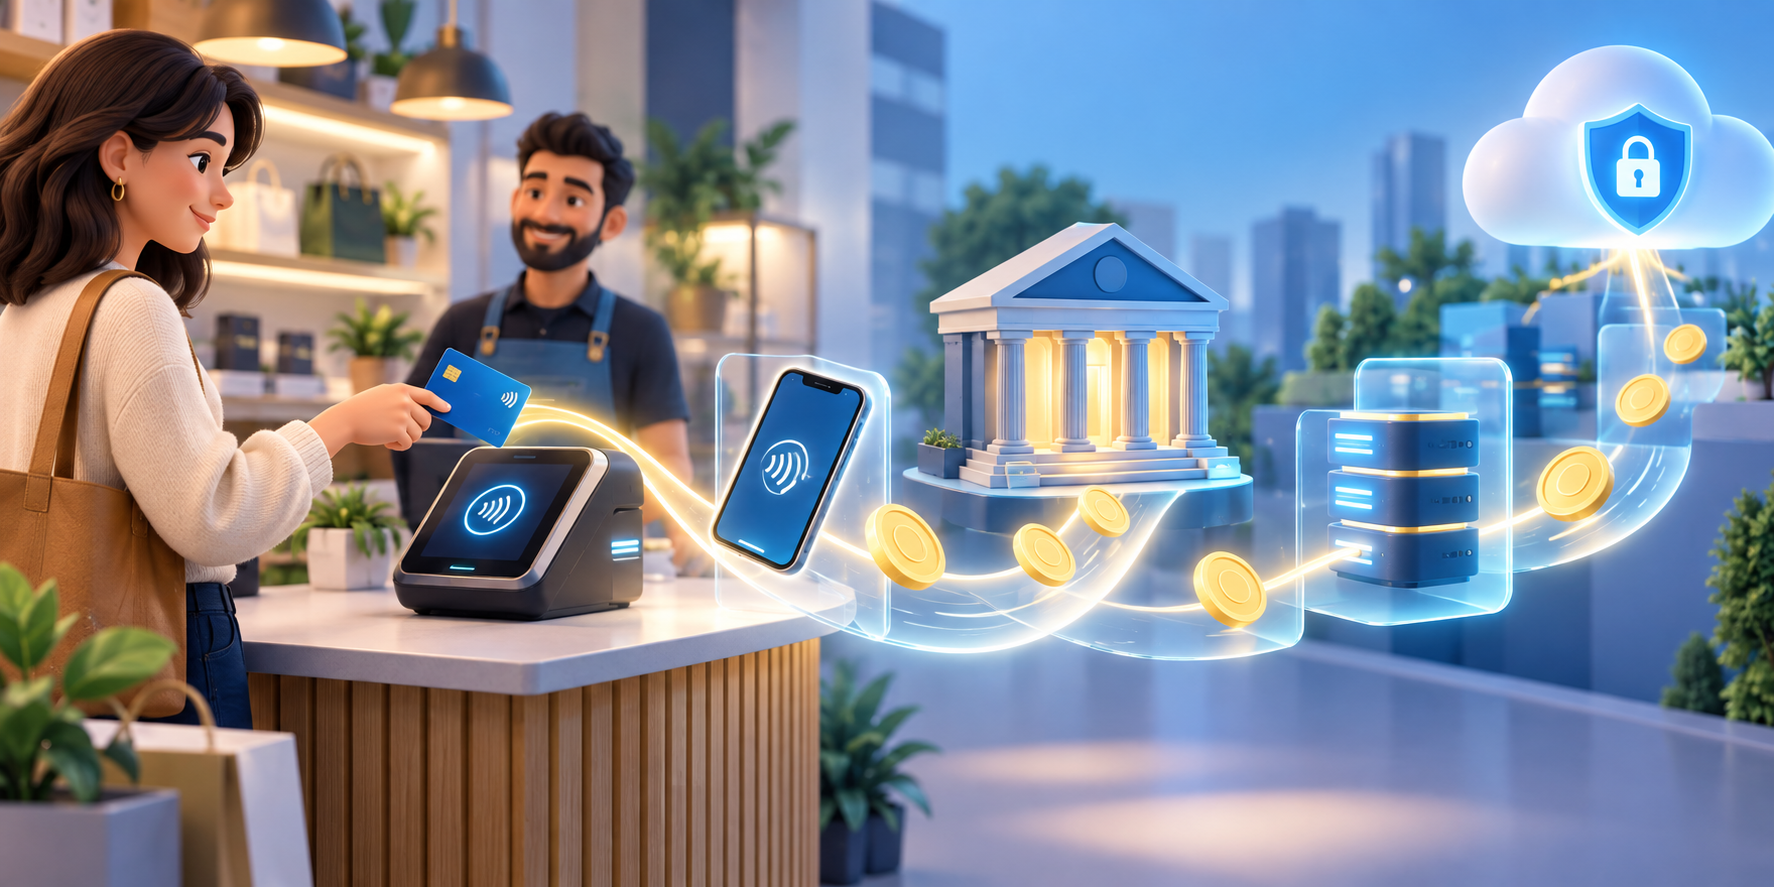
    A tap at a checkout can feel like money has jumped straight from your phone to the shop. In reality, the tap starts a chain of instructions, checks, and records. Understanding that chain helps explain why payments can be fast, why a transaction can be declined, and why the balance in your account changes after the purchase.

    The details vary between countries and payment providers, but the basic idea is consistent: a payment is a transfer of money in exchange for a good or service.

    Step one: choose a payment instrument

    You begin with a payment instrument, such as a debit card, bank payment, or mobile wallet. The instrument is the way you tell the system which account or balance should be used. It is not the same thing as the money itself; it is a way to give an instruction.

    Step two: the shop accepts the instruction

    The merchant uses a terminal or payment gateway to receive the instruction. A physical terminal reads the tap, while an online gateway collects payment details through a digital checkout. The merchant’s system sends the request into the payment network.

    Step three: authorisation checks the request

    Your bank or payment provider checks whether the instruction can be approved. It may check the account balance, security signals, limits, and whether the transaction appears valid. If the request is declined, the payment has not completed even though you may have seen a message on the terminal.

    Step four: clearing prepares the transaction

    After authorisation, clearing passes the transaction information between the relevant institutions. The payment network, your bank, and the merchant’s bank need to agree on what happened and how the transaction should be processed. This is one reason a payment can show as pending before it is final.

    Step five: settlement completes the movement

    Settlement is the stage where the funds are transferred and the transaction is completed in the accounts involved. The Reserve Bank of New Zealand describes the process as instruction, authorisation, clearing, and settlement, with the merchant ultimately receiving funds in its account: How do card payments work?

    Why a digital payment still needs a ledger

    No pile of coins moves through the air when you tap. Instead, records are updated across connected systems. Your account records a debit, the merchant’s records show a sale, and the payment system carries messages that allow the institutions to reconcile the transaction.

    That is why keeping track of digital spending matters. A tap can feel less tangible than handing over cash, but it still reduces the money available for later decisions. Notifications, account statements, and a simple spending log make the invisible movement visible again.

    What a tap can teach you about money

    Digital payment technology makes convenience possible, but convenience is not the same as affordability. Before tapping, check the price, the account you are using, and the trade-off with your current goal. After tapping, make sure the transaction appears as expected and keep your security details private.

    MoneyCQ turns this kind of invisible process into a visible decision. The ledger shows money arriving, leaving, and being reserved for different purposes. The more clearly you can see the path, the easier it is to manage the next choice.

    Sources and further reading

    For a deeper overview of New Zealand’s payment infrastructure, read the Reserve Bank’s payments landscape primer. Payment rules and timing can differ by country and provider.

    FAQs

    Does tapping move physical cash?

    No. It sends an electronic instruction that results in account records and funds being transferred.

    What is authorisation?

    Authorisation is the check by a bank or payment provider to decide whether the payment request can be approved.

    What is clearing?

    Clearing is the process of passing and checking payment information between the institutions involved.

    Why can a payment be pending?

    A pending status can mean the transaction has been authorised but has not yet completed final processing and settlement.

    Why should I watch digital spending?

    Digital payments are convenient but still reduce the money available for future spending, saving, or emergencies.

    What should I do if a tap is declined?

    Check the account, payment method, limits, or security requirements, and use the provider’s official support channel if the problem continues.
  • The Seven-Day Needs vs Wants Challenge

    The Seven-Day Needs vs Wants Challenge

    “Is this a need or a want?” is a useful question, but it can become a lecture if it never reaches real decisions. The Seven-Day Needs vs Wants Challenge turns it into a small experiment. For one week, notice the choices you make, pause before optional spending, and see what changes when you give every purchase a job.

    The aim is not to label every want as wrong. Wants make life enjoyable. The aim is to become better at choosing them deliberately instead of letting a hurry, a discount, or someone else’s excitement choose for you.

    What counts as a need?

    A need is something that supports health, safety, basic living, or an important responsibility. Food, necessary transport, a place to live, and essential school or work items are common examples. Needs still have choices inside them: one food option may cost more than another, and a need can sometimes be met in several ways.

    A want is something you would like but could postpone, replace, borrow, or live without for now. Entertainment, treats, upgrades, and impulse purchases often sit here. A want is not silly or shameful. Naming it honestly gives you control over when and how you buy it.

    The challenge rules

    For seven days, keep a simple note on your phone or a sheet of paper. Record each purchase or planned purchase, whether it was a need or a want, how you felt before buying, and whether the purchase helped with a goal. If you do not spend, record one moment when you chose not to.

    Use five labels: need now, need later, want planned, want impulse, and not sure. The “not sure” label matters. It gives you room to learn without pretending every decision is obvious.

    Day one: notice without changing

    On the first day, simply observe. Do not try to be perfect. Notice the trigger: hunger, boredom, a notification, a friend, a time limit, or a convenient checkout button. You are collecting clues about how decisions happen.

    Days two and three: add a pause

    Before buying a want, wait ten minutes. Ask three questions: What problem does this solve? What else could I do with the same money? Will I still want it tomorrow? A short pause separates a real preference from a passing feeling.

    Days four and five: connect spending to goals

    Choose one small goal, such as a game, a book, a trip, or an emergency buffer. Put the price beside the goal. When you skip or delay a want, write down the amount you kept available. You are not “missing out”; you are making the trade-off visible.

    Days six and seven: design your own rule

    Look back at the week. Which purchases felt worth it? Which were forgotten quickly? Create one personal rule, such as “I wait overnight for unplanned purchases,” “I compare two prices,” or “I save part of every payment before spending.” A good rule is small enough to repeat.

    What the challenge teaches

    The challenge shows that budgeting is not only arithmetic. It is attention, timing, and priorities. Sorted describes a budget as a plan for where incoming money should go, including regular and irregular costs; see Sorted’s budgeting guide. Your seven-day notes provide the evidence for building a plan that reflects real behaviour.

    In MoneyCQ, each choice feeds the wider story. A small purchase can affect saving, resilience, and the options available later. The challenge works the same way outside the game: one decision rarely changes everything, but repeated decisions create a pattern you can see and improve.

    Sources and further reading

    Use the Sorted money-mindset guide for more on habits, goals, and the emotional side of spending.

    FAQs

    Does calling something a want mean I should never buy it?

    No. A want can be a sensible purchase when it fits your priorities and available money.

    What if I cannot tell whether something is a need?

    Use the “not sure” label and ask whether the purchase supports health, safety, basic living, or a real responsibility.

    How long should the pause before buying last?

    The challenge suggests ten minutes for a quick experiment, while an overnight pause can help with larger or unplanned wants.

    What should I write down during the challenge?

    Record the purchase, its label, the feeling or trigger before buying, and whether it supported a goal.

    Can children do this activity?

    Yes. Adults can help children use simple labels and discuss choices without shaming them.

    What is the best result after seven days?

    The best result is a repeatable personal rule based on what you noticed, not a perfect record with no spending.

  • Gross Pay vs Take-Home Pay: Where Your Money Goes First

    Gross Pay vs Take-Home Pay: Where Your Money Goes First

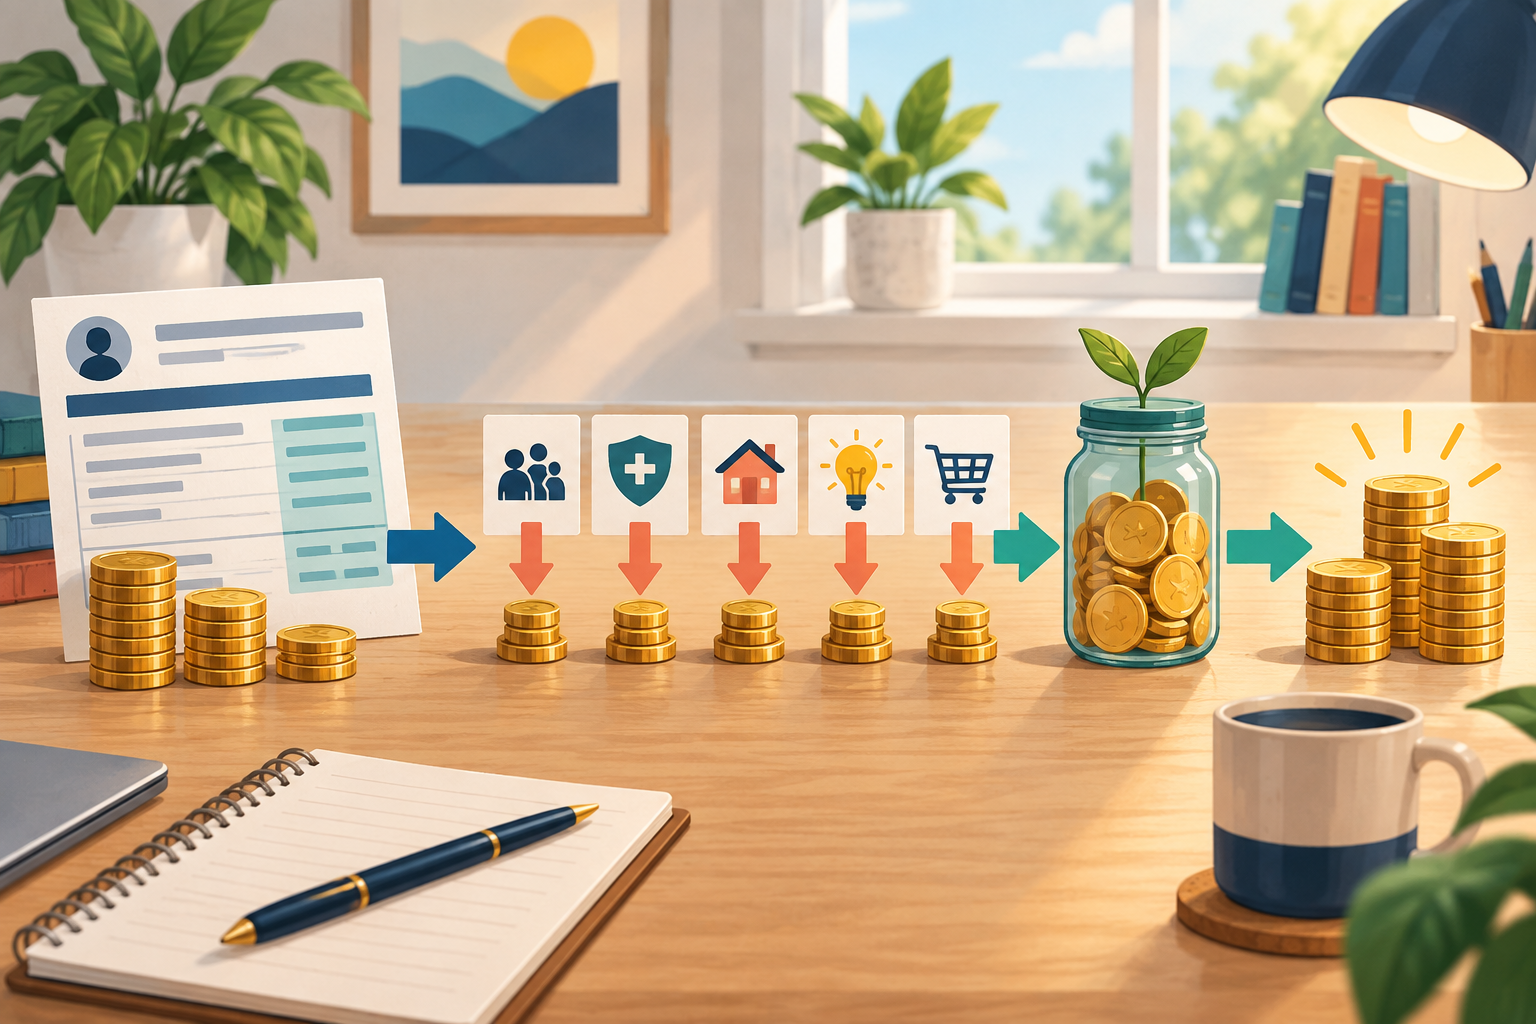
    A new job can come with a number that looks wonderfully large. Then payday arrives and the amount in your account is smaller. That is not a trick, and it does not mean someone has lost your money. It means your gross pay has passed through the deductions that apply before you receive your take-home pay.

    Understanding the journey from salary to spendable money is one of the most useful money skills you can build. It helps you plan honestly, compare jobs fairly, and make sense of the payslip in MoneyCQ or in real life.

    Gross pay is the starting number

    Gross pay is the amount agreed before deductions. It might be shown as an annual salary, an hourly rate, or a weekly amount. If a job pays $25 an hour and you work 20 hours, the gross pay for that week is $500 before anything is taken out.

    Gross pay is useful for comparing the size of different jobs, but it is not the amount you can automatically spend. A salary offer can look attractive while a different job with better hours, lower travel costs, or more reliable income leaves you with more useful money overall.

    Take-home pay is what reaches your account

    Take-home pay, sometimes called net pay, is the amount left after the deductions that apply to you. It is the number that should anchor your weekly or monthly spending plan. Rent, food, transport, saving, and fun all have to fit inside this amount.

    The exact deductions depend on where you live, your income, your tax settings, and the choices you make. In New Zealand, an employer generally deducts PAYE and the ACC earners’ levy from salary or wages. Other deductions may include KiwiSaver contributions, student-loan repayments, charitable payroll giving, or other authorised amounts. Inland Revenue explains that the tax code supplied to an employer affects how much PAYE is deducted: IRD guidance on salary and wages.

    Why the difference matters when you plan

    Imagine two people each seeing a gross weekly pay of $900. One has a long commute, a student-loan deduction, and higher insurance costs. The other works close to home and has fewer deductions. Their gross pay is identical, but their available cash is not.

    A realistic plan begins with take-home pay. First list regular commitments such as housing, utilities, transport, and debt payments. Then allow for flexible essentials such as groceries. After that, give saving and irregular costs a place. Only then should you decide how much is available for optional spending.

    Read a payslip like a money map

    When you receive a payslip, look for four landmarks: the pay period, gross earnings, deductions, and net pay. Check whether the hours or salary shown match what you expected. Notice whether deductions are fixed, percentage-based, or changing. If a number is unfamiliar, ask the employer or payroll team rather than guessing.

    A payslip is also a record of trade-offs. A retirement contribution may reduce today’s cash while building a locked or long-term balance. A student-loan repayment may feel like a loss from the week’s budget, but it is reducing a liability. Seeing every line helps you understand why your cash flow looks the way it does.

    How this appears in MoneyCQ

    In MoneyCQ, the payslip flow turns an abstract salary into a lived decision. Gross pay comes in, deductions are shown, and the amount available for the week becomes real. That makes it easier to test choices: Can you afford a higher rent? What happens if you save first? Does a second income stream actually cover the extra costs it creates?

    The lesson is simple: build your life around money you can use, not money that only appears at the top of an offer letter. Gross pay tells you the size of the starting pool. Take-home pay tells you what the next decision can actually be.

    Sources and further reading

    For a New Zealand example of progressive income tax rates and PAYE deductions, see Inland Revenue tax rates. Rules differ by country, so use the official tax authority for the region that applies to you.

    FAQs

    What is gross pay?

    Gross pay is the amount earned before tax and other deductions are taken out.

    What is take-home pay?

    Take-home pay is the amount left after the deductions that apply to your pay have been made.

    Which number should I use for a budget?

    Use take-home pay because it is the amount available to cover spending and saving.

    Why can two people with the same salary receive different amounts?

    Tax settings, retirement contributions, student-loan payments, and other deductions can differ between people.

    What should I check on a payslip?

    Check the pay period, earnings, deductions, and net amount against what you expected.

    Are pay deductions always bad?

    No. Some deductions fund taxes, insurance, retirement saving, or debt repayment, even though they reduce the cash available today.