Author: aoagent

  • The Busy Stall With an Empty Cash Tin: A Fictional Market-Day Lesson

    The Busy Stall With an Empty Cash Tin: A Fictional Market-Day Lesson

    This is a fictional teaching story. The people, stall and figures are invented.

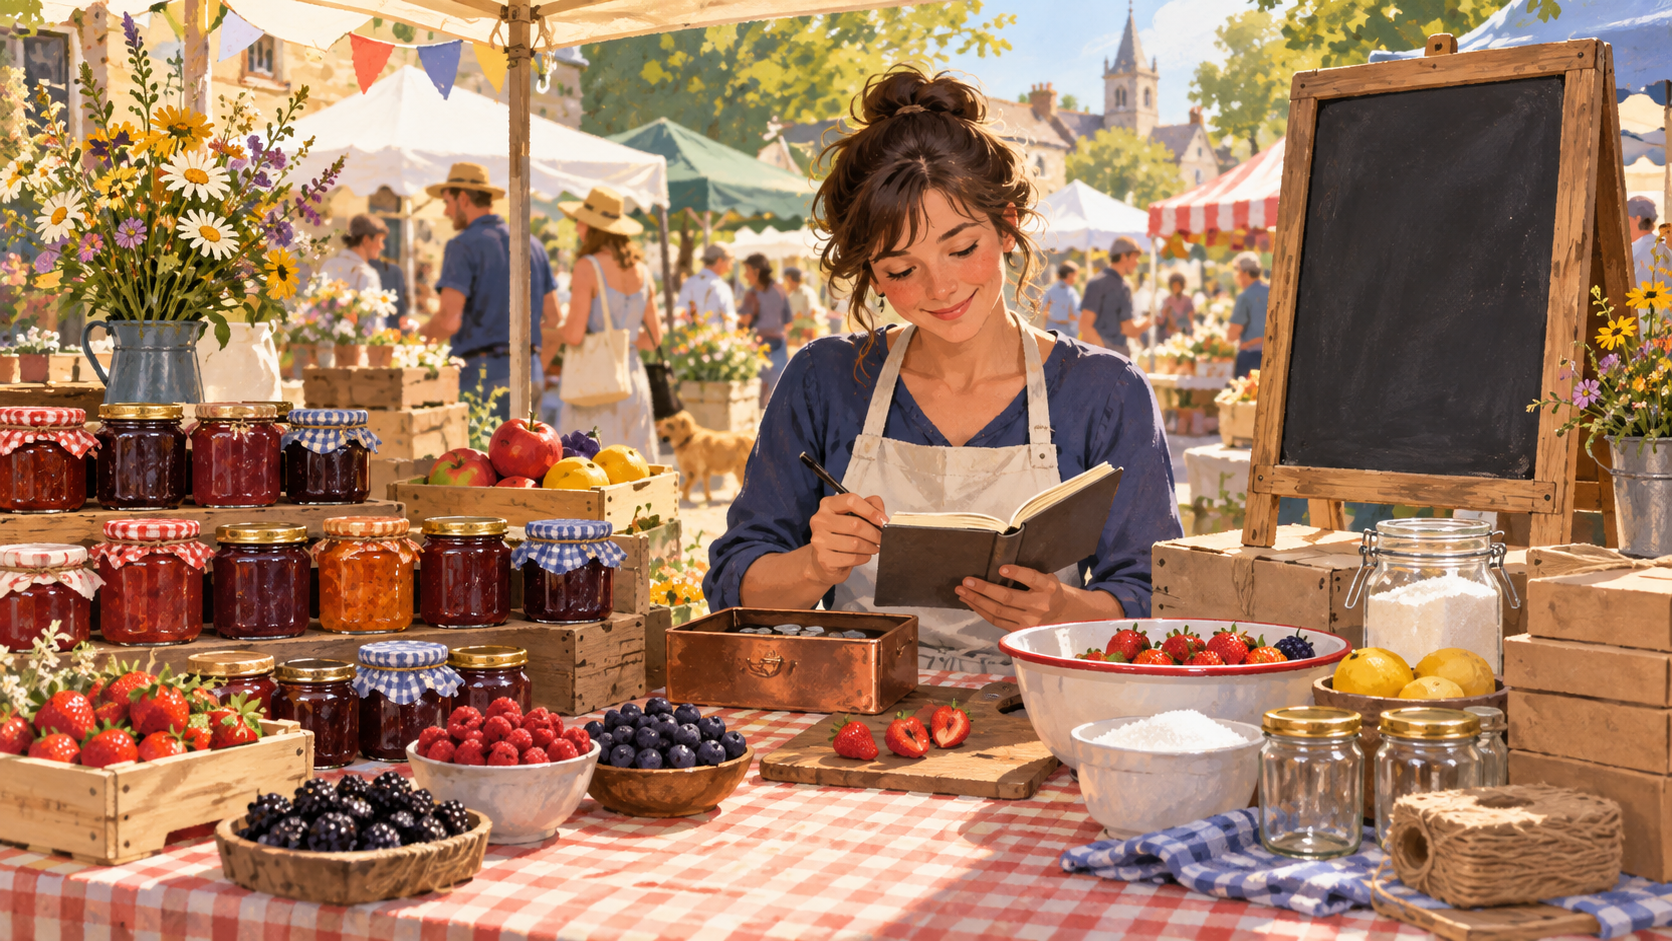
    On Saturday morning, Maia set up a small jam stall at a community market. By lunchtime, most of the jars were gone. Customers had smiled, the table looked busy, and the cash tin held $360. Maia’s first thought was, “That went brilliantly.” Then she counted what the day had cost.

    Sales are not the same as money kept

    Maia wrote down four expenses: ingredients and jars cost $148, the market-space fee was $50, card-processing fees totalled $7, and transport cost $22. Together, the expenses were $227. Subtracting $227 from $360 in sales left $133 before tax and before placing any value on Maia’s time.

    That $133 is not the same as the $360 customers paid. The $360 is revenue (the sales total). The $133 is what remained after the listed costs. Even that number is incomplete if Maia used equipment she had already bought, replaced a broken tool, or spent hours preparing fruit and labels. A busy day and a profitable day can overlap, but they are not synonyms.

    Give the numbers more context

    Suppose Maia spent eight hours preparing and selling. Dividing the remaining $133 by eight gives about $16.63 an hour, before tax and before any costs she forgot to record. This is not a wage calculation or a promise about what a small business should earn; it is a prompt to notice the value of time and the limits of an incomplete tally.

    She also asks a different question: what does each jar contribute toward the shared costs? If there are 40 jars in the sales total, the listed costs average $5.68 per jar ($227 divided by 40). If the average sale per jar was $9, that leaves about $3.32 per jar toward Maia’s time and any missing costs. Bundles, unsold stock and discounts would change the picture, so a simple average is a starting point, not a full accounting.

    A small record makes the next decision clearer

    For the next market, Maia records the quantity made, what sold, what remained, every expense and how long each step took. She can then compare two options: keep the same prices and sell more, or adjust the batch size, product mix or price. She does not need to choose immediately; better information makes the trade-offs easier to see.

    This is useful beyond stalls. A school fundraiser, side project or family bake sale also has money coming in and costs going out. Sorted’s money-tracking guide recommends recording spending rather than relying on memory, because small and irregular costs are easy to miss. A basic record cannot answer every business question, but it helps replace “we sold heaps” with numbers that can guide the next plan.

    The final lesson is not that Maia should work harder or charge more. It is that a cash tin tells only part of the story. Before calling a project a success, decide what success means: covering costs, learning, fundraising for a cause, or earning a return for time. Once that is clear, the right next step becomes easier to choose.

    FAQs

    What is revenue in this story?

    Revenue is the $360 total Maia received from sales before subtracting expenses.

    How much remained after the listed costs?

    The listed costs totalled $227, so $360 minus $227 left $133 before tax and unrecorded costs.

    Is the $133 the same as Maia’s wage?

    No. It does not include tax, missing expenses or a full valuation of her preparation and selling time.

    Why record unsold stock?

    It helps Maia understand what sold, what remains and whether the next batch should change. Unsold stock is not the same as cash earned.

    Does selling out prove a stall made a profit?

    No. Sales volume alone does not show whether revenue exceeded all the relevant costs.

    What should Maia track next time?

    Record sales, quantities, every expense, remaining stock and the time spent preparing and selling.
  • Gift Cards in 2026: Check the Terms, Balance and Fees

    Gift Cards in 2026: Check the Terms, Balance and Fees

    A gift card can feel almost like cash, but it comes with conditions. Before buying one—or putting it in a drawer—check where it works, when it expires and whether using it costs anything. A few seconds with the terms and receipt can prevent a small present from becoming an awkward surprise later.

    Know which kind of card you have

    A store gift voucher is usually a promise that a retailer will accept it for goods or services. A pre-loaded payment card may work across more places, but it can have fees for purchase, use, inactivity or replacement. The rules and costs are not automatically the same, so read the card packaging or provider’s terms rather than relying on the word “gift”.

    New Zealand’s Consumer Protection guidance says a new law took effect in March 2026: newly issued gift cards cannot have an expiry date shorter than three years from the initial sale date. If a shorter date is printed, the guidance says that date is void and is treated as three years after sale. Check the issue or purchase date, and ask the retailer if you are unsure whether a specific card is covered. This rule does not mean every pre-loaded payment card has identical terms.

    Four checks before you pay

    • Where can it be used? Check eligible shops, websites, branches and exclusions. A card accepted at one franchise may not work at another.
    • When does it expire? Record the date somewhere you will see it. If there is no expiry date, the official guidance says it can be used whenever you want; if there is a valid expiry, a retailer may not have to accept it after that date.
    • Are there fees? Gift vouchers should not have extra fees, while some pre-loaded cards can charge fees. Read the provider’s current terms before purchasing.
    • What happens to the leftover balance? Electronic-card balances can generally be used on another date. Paper-voucher change depends on the terms and the remaining value.

    Keep a record and use it thoughtfully

    Save the receipt or transaction confirmation, especially for a higher-value card or an online purchase. If the card is lost, a retailer may not have to replace a voucher; a pre-loaded card may have a replacement process or fee. Keep the card number and proof of purchase somewhere safe, but do not post a photo of the code publicly.

    Once you receive a card, add a reminder before its expiry date and check the balance after each use. If you are buying for someone else, a card accepted at more than one shop may offer more flexibility. Consumer Protection’s gift voucher and pre-loaded card guide explains expiry, fees, lost cards and what to do if a retailer closes.

    Finally, treat the card as a spending choice, not a reason to buy something you do not want. If the recipient has a clear preference, a flexible option—or asking first—may be more useful than guessing. When a card does not work, contact the seller first, explain what outcome you want, and keep the purchase evidence to hand.

    FAQs

    What is the minimum expiry for a newly issued NZ gift card in 2026?

    Consumer Protection says the March 2026 law prevents newly issued gift cards from having an expiry shorter than three years from the initial sale date.

    Does that rule automatically cover every pre-loaded card?

    No. Gift vouchers and pre-loaded payment cards can have different features and fees. Check the specific product’s terms and ask the provider if coverage is unclear.

    Can a pre-loaded card have fees?

    Some can. Check for purchase, use, inactivity or replacement fees before paying.

    What should I keep after buying a card?

    Keep the receipt or transaction record and note the card’s terms and expiry details.

    What happens to an unused electronic balance?

    Consumer Protection says an electronic-card balance can be redeemed on another date, subject to the card’s terms.

    Who should I contact if a voucher is not accepted?

    Start with the retailer or seller where it was bought, explain the issue and say what solution you are seeking.

  • The Class Trip Budget Challenge: Plan a Great Day Under $25 Each

    The Class Trip Budget Challenge: Plan a Great Day Under $25 Each

    A class trip is a lively way to practise budgeting because the numbers connect to a real plan: getting there, eating, taking part and allowing for surprises. This activity uses a fictional limit of $25 per student. It is not a statement about current New Zealand transport or admission prices; teachers should replace the sample figures with verified local quotes before making a real booking.

    The challenge

    In teams, plan a day out for 24 students. Your total must stay at or below $600, which is $25 per student. Your plan should include travel, an activity, food and a small contingency. It should also explain how students with different access, food or mobility needs can take part.

    Give each team these sample costs to start: bus contribution $8 per student, activity entry $7, packed lunch $6 and contingency $4. The total is $25 each, or $600 for 24 students. These are invented classroom figures. Teams can change them, but they must show the arithmetic and say which numbers they would need to confirm with a provider.

    Make the numbers tell a story

    Ask teams to make a one-page plan with four columns: item, cost per student, group total and how the figure was checked. Multiply each per-person amount by 24. For example, a $7 activity cost becomes $168 for the group. Add all group totals and compare the result with the $600 limit.

    Then introduce a change card: the bus quote rises by $48 for the whole class, rain moves the group indoors, or one student needs a different lunch option. Teams should decide whether to use contingency, change an activity, or revise the plan. They must explain who is affected by each choice. A budget is a way to make trade-offs visible, not just a maths worksheet.

    For a second round, invite students to design two options: the lowest-cost workable trip and the best-value trip. Best value may mean a more accessible venue, a shorter travel day or an activity that everyone can enjoy. The cheapest line on a page does not always make the best overall experience.

    Debrief without judging

    Finish by asking what the teams found easy to estimate and what they needed to verify. Which cost changed the total most? Did the contingency protect the plan? What would make the plan fairer for a family unable to contribute the same amount? Keep the focus on systems and choices, not on classmates’ household circumstances.

    Sorted’s step-by-step budgeting guide describes a budget as a plan for money coming in and going out. This activity turns that idea into a shared, low-stakes exercise. In a real trip, the organiser should confirm quotes, payment deadlines, transport, permissions and any school subsidy before asking families to pay.

    Quick check: If a team chooses a $9 bus contribution, $6 activity, $5 lunch and $3 contingency, what is the total per student? ($23.) For 24 students, what is the group total? ($552.) How much remains under the fictional $600 cap? ($48.)

    FAQs

    Are the sample prices real New Zealand prices?

    No. They are invented for the classroom exercise. Check current local quotes before planning a real trip.

    Why include a contingency?

    It gives the plan room to respond to a change or an overlooked cost without immediately exceeding the limit.

    What is the class limit in this activity?

    The fictional limit is $25 for each of 24 students, or $600 in total.

    Can students choose a plan over budget?

    They can show it as an alternative, but they should identify the gap and explain a realistic adjustment before it counts as a workable plan.

    How can the activity include different needs?

    Ask teams to consider access, travel, food and participation from the start, then verify options with the school and providers.

    Should the class ask families to cover a shortfall?

    That is a school decision, not an assumption for students to make. Discuss affordability and available support with the appropriate adults.

  • Turn a Savings Wish Into a Goal You Can Actually Follow

    Turn a Savings Wish Into a Goal You Can Actually Follow

    “We should save for that” is a nice intention, but it is hard to act on until the wish has a price, a timeframe and a next step. A useful savings goal is not a promise to be perfect. It is a small plan you can revisit when life changes.

    Start with the thing, not the weekly amount

    Choose one goal that matters to you or your whānau: replacing a worn-out appliance, paying for a course, or setting aside money for a family day out. Write down what you are aiming for and why. A goal with a real purpose is easier to keep visible than an abstract instruction to “save more.”

    Next, estimate the full cost. Include the parts that are easy to forget: delivery, equipment, transport, or a small allowance for price changes. If you do not know the exact amount, use a reasonable estimate and mark it as one. You can update it when you have a quote or more information.

    Turn the total into a rhythm

    Suppose a family wants to save $360 for a goal in 12 weeks. Dividing $360 by 12 gives a starting target of $30 a week. If the household is paid fortnightly, that might become $60 each pay cycle. The arithmetic makes the goal easier to picture; it does not mean every family can spare that amount.

    If the amount does not fit, adjust one of the three levers: choose a less expensive version, extend the timeframe, or set a smaller contribution and accept that the goal will take longer. A plan that leaves enough for essentials is more useful than an ambitious figure that quickly becomes discouraging. Sorted’s guide to setting money goals also recommends making goals clear and breaking them into manageable steps.

    Make progress visible—and flexible

    Pick a tracking method you will actually use: a separate account, a note in a budgeting app, or a paper thermometer with blank milestones. Record deposits when they happen and check the balance on a regular date. If you share the goal, agree who will update the record and where the money will sit.

    Build in a review point rather than treating the first plan as fixed. After a month, ask: Is the target still realistic? Did the price change? Did an unexpected cost take priority? Adjusting the amount or date is not failure; it is how a plan stays connected to real life. If the goal is no longer important, you can redirect the money deliberately instead of letting the plan fade without a decision.

    For a household activity, invite everyone to suggest one way to make progress that does not rely only on cutting small treats. Perhaps there is a lower-cost option, a second-hand version, or a way to share equipment. Keep the conversation practical and free of blame. The point is to practise turning a wish into a set of choices.

    This is general financial-literacy information, not personalised financial advice. A savings plan should fit your circumstances and essential commitments.

    FAQs

    What makes a savings goal useful?

    It names the goal, estimates the total cost, gives a timeframe and identifies a repeatable contribution. Those details make progress easier to review.

    What if I do not know the exact price?

    Use a clearly labelled estimate, include likely extra costs and replace the estimate when you can check a current price or quote.

    How do I calculate a weekly target?

    Divide the amount still needed by the number of weeks available. For example, $360 over 12 weeks is $30 a week.

    What if the weekly amount is too high?

    Consider a lower-cost version, a longer timeframe or a smaller contribution. Keep essentials ahead of an optional savings target.

    Should I keep goal savings separate?

    A separate account or clear tracking label can make the balance easier to see. Choose a method that is safe and convenient for you.

    Is changing the deadline a failure?

    No. Reviewing the timeline when circumstances change is a normal part of making a realistic plan.

  • Money Words at the Table: A Family Vocabulary Game

    Money Words at the Table: A Family Vocabulary Game

    Money conversations become easier when everyone can use the same words. A learner may know that a price is “expensive” but not yet distinguish an expense from a fee, or a quote from an estimate. This small game turns six words into a shared vocabulary without asking anyone to reveal private finances.

    Use blank cards, simple drawings or fictional examples. The goal is not to memorise a dictionary. It is to help learners explain what a number means and what question they might ask next.

    The six cards

    Income is money coming in, such as pay, an allowance or another source. Expense is money going out for something you buy or use. Goal is something you are planning toward, such as an event or a purchase.

    Fee is a charge connected with a service or action. Quote is an offer for a specified price and scope. Estimate is a best guess of what something may cost. Consumer Protection explains the important difference between quotes and estimates, making those two cards useful in a real-life scenario.

    Round one: match the picture

    Place six picture cards on the table: money arriving, a basket leaving a shop, a target, a service charge, a fixed service offer and a “roughly this much” note. Learners match each picture to a word and explain their choice in one sentence. There can be more than one sensible picture if the explanation is clear.

    Round two: build a sentence

    Draw two cards and make a fictional sentence. “The income helps with an expense.” “The goal needs a plan.” “The estimate is not the same as a quote.” Ask what extra question would make the sentence more useful. The adult can model uncertainty by saying, “I would check the terms before deciding.”

    Round three: solve a tiny scenario

    Give the learner a fictional situation: a group wants to book an activity, a service provider sends an estimate, or a family is planning for a goal. The learner chooses three cards and explains the order they would use them. For example, identify the income available, list the expense and ask whether the price is a quote or an estimate.

    Keep the language kind and practical

    Do not use the game to test whether someone is “good with money”. Let learners ask for a word to be explained again. Sorted describes budgeting as a plan for spending and saving; the game gives families and classrooms a low-pressure way to talk about that plan before real decisions appear.

    Finish by asking which word was most useful and which word needs another example. A shared vocabulary does not remove every money challenge, but it gives people a clearer starting point for asking questions.

    Sources and further reading

    Sorted: How to build a budget step by step; Consumer Protection: Quotes and estimates; Consumer Protection: Contracts and sales agreements.

    FAQs

    Who is this vocabulary game for?

    It can work for families, whānau, classrooms or small groups using fictional examples and age-appropriate language.

    Why include both quote and estimate?

    The words describe different kinds of price information, so learners can practise asking which one they have received.

    Does income only mean wages?

    No. In the activity, income can be any fictional money coming in, such as pay or an allowance.

    Is every charge a fee?

    Not necessarily. The game uses fee as a charge connected with a service or action, but the actual terms should be checked in each situation.

    Do learners need to share family finances?

    No. Use made-up numbers and scenarios so personal income, expenses and goals can stay private.

    What should we do if a word is unclear?

    Pause, explain it in plain language and create another fictional example rather than guessing.

  • The Fifteen-Minute Money Meeting: A Habit That Keeps Plans Visible

    The Fifteen-Minute Money Meeting: A Habit That Keeps Plans Visible

    A money plan is easier to use when it is visible before a decision arrives. A fifteen-minute meeting can give a household, whānau or learning group a calm place to look at what is coming up, what matters most and what needs checking next.

    This is not a meeting for judging anyone’s spending. Sorted describes a budget as a plan for spending and saving, and recommends gathering information about income, regular costs, irregular costs and goals. The meeting turns that idea into a small recurring habit.

    Minutes 1–3: choose a private, predictable time

    Pick a time that is close enough to the week ahead to be useful. Decide who needs to be involved and what information each person is authorised to see. A learner can use fictional numbers or a personal allowance plan instead of sharing household balances.

    Minutes 4–7: name the next commitments

    Write the costs that are due before the next meeting: transport, food, school activity, bill, appointment or agreed payment. Mark anything that is an estimate. The purpose is not to predict perfectly; it is to make the next decisions less surprising.

    Minutes 8–10: check the plan against available money

    Place the amount available for the period beside the near-term commitments. If the plan has room, decide where a small amount could go toward a goal or flexible spending. If it does not fit, choose one next step such as confirming a due date, changing an optional plan or asking a provider about the available options.

    Minutes 11–13: name one priority

    Choose one goal or value for the next week: keeping transport covered, saving for an event, leaving room for a shared activity, or avoiding a late fee. Sorted’s guidance on money goals encourages goals that are specific, realistic and written down. One visible priority is easier to revisit than a long list of intentions.

    Minutes 14–15: close with one action

    Write down who will do what and when. It might be checking a price, moving a planned amount, cancelling an unused booking or bringing a receipt to the next meeting. End by choosing the next meeting time. If the meeting becomes tense, pause and return later; a repeatable habit matters more than completing every question.

    Over time, the meeting can become a record of learning. A household may notice which costs are regular, which are irregular and which priorities change. That is resilience in practice: not having a perfect plan, but having a small routine for returning to the plan.

    Sources and further reading

    Sorted: How to build a budget step by step; Sorted: Why money goals are important and how to set them.

    FAQs

    Does a money meeting need to last exactly fifteen minutes?

    No. Fifteen minutes is a helpful starting point. The aim is a short routine that people can repeat.

    Who should attend?

    Include the people who share the decision or need the information, while protecting anyone’s private financial details.

    What if a cost is only an estimate?

    Label it as an estimate and update it when better information becomes available. Do not treat an estimate as a confirmed amount.

    What if the plan does not fit?

    Choose one practical next step, such as confirming a date, changing an optional choice or asking about available options.

    Should every meeting include a savings goal?

    Not necessarily. The priority might be an upcoming essential cost or simply understanding what is due next.

    Can learners practise this without real household information?

    Yes. Use fictional income, costs and goals so learners can practise planning without sharing private balances.

  • The Estimate That Wasn’t a Quote: A Fictional Repair Story

    The Estimate That Wasn’t a Quote: A Fictional Repair Story

    This is a fictional teaching story, not a real testimonial.

    Mila’s washing machine begins making a strange sound. She asks a repair business how much it might cost. The technician looks at the machine and says, “It should be around $180, depending on the part.” Mila writes the number in her notebook, but she does not yet have a fixed quote.

    The first number is not the whole agreement

    Mila asks what the inspection includes, whether parts and labour are covered, and whether the business will contact her before doing extra work. The business sends a written estimate with the likely repair, an inspection charge and a note that the final cost may change if a different part is needed.

    Consumer Protection explains that an estimate is a best guess, while a quote is an offer for a specified price. The words matter because they describe a different level of price commitment.

    Mila compares the options

    She gets a second estimate. It is lower, but the provider cannot come for two weeks. The first provider can attend tomorrow and gives a clearer list of what is included. Mila does not choose by price alone. She compares the likely cost, timing, scope and what happens if the repair needs extra work.

    The repair changes shape

    At the appointment, the technician finds that the original part is worn and another component may also need replacing. The technician explains the extra work and gives Mila a new price before continuing. Mila decides the extra cost is too high today, so she asks the technician to stop after the inspection and records the options.

    She is not embarrassed that the answer changed. The important step was that the extra work was discussed before it happened. Consumer Protection’s repair guidance recommends giving a repairer a price limit or asking what work is needed and how much it will cost before agreeing.

    What Mila learns

    A number remembered from a conversation is not the same as a written agreement. Next time, Mila will ask whether she is receiving an estimate or a quote, what is included, and how variations will be approved. She will also keep the written information with the invoice.

    The story does not say that an estimate is bad or that a quote is always possible. It shows how a clear question can protect a decision from surprise. A household can choose a different path depending on urgency, available cash and the importance of the repair.

    Sources and further reading

    Consumer Protection: Quotes and estimates; Consumer Protection: Repair damage after normal use.

    FAQs

    Are Mila and the repair business real?

    No. They are fictional characters created to explore how a repair price can change when the scope changes.

    What is an estimate?

    An estimate is a provider’s best guess of what the work may cost, based on the information available at the time.

    What is a quote?

    A quote is an offer for a specified price and scope. The terms should be checked before accepting it.

    Why did Mila ask for approval before extra work?

    She wanted to know the new cost and agree to the changed scope before more work was carried out.

    Should a repair decision use price alone?

    No. Timing, scope, materials, reliability and the household’s priorities can all matter.

    What should a customer keep?

    Keep the estimate or quote, messages about changes, approval of extra work, invoice and payment record.

  • The Payment-Link Pause: Five Checks Before You Pay Online

    The Payment-Link Pause: Five Checks Before You Pay Online

    A message can make a payment feel urgent: a parcel needs a fee, an account needs verification, or a special offer expires in minutes. The safest money habit is to slow the moment down. A link can be convenient, but convenience is not proof that the message is genuine.

    Netsafe describes online scams as deceptive schemes intended to steal money or personal information and lists unexpected contact as a warning sign. The Payment-Link Pause is a practice routine, not a guarantee that a message is safe.

    1. Did you expect this message?

    Start with the contact, not the link. Were you expecting an invoice, delivery update or account message? An unexpected message deserves a separate check, even if it uses a familiar logo or name. Do not reply with personal details just to make the message feel more real.

    2. Can you verify the sender another way?

    Open the organisation’s known website or app by typing the address yourself or using a saved bookmark. Use an official phone number or support route, not the contact details supplied in a surprising message. If the organisation cannot confirm the request, do not continue through the link.

    3. Does the web address and request make sense?

    Look at the address, spelling and page purpose before entering anything. Be cautious if a link goes to an unfamiliar domain, asks for information that does not fit the situation, or tries to install software. A secure-looking padlock is not proof that the business or message is trustworthy.

    4. Is the amount and payment route clear?

    Check the total, currency, payee and reason for the charge. Consumer Protection advises online shoppers to check the full cost, including delivery, fees and currency. If the amount is different from your order or invoice, pause and verify it. Never share a one-time code or password to “release” a payment.

    5. Can you keep a record?

    Before paying, know how you will receive a receipt and how to contact the seller. Save the confirmation and the order or invoice details. If you have already sent money and suspect a scam, stop contact and contact your bank or payment provider promptly. Netsafe and Consumer Protection can explain reporting and support routes.

    Practise the pause

    In a classroom or family activity, show two fictional messages: one expected and one surprising. Learners do not click either one. They identify the sender, choose an independent verification route, list the details they would check and decide what record they would keep. The goal is not to spot every scam by appearance; it is to build a repeatable pause before money or information moves.

    Sources and further reading

    Netsafe: Understanding scams; Netsafe: Report scams; Consumer Protection: Know your rights when shopping online.

    FAQs

    Is every payment link a scam?

    No. A real organisation may send a link, but an unexpected link still deserves independent verification before you use it.

    What is an independent verification route?

    It is a known website, app, phone number or support channel that you find separately from the surprising message.

    Why should I check the amount and currency?

    A message or checkout can show a different total or currency from what you expected, changing the amount you may pay.

    Should I share a one-time code with a caller or message sender?

    No. Keep passwords and one-time codes private and verify the request through an official route.

    What if I already paid and now feel unsure?

    Stop contact with the suspected scammer and contact your bank or payment provider promptly for guidance.

    What is the main skill in the Payment-Link Pause?

    It is delaying the payment long enough to verify the sender, address, amount, route and record independently.

  • The Three-Quote Challenge: Compare a Service Without Chasing the Cheapest Number

    The Three-Quote Challenge: Compare a Service Without Chasing the Cheapest Number

    The cheapest number is tempting, especially when three businesses appear to offer the same job. But a service can cost more because it includes better materials, a clearer timeframe or more work. The Three-Quote Challenge lets a family or class practise comparing the whole offer without spending real money.

    Use a fictional job such as painting a room, repairing a bicycle or setting up a small garden. Consumer Protection explains that an estimate is a best guess, while a quote is an offer for a specified price. That difference is the first clue in the activity.

    Set up three fictional offers

    Create three cards. Each card should show the work included, materials, timeframe, price type, and one question the customer still needs to ask. Keep the cards comparable: the same room, repair or service request should be described to each provider.

    For example, Offer A might be a low estimate with a quick start but no materials list. Offer B might be a written quote with a slower start and named materials. Offer C might cost more but include a longer warranty or a detailed completion date. None is automatically the right answer.

    Check the scope before the dollars

    Ask what will actually be done. Does the price cover preparation, materials, delivery, clean-up and tax? If one offer leaves out a step, it is not a fair price comparison yet. Consumer Protection recommends asking for written details and giving providers as much information as possible so offers can be compared more accurately.

    Label quote or estimate

    Put a large “quote” or “estimate” label on each card. An estimate is not a fixed price. A quote is generally a confirmed price for the agreed scope, and extra work or a changed scope should be agreed before the price changes. In the activity, learners should circle the offer with the clearest price commitment and write one follow-up question for the others.

    Compare more than price

    Give each offer a simple score from one to three for scope clarity, timing, evidence of quality and price clarity. Do not add the scores into a pretend “best business” result unless the group explains its weighting. A low price may matter most to one household; a reliable date may matter most to another.

    Finish with a decision note

    Each learner completes the sentence: “I would ask ___ before choosing because ___.” A strong answer might request a written quote, ask what materials are included, or check when the work can begin. If a provider proposes extra work later, the fictional customer pauses and agrees the variation before it happens.

    The activity teaches that comparing offers is a reasoning task. Price is part of the decision, but a number without a clear scope can create a bigger surprise later.

    Sources and further reading

    Consumer Protection: Quotes and estimates; Consumer Protection: Repair damage after normal use.

    FAQs

    What is the difference between a quote and an estimate?

    An estimate is a best guess of cost. A quote is an offer for a specified price and scope, subject to the terms of the agreement.

    Why should the service scope be compared first?

    Two prices cannot be compared fairly if the offers include different work, materials or timeframes.

    Should the cheapest offer always win?

    No. Consider scope, timing, quality clues, price clarity and the priorities of the person making the decision.

    What should I ask if a quote is vague?

    Ask what work, materials, timing and other costs are included, and request the answer in writing.

    Can a service price change after a quote?

    It may change if the customer agrees to extra work or the scope changes. Ask before agreeing to any variation.

    Can we do this challenge without contacting real businesses?

    Yes. Fictional cards or anonymised examples let learners practise comparison without sharing personal projects or making requests.