Category: Uncategorized

  • The Family Money Meeting: Four Rules for Decisions Without Arguments

    The Family Money Meeting: Four Rules for Decisions Without Arguments

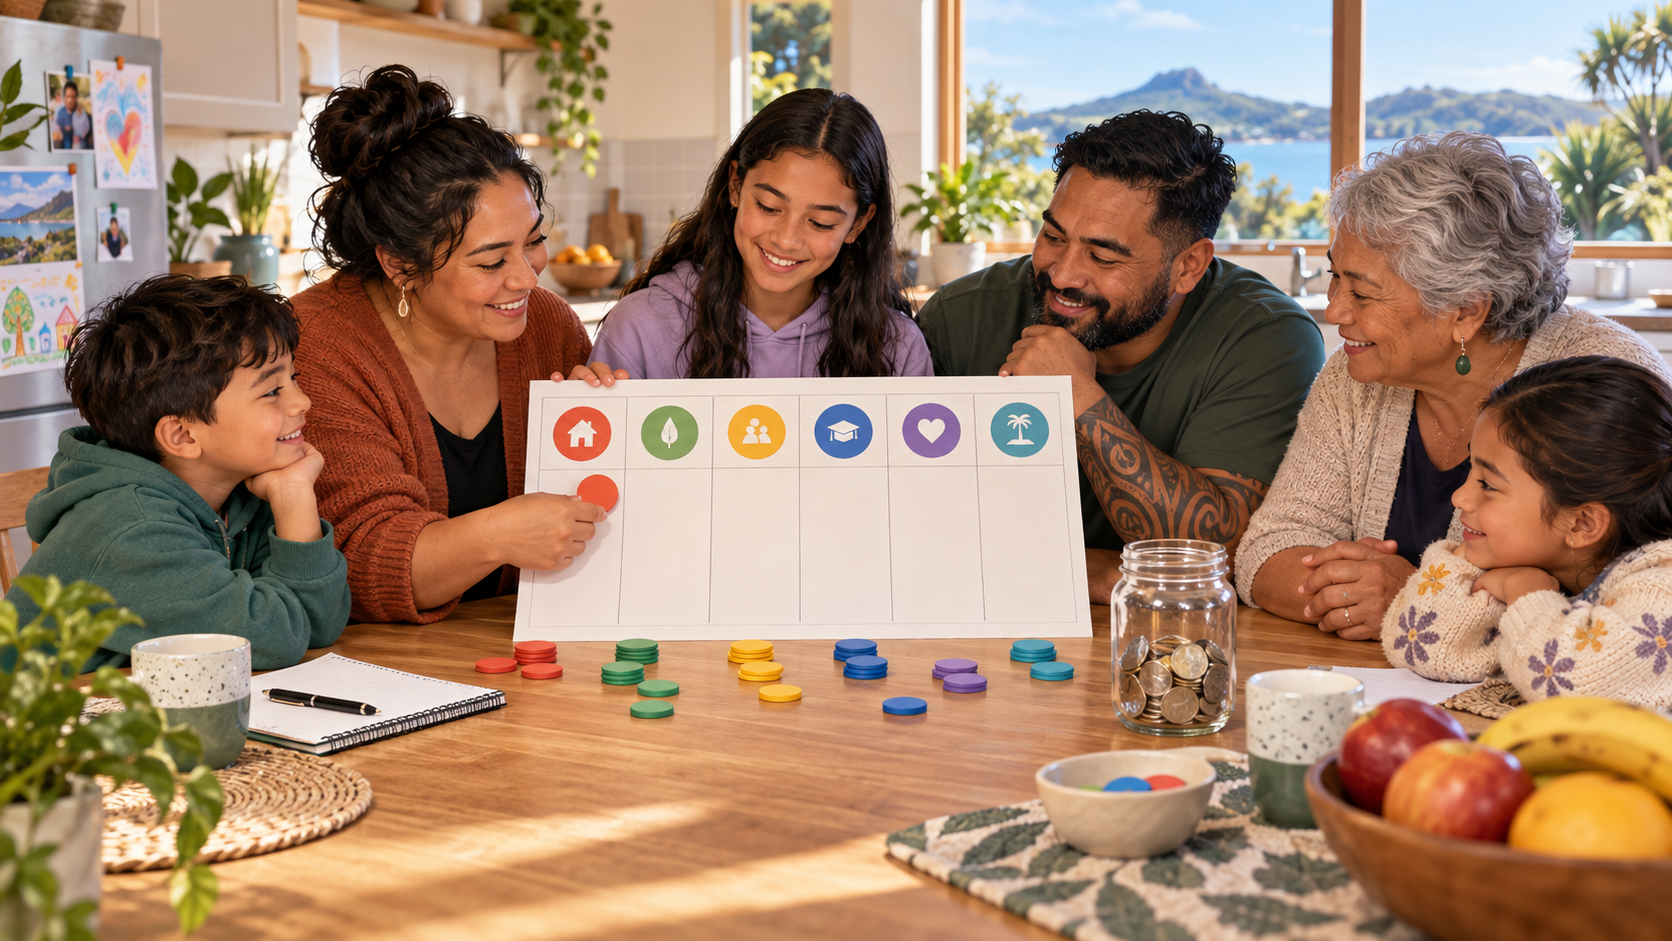
    Money conversations often go wrong before anyone has looked at a number. One person wants certainty, another wants flexibility and a young person may hear the discussion as a judgement about what the family can afford. A short money meeting can make decisions calmer when the group agrees how to talk before deciding what to do.

    Rule one: discuss the decision, not someone’s worth

    Replace “You always spend too much” with “We need to choose how to use this amount.” A money decision is information about priorities and circumstances, not a measure of character. This matters in families and classrooms because people can have different needs without anyone being the villain.

    Rule two: separate private facts from shared facts

    A group may need to know the price of a school trip, a shared bill or a family goal. It does not automatically need every person’s income, account balance or debt. Sorted’s budgeting guidance focuses on gathering the information needed to make a plan; use the minimum information that makes this decision possible.

    For children or students, use fictional amounts or broad choices such as low, medium and high. Privacy is not avoiding financial learning. It is part of learning how to handle money respectfully.

    Rule three: name the trade-off

    Every shared choice has a cost somewhere. If the family chooses a weekend trip, it may have less available for a new device or a savings goal. If the class spends its tokens on equipment, it may have fewer for a celebration. Write the options down and ask what each makes possible and what it delays.

    Sorted’s budget guide describes a budget as a comparison between income, spending and saving. That simple structure keeps the meeting grounded: what comes in, what must go out and what the group wants to protect.

    Rule four: record the next review date

    A decision made today may need revisiting after a bill arrives, a term changes or the household’s income shifts. End with one sentence: “We will check this on…” The review date is not a threat that the original choice failed. It is a way to learn from what actually happened.

    A 15-minute meeting format

    1. State the shared decision in one sentence.
    2. List the known amount and the deadline.
    3. Invite each person to name one priority or concern.
    4. Compare two or three options and their trade-offs.
    5. Choose a next step, write it down and set a review date.

    MoneyCQ’s family and classroom settings are useful places to practise this style of reasoning because the scenario can be simulated. The goal is not to produce one perfect answer. It is to make the thinking visible, listen to other priorities and leave with a plan people understand.

    FAQs

    Who should attend a family money meeting?

    Include the people affected by the shared decision, while keeping private financial details with the people who need them.

    Should children see every family number?

    No. Children can learn with age-appropriate, fictional or limited information without seeing private balances.

    What if people disagree?

    Write down the competing priorities and trade-offs, then decide what information or compromise is needed for the next step.

    How long should the meeting last?

    A focused 15-minute meeting is enough for one decision. Longer conversations can be split into smaller sessions.

    Why set a review date?

    It gives the group a chance to compare the plan with what actually happened and adjust without blame.

    Can this work in a classroom?

    Yes. Use fictional budgets, class goals and tokens so students practise decisions without revealing household finances.
  • When a Purchase Is Faulty: Build a Clear NZ Consumer Complaint

    When a Purchase Is Faulty: Build a Clear NZ Consumer Complaint

    When something you bought stops working, a clear record can make the next conversation easier. You do not need an angry message or a long story. Start with what you bought, when you bought it, what went wrong, what you have already tried and what outcome you are asking for.

    Check whether the Consumer Guarantees Act may apply

    Consumer Protection says the Consumer Guarantees Act (CGA) applies to products and services bought from businesses trading in New Zealand for personal or household use, including online purchases. Products should be of acceptable quality, fit for purpose and match their description. The CGA generally does not apply to private sales, a change of mind or damage caused by misuse or alteration.

    Read the official Consumer Guarantees Act guide and its Consumer Rights Finder for the situation. This article is general information, not a legal opinion. The right remedy depends on the product, the problem and how serious the failure is.

    Make an evidence pack

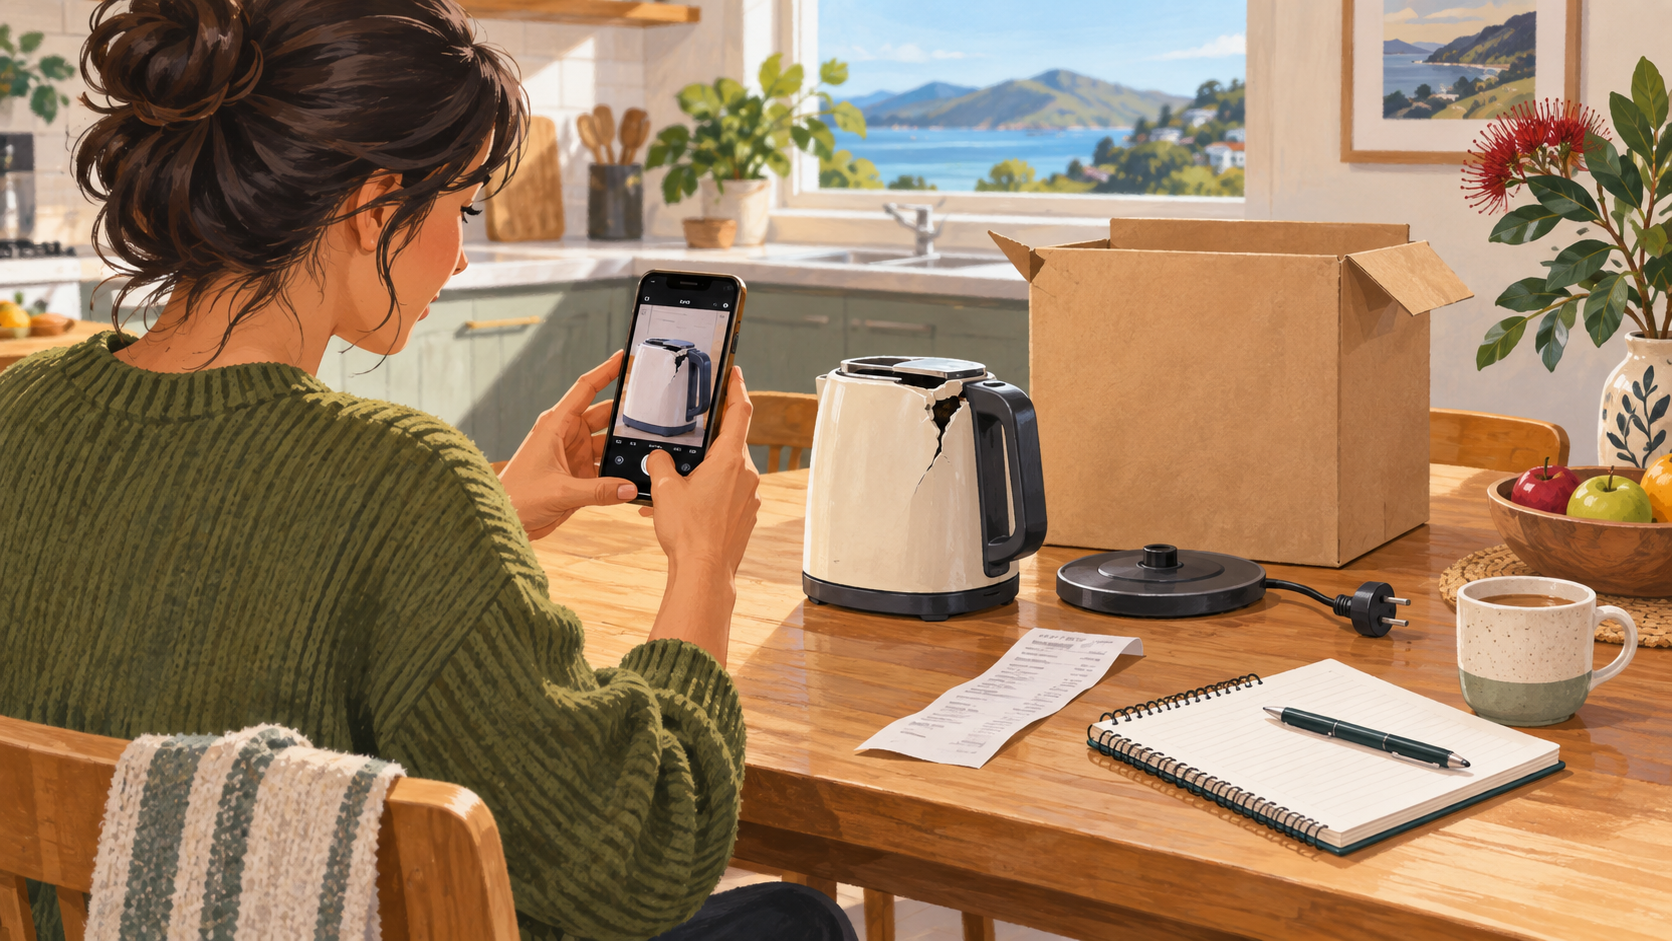
    1. Save the receipt, order confirmation or other proof of purchase.
    2. Take clear photos of damage, the product and its packaging before sending anything back.
    3. Write down the date the problem appeared and what the product was being used for.
    4. Keep the listing, product description, warranty information and any messages with the seller.
    5. Note the remedy you are requesting: repair, replacement, refund or another appropriate outcome.

    Consumer Protection suggests photographing damaged packaging and says it can make a remedy discussion easier. Keep the original evidence safe and send copies unless the seller needs the item for inspection. Do not throw the product away before the issue is resolved unless it is unsafe and you have followed appropriate safety advice.

    Contact the seller in a way you can track

    Start with the business that sold you the product. Be factual: include the order number, purchase date, fault, evidence and the response you want. Give a reasonable opportunity to respond. If the problem is minor and can be fixed, the retailer may choose a repair, replacement or refund. If the problem is substantial or cannot be remedied within a reasonable time, different remedies may be available.

    A manufacturer’s warranty is additional to CGA rights, according to Consumer Protection. An expired warranty does not automatically mean the conversation is over; a product may still need to last a reasonable time. Keep the warranty terms, but do not assume they replace the consumer guarantees.

    Escalate calmly if needed

    If the seller refuses to engage, keep your evidence and ask what complaint process is available. Consumer Protection points people to further resolution options, including the Disputes Tribunal for suitable matters. If a product is unsafe, stop using it and report the safety concern through the appropriate official route.

    A good complaint is not about using the strongest word. It is about making the facts, evidence and requested outcome easy to understand. That gives the seller a fair chance to respond and gives you a clearer record if the issue continues.

    FAQs

    Does the CGA cover online purchases?

    It can cover products bought online from a business trading in New Zealand for personal or household use.

    What should I photograph?

    Photograph the fault, the product and any damaged packaging, especially before returning or sending it for inspection.

    Who should I contact first?

    Start with the business that sold you the product and explain the problem and remedy you are seeking.

    Does an expired warranty end my rights?

    Not automatically. Consumer Protection says warranty rights are additional to CGA protections, and a product may still need to last a reasonable time.

    What if the seller says the fault is minor?

    If a fault is minor and can be fixed, the retailer may choose to repair, replace or refund. The correct response depends on the facts.

    What if the product is unsafe?

    Stop using it, keep evidence and seek appropriate safety and consumer guidance rather than continuing to test it.

  • Money Worries in New Zealand: Where to Start and How to Ask for Help

    Money Worries in New Zealand: Where to Start and How to Ask for Help

    Money worries can make even a small next step feel hard. You do not need a perfect budget or a complete explanation before asking for help. A useful first move is to identify what feels most urgent, gather only the information you have, and speak with a service that can help you work out options.

    Make a short, practical list

    On one page, note the next few payments that concern you: who needs to be paid, the amount if you know it, the due date and whether you have already contacted them. Add a short list of income expected and essential costs. If a number is uncertain, mark it as an estimate. You do not have to solve everything at once; the list simply gives you a place to start.

    If a provider or lender needs to hear from you, use its official contact details and explain what you can pay or what information you are still checking. Ask what options are available and whether the provider can confirm any arrangement in writing. Keep notes of dates, names and what was agreed. A conversation does not guarantee that a bill will be changed, but it can help you understand the next step sooner.

    Ask for support before the worry grows

    In Aotearoa, MoneyTalks is a starting point for day-to-day money questions, including budgeting and debt management. Its current information says it can connect people with a local financial mentor for free, confidential and non-judgemental support. You can contact MoneyTalks by calling 0800 345 123, texting 4029, emailing help@moneytalks.co.nz or using live chat on its website. Check the MoneyTalks contact page for current ways to reach the service.

    A financial mentor can help you organise information, consider options and connect with other support where appropriate. That is different from receiving a recommendation to buy a particular investment or financial product. If someone is pressuring you to pay an upfront fee to “unlock” a grant or debt solution, pause and verify the organisation independently before sharing money or sensitive information.

    If you are helping a friend or whānau member

    Offer practical support without taking over. You might sit together while they call, help write down questions or give them space to speak privately with a mentor. Do not ask them to share passwords, one-time codes or more account information than the service needs. If there is immediate danger or a safety concern, use an appropriate emergency or specialist support service; this money guide cannot replace that help.

    Sorted’s budgeting guide reminds readers that a budget is simply a plan for what comes in and goes out, and that people can start with the information they have. A support conversation can begin with a single question: “What is the next payment I need to understand?” From there, you can take one step at a time. Seeking help is a practical action, not an admission of failure.

    FAQs

    Do I need a complete budget before contacting MoneyTalks?

    No. A short list of urgent payments, due dates and known income can be a useful place to start; estimates can be labelled as estimates.

    What does MoneyTalks help with?

    MoneyTalks says it helps with day-to-day questions such as budgeting and debt management and can connect people with financial mentors.

    Does MoneyTalks charge for a financial mentor?

    MoneyTalks says the mentoring support it connects people with is free, confidential and non-judgemental.

    How can I contact MoneyTalks?

    Its current page lists phone 0800 345 123, text 4029, email help@moneytalks.co.nz and website live chat. Check its page for updates.

    Should I share my banking password with someone helping me?

    No. Keep passwords and one-time sign-in codes private, even when asking for help with a money problem.

    Does asking a biller for help guarantee a change?

    No. Contacting a provider helps you ask about options, but any arrangement depends on the provider and your circumstances.

  • Money Privacy at Home: Five Safer Habits for Banking and Payment Apps

    Money Privacy at Home: Five Safer Habits for Banking and Payment Apps

    Money apps make everyday tasks convenient, but they also hold details you may not want exposed: account access, contact information, purchase history and sometimes identity documents. Good privacy habits do not have to be complicated. A few small checks can reduce avoidable risk while keeping the tools you use practical.

    1. Give important accounts unique passwords

    Reusing one password across email, banking and shopping accounts means a password exposed in one place may put other accounts at risk. The Office of the Privacy Commissioner recommends long, unique passwords and says a password manager can help you manage them. If an account offers multi-factor authentication (MFA or 2FA), turn it on: it adds another sign-in check beyond the password.

    2. Pause before sharing personal details

    If an app, caller or website requests information, ask why it is needed, how it will be used and who will see it. A request may be reasonable in one context and unnecessary in another. Check the organisation’s privacy information, and do not feel pressured to provide details you do not understand. If someone calls claiming to represent a bank or agency, you can end the call and contact the organisation using a number from its public website.

    3. Check links and sign-in prompts

    A message that looks urgent can make it tempting to tap first and think later. If an unexpected email or text asks you to log in, open the official app or type the organisation’s known address yourself instead of following the message link. Never share a one-time sign-in code with someone who contacts you. If a prompt arrives when you were not trying to sign in, treat it as a reason to check the account through a trusted route.

    4. Review device and app settings

    Check which apps can access your contacts, location, camera or notifications, and switch off permissions that are not needed for the service to work. Keep your phone and apps updated, use a device lock, and sign out of shared devices. Avoid entering sensitive financial information over public Wi-Fi; if you need to take action, use a trusted connection or contact your provider for a safer option.

    5. Keep evidence, not exposed card details

    Save purchase confirmations and records in a place you can find, but avoid sharing screenshots that reveal full card numbers, account balances, addresses or one-time codes. When asking for help, cover details that are not necessary to solve the issue. If a card or bank detail may have been exposed, contact your bank promptly through its official app or publicly listed phone number and follow its instructions.

    The Privacy Commissioner’s guide to protecting personal information covers unique passwords, MFA, privacy settings and questioning requests for information. These steps cannot guarantee that an account will never be compromised, but they make it easier to spot unusual requests and respond through a trusted channel.

    Try one small change today: update a reused password, enable MFA on an account that offers it, or review one app’s permissions. A calm, repeatable habit is more useful than trying to fix every setting at once.

    FAQs

    Should I use the same password for several money accounts?

    No. The Privacy Commissioner recommends unique passwords so one exposed password is less likely to unlock other accounts.

    What does multi-factor authentication do?

    It adds another way to confirm a sign-in, beyond the password, when the service offers it.

    What should I do with an unexpected banking link?

    Do not use the message link. Open the official app or contact the organisation through a trusted, publicly listed route.

    Is it okay to share a sign-in code with a caller?

    No. Keep one-time sign-in codes private, and contact the organisation directly if a request seems suspicious.

    Should every app have access to my location and contacts?

    No. Review permissions and keep only those needed for the service’s features you use.

    What if my card or bank details may have been exposed?

    Contact your bank promptly using its official app or publicly listed contact details and follow its instructions.

  • Money Words at the Table: A Family Vocabulary Game

    Money Words at the Table: A Family Vocabulary Game

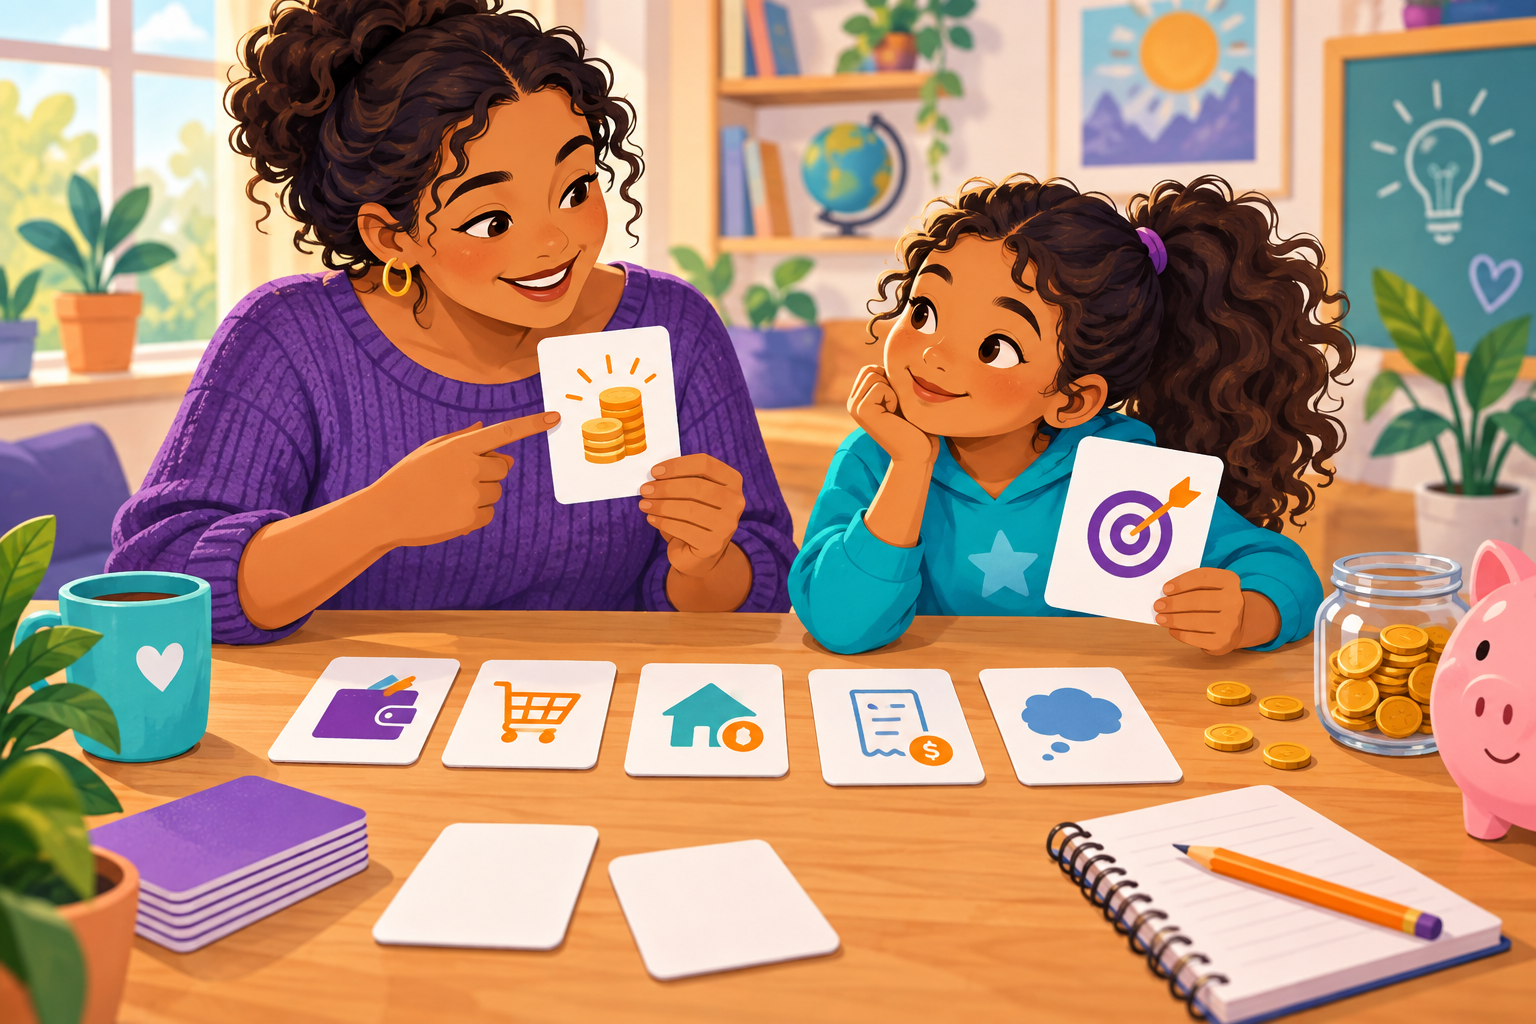
    Money conversations become easier when everyone can use the same words. A learner may know that a price is “expensive” but not yet distinguish an expense from a fee, or a quote from an estimate. This small game turns six words into a shared vocabulary without asking anyone to reveal private finances.

    Use blank cards, simple drawings or fictional examples. The goal is not to memorise a dictionary. It is to help learners explain what a number means and what question they might ask next.

    The six cards

    Income is money coming in, such as pay, an allowance or another source. Expense is money going out for something you buy or use. Goal is something you are planning toward, such as an event or a purchase.

    Fee is a charge connected with a service or action. Quote is an offer for a specified price and scope. Estimate is a best guess of what something may cost. Consumer Protection explains the important difference between quotes and estimates, making those two cards useful in a real-life scenario.

    Round one: match the picture

    Place six picture cards on the table: money arriving, a basket leaving a shop, a target, a service charge, a fixed service offer and a “roughly this much” note. Learners match each picture to a word and explain their choice in one sentence. There can be more than one sensible picture if the explanation is clear.

    Round two: build a sentence

    Draw two cards and make a fictional sentence. “The income helps with an expense.” “The goal needs a plan.” “The estimate is not the same as a quote.” Ask what extra question would make the sentence more useful. The adult can model uncertainty by saying, “I would check the terms before deciding.”

    Round three: solve a tiny scenario

    Give the learner a fictional situation: a group wants to book an activity, a service provider sends an estimate, or a family is planning for a goal. The learner chooses three cards and explains the order they would use them. For example, identify the income available, list the expense and ask whether the price is a quote or an estimate.

    Keep the language kind and practical

    Do not use the game to test whether someone is “good with money”. Let learners ask for a word to be explained again. Sorted describes budgeting as a plan for spending and saving; the game gives families and classrooms a low-pressure way to talk about that plan before real decisions appear.

    Finish by asking which word was most useful and which word needs another example. A shared vocabulary does not remove every money challenge, but it gives people a clearer starting point for asking questions.

    Sources and further reading

    Sorted: How to build a budget step by step; Consumer Protection: Quotes and estimates; Consumer Protection: Contracts and sales agreements.

    FAQs

    Who is this vocabulary game for?

    It can work for families, whānau, classrooms or small groups using fictional examples and age-appropriate language.

    Why include both quote and estimate?

    The words describe different kinds of price information, so learners can practise asking which one they have received.

    Does income only mean wages?

    No. In the activity, income can be any fictional money coming in, such as pay or an allowance.

    Is every charge a fee?

    Not necessarily. The game uses fee as a charge connected with a service or action, but the actual terms should be checked in each situation.

    Do learners need to share family finances?

    No. Use made-up numbers and scenarios so personal income, expenses and goals can stay private.

    What should we do if a word is unclear?

    Pause, explain it in plain language and create another fictional example rather than guessing.

  • A MoneyCQ Debrief: Five Questions for Parents and Teachers

    A MoneyCQ Debrief: Five Questions for Parents and Teachers

    A MoneyCQ session can end with a number on a screen, but a score is not the whole conversation. The most useful follow-up may be a learner explaining what they noticed, what information they used, and what they might try next time. Parents, whānau and teachers can help by asking before advising.

    These questions work with a fictional scenario or a shared game experience. No one needs to disclose their family income, account balance or private financial decisions to take part.

    1. What surprised you?

    This invites the learner to name an event, cost or choice they did not expect. Listen for the detail that caught their attention rather than correcting the answer immediately.

    2. What information helped you decide?

    The learner might mention a price, a due date, a goal or the effect of an earlier choice. Ask how they found that information and what else they would want to know in a similar scenario.

    3. Which trade-off felt hardest?

    Money choices can involve competing priorities. Instead of asking whether the choice was right or wrong, invite the learner to describe what they gained and what they gave up. More than one answer can make sense depending on the goal and circumstances.

    4. What would you like to test next time?

    Let the learner choose one small experiment, such as checking a recurring cost, saving toward a goal before optional spending, or comparing two options. Keep the experiment within the simulation; do not turn it into a real-world financial instruction unless an adult has checked that it is suitable.

    5. What is different in real life?

    A simulation makes choices visible, but real people have different responsibilities, opportunities and support. Ask which parts of the scenario feel simplified. This helps the learner practise judgement rather than copying a game outcome as a universal rule.

    Keep the chat short, use plain words, stay on the topic the learner chose, and avoid treating a score as a judgement of character. Sorted’s guide to good money conversations recommends listening, avoiding judgement and keeping the discussion focused. A calm debrief gives families and classrooms room to notice learning without requiring personal disclosures.

    MoneyCQ is a place to practise decisions. A thoughtful question can help a learner carry the reasoning—not a single answer—into the next scenario.

    FAQs

    Should a debrief focus on the learner’s score?

    A score can be one starting point, but the conversation can focus on the choices, information and trade-offs behind it rather than treating it as a grade.

    Do learners need to share real family finances?

    No. Use the simulation or a fictional example. Personal balances, income and household decisions can remain private.

    What if the learner made a choice I disagree with?

    Ask what they were trying to achieve and what information they used before offering another perspective.

    How long should the conversation take?

    There is no required length. A few focused questions can be enough for one session; let the learner’s interest guide the discussion.

    Can a teacher use these questions with a class?

    Yes. Keep examples fictional or from the simulation, and make it clear that students do not need to disclose personal or family finances.

    Is a MoneyCQ outcome advice for real life?

    No. Treat it as practice in reasoning through a simulated situation, not as a universal financial recommendation.

  • How to Read Your First MoneyCQ Week Beyond the Score

    How to Read Your First MoneyCQ Week Beyond the Score

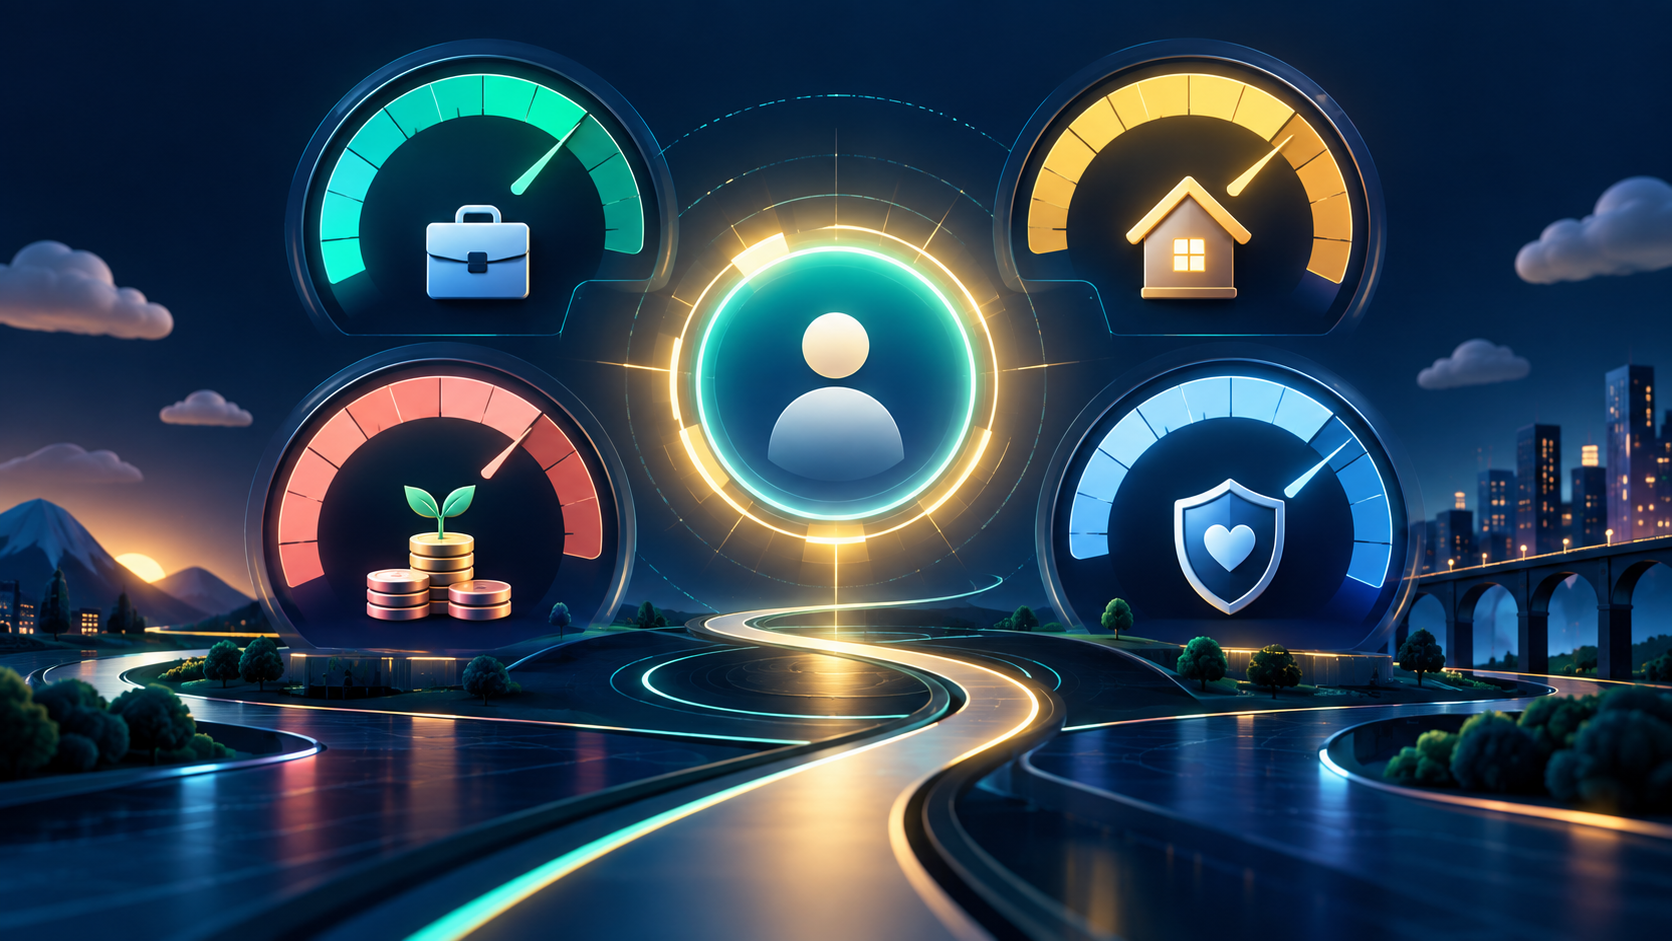
    Your first MoneyCQ week can produce a number that feels like a verdict. It is better understood as a dashboard. The score is a signal about the choices you made, the pressures you faced, and the systems you built. To improve, look underneath the number and ask which decisions moved it.

    Start with the four visible questions

    MoneyCQ describes financial health through four practical lenses: earn, manage, grow, and survive. They are connected but not identical. You may earn more without managing well. You may save consistently without taking enough care of resilience. The score becomes useful when you can see the balance between them.

    After your first week, write one sentence for each lens. What brought money in? What did you spend or reserve? Did anything grow over time? What protected you from a setback? This turns a score into a story you can act on.

    Earn: look at reliability, not only the headline pay

    A job with higher pay can also bring longer hours, more fatigue, less security, or higher costs. Review how your income fitted the life around it. Did the work cover basic costs? Did a side hustle require equipment or time that reduced the benefit? The best income decision is not always the largest number; it is the one that supports sustainable cash flow.

    Manage: follow the ledger

    The ledger is where the score meets reality. Look for repeated small outflows, large fixed commitments, and decisions that reduced flexibility. Ask whether you planned from net pay or spent as if gross income were available. If the week felt tight, identify the pressure point rather than blaming the whole plan.

    A strong management habit is to decide what each incoming dollar is for before the week becomes busy. Housing, bills, food, saving, debt, and optional spending all compete for the same pool. A visible plan makes the trade-offs easier to explain.

    Grow: separate progress from excitement

    Growth is not just finding a dramatic opportunity. It can mean adding to savings, reducing costly debt, building skills, or choosing a measured investment. Before taking risk, understand what could be lost, how quickly you might need the money, and whether the decision is diversified or concentrated.

    MoneyCQ uses a simulated world so you can test choices without placing real money at risk. Treat the result as practice, not a promise about what will happen outside the game.

    Survive: notice the protections you almost needed

    Resilience is often invisible when nothing goes wrong. Insurance, a cash buffer, a stable home, manageable debt, and enough recovery time may feel boring during a calm week. Their value becomes clear when a shock arrives.

    Review what would have happened if one event had been worse. Would you have had cash? Could you reduce a cost? Which asset or decision was exposed? This is not an invitation to fear every possibility. It is a way to build a plan before pressure makes the choice for you.

    Choose one experiment for week two

    Do not try to change everything at once. Choose one experiment: save before spending, compare a recurring cost, wait before an impulse purchase, review insurance, or find a way to improve income without adding unsustainable fatigue. At the end of the next week, compare the decision and the result.

    The score matters because it makes progress visible. It does not replace judgement. Your real advantage is learning to connect the number to the habit underneath it, then repeating the habits that make your future choices stronger.

    Sources and further reading

    MoneyCQ’s own Cash Quotient explanation describes the score as a blend of earning, managing, growing, and surviving with money. Use the in-game weekly summary as the primary record of your simulated decisions.

    FAQs

    Is a high CQ score a guarantee of success?

    No. It is a game measure of simulated financial decisions, not a guarantee about real-life outcomes.

    What should I inspect first after a week?

    Inspect the weekly summary and ledger, then connect the result to earn, manage, grow, and survive.

    Can earning more lower my score?

    It can if higher income is outweighed by new costs, debt, fatigue, or weaker management decisions in the simulation.

    What is a good week-two experiment?

    Choose one manageable change, such as saving first, pausing before impulse spending, or reviewing a recurring cost.

    Should I copy a successful in-game investment?

    No. Use the simulation to practise thinking about risk and trade-offs rather than treating it as a real-world recommendation.

    Why look at resilience during a calm week?

    Protections such as buffers and manageable commitments are easiest to build before a financial shock arrives.

  • Introducing MoneyCQ

    MoneyCQ — Money Cash Quotient — is a measurable score of your financial skill, habits, and progress. Think of it like IQ for intelligence and EQ for emotional intelligence: CQ is financial intelligence.

    Your CQ reflects how well you earn, manage, grow, and survive with money. It rises and falls with your choices — jobs, side hustles, daily expenses, unexpected events, investments, gambling, loans, lifestyle upgrades, relationships, and the random chaos of life.

    We’re building a financial life-sim where CQ is the heartbeat of the game. Start your first life now at app.moneycq.com – the game is live.