Category: Resilience & Habits

  • The $50 Buffer Experiment: Make Small Emergencies Less Dramatic

    The $50 Buffer Experiment: Make Small Emergencies Less Dramatic

    Resilience is not a dramatic promise to handle every crisis perfectly. It can start with a small amount of money kept for a problem that arrives at an inconvenient time. A $50 buffer will not solve every emergency, but it can give a person one more option when a bike light breaks, a prescription needs collecting or a school cost arrives early.

    Choose a small, visible target

    Call the first target “the buffer,” not “money I am never allowed to touch.” Its job is to handle a genuine unexpected cost. Keep it separate from everyday spending if that makes the boundary clearer, and record the purpose in a place you can see.

    Sorted’s emergency-savings guide suggests starting with $1,000 and building towards several months of expenses, while also recognising that even smaller amounts help when someone is beginning. The $50 experiment is a first step, not a claim that one amount suits every household.

    Run the four-week experiment

    1. Choose an amount that is realistic and a weekly transfer or cash amount.
    2. Give the buffer a clear label and keep a simple record of additions.
    3. If a genuine unexpected cost happens, write down what it was and how much you used.
    4. After four weeks, review whether the amount, location or target still makes sense.

    The experiment is not a test of willpower. If income changes or essential costs are already too high, the right action may be to ask for help, renegotiate a bill or use a suitable support service. Do not skip food, housing, healthcare or required payments to force a savings target.

    Make the lesson visible

    Imagine two fictional players. Ari has $50 in a labelled buffer when a $38 bike repair appears. Bo has no buffer and must decide whether to delay the repair, borrow or ask someone for help. Neither player is “good” or “bad”; the buffer simply changes the number of choices available.

    For a classroom activity, give groups event cards and a fictional weekly budget. Some groups have a buffer and some do not. Ask what changes, what does not and which decisions carry a future cost. Keep every example fictional so students do not have to disclose private finances.

    Refill without shame

    If you use the buffer, the next task is not to feel guilty. It is to record the reason, check whether the cost was truly unexpected and begin refilling when possible. A buffer is a tool that gets used; its value comes from helping you recover and plan the next step.

    FAQs

    Is $50 enough for every emergency?

    No. It is a small practice target that may help with some minor costs. The right amount depends on the household and the risk.

    What counts as an emergency?

    It is a necessary or important cost that was not reasonably planned for, such as a small urgent repair. Definitions differ, so write your own examples.

    Should I stop essential spending to save?

    No. Do not sacrifice food, housing, healthcare or required payments to force a target.

    Where should the buffer be kept?

    Use a safe, accessible place that is separate enough from everyday spending for you to notice when it is being used.

    What if I need to use the buffer?

    Record the reason and amount, then refill it gradually when your circumstances allow.

    Can students do this activity?

    Yes, with fictional budgets and event cards. No student needs to reveal a real household balance.
  • The One-Page Money Admin Folder: A Small Habit That Prevents Big Scrambles

    The One-Page Money Admin Folder: A Small Habit That Prevents Big Scrambles

    When a bill is questioned, an appliance breaks or a subscription needs cancelling, the hardest part can be finding the right detail. A small money-admin folder gives you a place for due dates, reference numbers, receipts and contact notes. It is not a second job and it should not contain passwords or unnecessary sensitive information.

    Keep the folder deliberately small

    Start with one page or a short digital note containing recurring payment names, due dates and the account or provider involved. Add a second section for annual costs such as insurance renewals, vehicle registration, school costs or medical appointments. Sorted’s budget guide recommends gathering day-to-day spending, annual costs, after-tax income and savings information; your folder can be the reminder system that helps you gather those details.

    Keep a third section for “in progress”: a disputed charge, a return, a repair request or a payment arrangement. Write the date, organisation, what you asked for and when you expect a response. This stops you from having the same conversation repeatedly and creates a calm trail if you need to follow up.

    Choose what not to store

    Do not store banking passwords, one-time codes, full card details or identity documents in an ordinary notebook or shared folder. If you keep receipts, turn them face down or use a secure location. Use official password-management and device-lock features for sign-in information. Share only the details a provider needs to answer your question.

    A household folder can include a list of trusted provider contact routes, but check each one from the organisation’s official website before calling. Scammers can imitate bills and customer-service messages. A saved official route is more useful than a phone number copied from an unexpected text.

    Use a ten-minute weekly reset

    1. Check the next two weeks of due dates.
    2. Move completed items out of the “in progress” section.
    3. Add any new annual renewal or appointment.
    4. File or securely destroy receipts you no longer need.
    5. Choose one question to resolve, rather than trying to fix everything.

    If you miss a week, simply restart. The folder is meant to reduce mental load, not create a new reason to feel behind. After a month, ask whether it is helping you see upcoming costs and follow up on open questions. Remove sections you never use.

    Good money administration is quiet work: fewer surprises, better evidence and clearer conversations. It cannot prevent every financial problem, but it can make the next practical step easier to find.

    FAQs

    What belongs in a money-admin folder?

    Useful items include due dates, annual costs, provider contacts, receipts and notes about open questions or disputes.

    Should passwords go in the folder?

    No. Keep passwords, one-time codes, full card details and identity documents out of an ordinary folder.

    How often should I check it?

    A short weekly check of the next two weeks is a practical starting rhythm.

    What is an “in progress” note?

    It records an open issue, the date you contacted someone, what you asked for and when you plan to follow up.

    Should I keep every receipt forever?

    No. Keep records that help with warranties, returns, disputes, tax or other real needs, and securely dispose of records you no longer need.

    What if I miss a weekly check?

    Restart the next time you remember. The habit is useful because it is repeatable, not because every week is perfect.

  • A Calm Money Rhythm for Variable Pay: Plan Around What Is Reliable

    A Calm Money Rhythm for Variable Pay: Plan Around What Is Reliable

    When pay changes from one week to the next, a budget built around the best pay period can create stress in a quieter one. A steadier habit is to plan from what is reasonably reliable, then decide deliberately what a higher-pay period should do. This is a flexible way to organise information, not a guarantee that every bill will fit.

    Begin with after-tax money and real dates

    Look at recent take-home pay rather than gross earnings. Write down when each payment arrived and when the next one is expected. If work is casual or seasonal, mark the amount that is confirmed separately from shifts or income that are possible but not yet certain. Do not count hoped-for hours as money already available.

    Sorted’s budget guide recommends listing income after tax, expenses and the period they cover. You can use weekly, fortnightly, monthly or annual figures—whichever period makes sense for your household. The practical habit here is to compare more than one pay period, so a single unusually high week does not set expectations for every week.

    Choose a conservative planning baseline

    Review the last few pay periods and identify a lower amount that has occurred often enough to be useful for planning. This is a household estimate, not a rule from Sorted. Use it to map essential costs and due dates first, then list other commitments and choices. If even the baseline does not cover the current bills, the plan has shown a gap early; it has not failed.

    Make a simple calendar of when money arrives and when payments are due. If a bill date falls before income is expected, contact the provider before the due date to ask what options, if any, are available. Do not assume every provider will change a date or waive a fee. If several bills cannot be covered, seek support rather than taking on a new loan without understanding the cost.

    Give stronger weeks a job

    When income is higher than the baseline, first check upcoming essentials and any overdue commitments. If those are covered, decide how much can go toward the next lower-pay period, a planned cost, a savings goal or another priority. The choice is yours; the helpful part is deciding before the extra disappears into unplanned spending.

    At the end of each month, compare the plan with what actually arrived and what was paid. Update the baseline if work patterns have changed. Avoid judging yourself for a low week: variable income is a feature of the work arrangement, not a personal failure. Sorted notes a budget can be adjusted as real information improves. For a simple start, track only income dates, bills due and the amount left after each one, then add detail if it helps.

    This article offers general financial-literacy ideas, not personal debt or investment advice. If income is persistently below essential costs, consider speaking with a free financial mentor or another trusted support service.

    FAQs

    Should I budget using my highest recent pay?

    A high pay period may not repeat. A conservative estimate based on reliable take-home income can make planning more cautious.

    Should I count shifts that are not confirmed?

    Keep possible shifts separate from confirmed income so you do not treat uncertain money as already available.

    What does after-tax income mean?

    It is the money that reaches you after deductions, which is the amount available to plan with in a household budget.

    What should I do if a bill is due before payday?

    Check the dates and contact the provider early to ask whether any options are available. Do not assume a change is guaranteed.

    What can I do with a higher-pay week?

    After checking near-term essentials and commitments, you can choose a priority such as preparing for a lower-pay period or a planned cost.

    How often should I review this plan?

    A short monthly review can help you update dates and estimates when your work pattern or expenses change.

  • The 90-Day Irregular-Costs Notebook: Find the Expenses a Monthly Budget Misses

    The 90-Day Irregular-Costs Notebook: Find the Expenses a Monthly Budget Misses

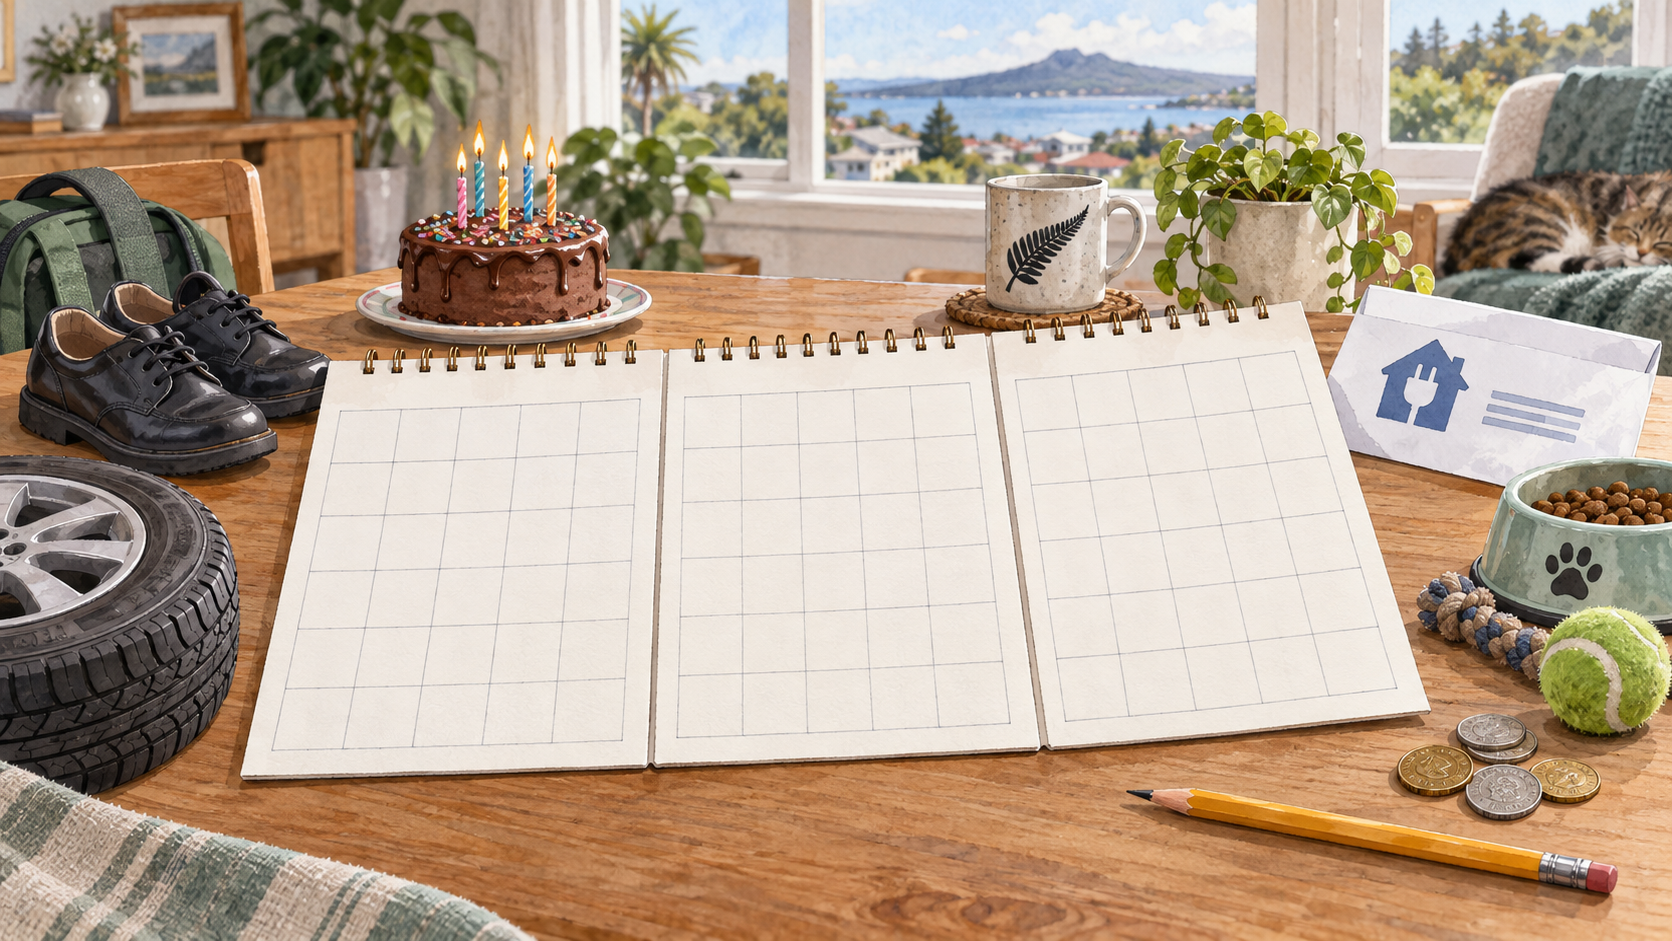
    A budget can look tidy in a normal month and still feel impossible when the car needs a tyre, school shoes wear out or several birthdays land close together. Those costs are not always emergencies; many are simply irregular. A short tracking habit can help you see their pattern before deciding what to do about them.

    Try a 90-day notebook

    For the next three months, record costs that do not arrive every week. Useful categories might include vehicle servicing, school supplies, health appointments, pet care, annual subscriptions, gifts and seasonal clothing. You can use bank transactions, a phone note, a spreadsheet or a paper page. Sorted notes that three months can reveal costs a single month may miss, including car costs, vet bills and birthday presents.

    Keep the record descriptive rather than judgmental. Write the date, category and amount. If a cost was shared, note only the portion your household paid. If an amount is an estimate—perhaps you are planning for next year’s school uniform—label it as an estimate instead of mixing it with actual spending.

    Use three check-ins, not daily perfection

    At the end of each month, take ten minutes to add new entries and spot anything you forgot. Do not worry about perfect categories. If a cost is hard to classify, put it in “other” and keep moving. The habit is useful when it is sustainable, not when it becomes another source of pressure.

    After 90 days, sort the entries into broad groups and ask three questions: Which costs repeat? Which were genuinely unusual? Which dates or seasons seem to matter? A three-month record still cannot capture every annual cost. Pair it with older bank records, invoices or reminders where available, and treat the result as a better estimate—not a guarantee.

    Turn observations into a gentle plan

    If a cost happens once a year, you might divide an estimate by 12 to see what a monthly set-aside would look like. For example, a $240 annual bill would average $20 a month. That arithmetic does not mean you must immediately find $20; it helps you understand the scale and timing. If the number does not fit, note the gap and consider what support, timing or adjustment is realistic.

    Sorted’s guide to tracking spending says starting with one month is better than not starting, while three months can show more irregular expenses. It also suggests continuing to compare real costs with a budget periodically. You can use your notebook to update a plan, prepare a reminder or simply recognise that a lumpy month is part of a longer pattern.

    Share the process only with people you trust and only as much as feels useful. The notebook is a tool for making the next decision clearer, not a scorecard. If recording everything feels too demanding, begin with one category—such as transport or school costs—and expand only if it helps.

    FAQs

    Why track for 90 days?

    A three-month view can reveal costs that do not appear in every month, although it will not capture every annual expense.

    What counts as an irregular cost?

    It is a cost that arrives unevenly or less often than weekly, such as a birthday, vehicle service or school purchase.

    Do I need a budgeting app?

    No. A banking app, spreadsheet, phone note or paper notebook can work. Choose a method you will keep using.

    What if I miss recording some purchases?

    Add what you can from receipts or account records, label estimates and continue. A useful record need not be perfect.

    How do I turn an annual cost into a monthly estimate?

    Divide the annual estimate by 12. For example, $240 divided by 12 is $20 per month.

    Does tracking mean I must cut the spending?

    No. Tracking helps you understand and plan for costs. Any change should fit your priorities and circumstances.

  • The Fifteen-Minute Money Meeting: A Habit That Keeps Plans Visible

    The Fifteen-Minute Money Meeting: A Habit That Keeps Plans Visible

    A money plan is easier to use when it is visible before a decision arrives. A fifteen-minute meeting can give a household, whānau or learning group a calm place to look at what is coming up, what matters most and what needs checking next.

    This is not a meeting for judging anyone’s spending. Sorted describes a budget as a plan for spending and saving, and recommends gathering information about income, regular costs, irregular costs and goals. The meeting turns that idea into a small recurring habit.

    Minutes 1–3: choose a private, predictable time

    Pick a time that is close enough to the week ahead to be useful. Decide who needs to be involved and what information each person is authorised to see. A learner can use fictional numbers or a personal allowance plan instead of sharing household balances.

    Minutes 4–7: name the next commitments

    Write the costs that are due before the next meeting: transport, food, school activity, bill, appointment or agreed payment. Mark anything that is an estimate. The purpose is not to predict perfectly; it is to make the next decisions less surprising.

    Minutes 8–10: check the plan against available money

    Place the amount available for the period beside the near-term commitments. If the plan has room, decide where a small amount could go toward a goal or flexible spending. If it does not fit, choose one next step such as confirming a due date, changing an optional plan or asking a provider about the available options.

    Minutes 11–13: name one priority

    Choose one goal or value for the next week: keeping transport covered, saving for an event, leaving room for a shared activity, or avoiding a late fee. Sorted’s guidance on money goals encourages goals that are specific, realistic and written down. One visible priority is easier to revisit than a long list of intentions.

    Minutes 14–15: close with one action

    Write down who will do what and when. It might be checking a price, moving a planned amount, cancelling an unused booking or bringing a receipt to the next meeting. End by choosing the next meeting time. If the meeting becomes tense, pause and return later; a repeatable habit matters more than completing every question.

    Over time, the meeting can become a record of learning. A household may notice which costs are regular, which are irregular and which priorities change. That is resilience in practice: not having a perfect plan, but having a small routine for returning to the plan.

    Sources and further reading

    Sorted: How to build a budget step by step; Sorted: Why money goals are important and how to set them.

    FAQs

    Does a money meeting need to last exactly fifteen minutes?

    No. Fifteen minutes is a helpful starting point. The aim is a short routine that people can repeat.

    Who should attend?

    Include the people who share the decision or need the information, while protecting anyone’s private financial details.

    What if a cost is only an estimate?

    Label it as an estimate and update it when better information becomes available. Do not treat an estimate as a confirmed amount.

    What if the plan does not fit?

    Choose one practical next step, such as confirming a date, changing an optional choice or asking about available options.

    Should every meeting include a savings goal?

    Not necessarily. The priority might be an upcoming essential cost or simply understanding what is due next.

    Can learners practise this without real household information?

    Yes. Use fictional income, costs and goals so learners can practise planning without sharing private balances.

  • Lost Track of Spending? Try This Ten-Minute Money Reset

    Lost Track of Spending? Try This Ten-Minute Money Reset

    You meant to check your spending on Sunday. Then the week filled up, a few receipts disappeared, and your budget page now feels like another thing you have failed to do. Pause there. A missed check-in is information about the routine, not a verdict on you.

    This ten-minute reset is for getting oriented again. It does not require a perfect record or a promise to fix everything at once.

    Minute 1–2: gather the next facts

    Open the account or notes you normally use. Write down the money currently available for the spending decisions you control, plus the next expected income date if you know it. If you share finances, only access the information you are authorised to see.

    Minute 3–5: look at the next seven days

    List the bills and essential costs you expect before the next check-in: for example, transport, food, a phone plan or a payment you already agreed to make. Mark a due date beside each one. Keep estimates clearly labelled as estimates; do not turn a guess into a fact.

    Minute 6–8: compare, then choose one action

    Put the available amount beside the near-term commitments. If the plan looks workable, choose a day and time for the next short review. If the numbers do not fit, choose one practical next step: check a bill date, pause an optional purchase, contact the provider to ask about options, or talk with a trusted adult or whānau member. You do not have to solve every longer-term question in this one sitting.

    Minute 9–10: restart with a tiny record

    Pick a format you will actually use: a phone note, a paper page, or a spreadsheet. Record one category or a few transactions until the next check-in. Sorted’s guide to tracking spending notes that starting with one month is better than not starting, and that a longer period can reveal irregular costs such as car bills or gifts. Treat a short reset as a restart, not a complete picture.

    When your routine is steady again, review what made the old one hard to keep. Was the reminder at the wrong time? Was the form too detailed? Change one part so the next check-in is easier. Resilience is not never losing track; it is having a small way back.

    FAQs

    What if I missed more than one week?

    Start with what is due next and what you can verify now. You can rebuild the longer record gradually instead of trying to recreate every detail at once.

    Does a ten-minute reset replace a full budget?

    No. It is a short orientation check. A fuller budget can be built or updated when you have more complete information.

    What should I check first?

    Check the amount available to you, expected income timing if known, and the essential commitments coming up soon.

    What if the numbers do not fit?

    Choose one next step, such as confirming a bill date, pausing an optional purchase, asking a provider about options, or speaking with a trusted person.

    Do I need an app to track money?

    No. A phone note, spreadsheet or paper record can work. Use a method you can maintain and keep private details secure.

    How long should I track spending?

    A short record can help you restart. Sorted suggests that tracking for longer, such as three months, can include irregular costs and provide a broader picture.

  • Build a Small Emergency Fund Without Waiting for a Perfect Income

    Build a Small Emergency Fund Without Waiting for a Perfect Income

    Financial resilience does not begin when you have a huge balance. It begins when some money is deliberately kept available for a problem you did not plan for. A broken appliance, an urgent trip, a health cost, or a gap in income can turn a normal week into a difficult one. A small buffer cannot solve every problem, but it can create time and choices.

    Give the fund one clear job

    An emergency fund is for unplanned costs that are important enough to need attention and unusual enough not to belong in your normal weekly spending. Regular groceries and scheduled bills are part of a budget. A sudden repair or unexpected loss of income is the kind of event a buffer is designed to help with.

    Write the job down in plain language. “Money for surprises that protect my basic life” is more useful than a vague promise to save. A clear purpose also helps you decide when to use the money and when to leave it alone.

    Start with the first reachable milestone

    Choose a first target that feels possible, such as $25, $50, or the cost of one common repair. The exact amount depends on your situation. The important step is creating a visible reserve and a habit of adding to it.

    If income changes from week to week, use a flexible amount rather than a promise that will make the rest of the budget fail. A small regular transfer can be more sustainable than an ambitious plan that is abandoned after one difficult month.

    Make saving automatic when possible

    People often intend to save what remains after spending, but “what remains” can disappear. The Consumer Financial Protection Bureau suggests creating a savings plan and using automatic deposits as one way to make saving more consistent: saving for emergencies and the future.

    Automation is not magic. Check that the amount and timing fit your cash flow. If an automatic transfer causes an overdraft or makes an essential bill difficult to pay, reduce it and choose a safer schedule.

    Keep it safe and accessible

    The right home for emergency money should protect it from casual spending while keeping it available when a genuine need arrives. A separate savings account may help. Some people use a labelled envelope or another clear method while building the first milestone. Consider safety, access, fees, and local rules.

    An emergency fund is not the same as a long-term investment. The job of a small buffer is stability and access, not chasing the highest possible return. Money placed somewhere difficult to access may not help when the repair needs to happen today.

    Use it without shame when the emergency is real

    A buffer that is never used is not automatically a successful buffer. If a genuine unplanned cost arrives, using the money can be exactly what it was designed for. Afterward, review what happened, adjust the target if needed, and restart the habit.

    MoneyCQ models this lesson through financial shocks. Skipping protection can make a setback harder, while a reserve can give you a better recovery path. In real life, resilience is built from the same ingredients: planning, a little available cash, and the willingness to rebuild after a drawdown.

    Sources and further reading

    The CFPB’s essential emergency-fund guide explains what a fund is for, how to build one, and why even small savings can help. The examples here are general education, not personal financial advice.

    FAQs

    What is an emergency fund?

    It is money set aside for important, unplanned costs or a sudden change in income.

    How much should I save first?

    Choose a reachable first milestone based on your circumstances, such as the cost of a common repair or another meaningful small amount.

    Should emergency savings be invested?

    A small emergency reserve should prioritise safety and access, because it may be needed quickly.

    How can I make saving more consistent?

    Use a clear goal and, where it fits your cash flow, an automatic transfer on a suitable schedule.

    When should I use the fund?

    Use it for a genuine important expense that was not part of your normal planned spending.

    What should I do after using it?

    Review the event, adjust the target if necessary, and restart regular contributions when you can.

  • Surviving Financial Shocks

    The storm will come. That’s not pessimism — it’s the whole reason this chapter exists. Financial shocks are a when, not an if: a job loss, an illness, a disaster, a crash. Resilience is what separates people who survive the shock from people who are defined by it.

    What a shock actually looks like

    Shocks come in shapes: income stops (job loss, illness), expenses spike (medical bills, repairs, disasters), or wealth drops (markets crash, property falls). Often two at once — the car breaks down the same month the hours get cut. The details differ; the shape is always the same: a sudden, unexpected gap between what you have and what life demands.

    The layers of defence

    • Layer 1: the emergency fund. Cash that stops the first hit from becoming a loan.
    • Layer 2: insurance. Protection for the losses too big for cash — health, home, income.
    • Layer 3: multiple income streams. When one stream stops, others keep flowing.
    • Layer 4: low fixed costs. The smaller your monthly bills, the smaller the gap gets.
    • Layer 5: skills. The ability to earn again, differently, is the deepest defence.

    What to do when it hits

    • Don’t panic-sell or panic-borrow. Shocks feel urgent; most decisions made in panic cost more.
    • Take stock. Write down what you have, what’s coming in, and what’s essential. Reality is less scary than imagination.
    • Cut the non-essentials first. Freeze wants before touching the fund.
    • Ask for help. Family, community, and services exist for exactly this. Resilience is not doing it alone.
    • Plan the comeback. The shock ends. The recovery plan is what decides how you come out the other side.

    The mindset part

    The financial part of a shock is fixable. The psychological part is harder: the urge to hide, to freeze, to blame yourself. Remember that shocks are not judgements — they’re weather. Resilient people don’t have fewer storms; they have better decks, and they keep sailing after.

    How this lifts your CQ

    Financial resilience is the lever that holds all the others together. A high CQ isn’t about never taking a hit — it’s about how quickly and completely you recover when one lands. In the life-sim, this is the difference between a setback and a game-over.

    Resilience isn’t avoiding the storm. It’s being the one who’s still standing when the storm passes.

    Run it in class

    Give each group a ‘shock card’ — job loss, illness, disaster, market crash — and a simple balance sheet. Their task: which layer of defence gets hit first, and what’s the recovery plan? Present the plans, compare, and note that every group ends up needing the same boring layers.

    Want to see how these choices move your score? MoneyCQ is a life-sim where your Cash Quotient rises and falls with decisions just like these. The game is live — build a life and watch your CQ move at app.moneycq.com.

  • Small Money Habits That Compound

    Big money moves get the headlines. Small money habits win the game. Nobody notices a daily habit while it’s happening — but a year later, the gap between people with small habits and people without them is enormous.

    The habits that quietly compound

    • Check your balances weekly. Awareness is the base of every other habit.
    • Move money on payday, automatically. Save before spending; never negotiate with yourself.
    • Take a no-spend day. One day a week where the wallet stays shut resets the impulse.
    • Round up. Bank the change on every purchase into savings — invisible and effective.
    • Plan one purchase a week. Before you buy anything non-essential, write down why it’s worth it.
    • Read or watch one money thing. Five minutes a week of learning beats a crash course.
    • Do a weekly review. Ten minutes: what came in, what went out, what’s next?

    Why tiny works

    Tiny habits work because they’re nearly effortless, so they survive bad weeks, busy days, and motivation crashes. A $2 daily round-up is $730 a year — before interest. A weekly check catches leaks early. A no-spend day trains the muscle that makes every other decision easier. None of it feels like anything. All of it compounds.

    The 1% rule

    Getting 1% better at money each week sounds like nothing. Over a year, that’s more than a 60% improvement — and unlike motivation, habits don’t fade. The goal isn’t a perfect financial life. It’s a slightly better one, repeated, until better becomes normal.

    How to start

    Pick one habit. Just one. Run it for two weeks before adding anything else. The habit that survives is worth more than the five that didn’t. Once it’s automatic, add the next. That’s the whole system.

    How this lifts your CQ

    Every lever of your Cash Quotient — spending, saving, resilience — is built from small repeated decisions. The score is just the scoreboard; the habits are the game.

    You don’t rise to the level of your goals. You fall to the level of your systems — so make the systems tiny and repeat them.

    Run it in class

    Students each commit to one micro-habit for two weeks and track it daily. The class compares survival rates, shares what got in the way, and picks round two. The discussion about why tiny beats heroic is the real lesson.

    Want to see how these choices move your score? MoneyCQ is a life-sim where your Cash Quotient rises and falls with decisions just like these. The game is live — build a life and watch your CQ move at app.moneycq.com.

  • Peer Pressure and Your Wallet

    It starts small: everyone’s getting the new game, so you do too. The shoes everyone’s wearing. The treat everyone’s buying after school. It doesn’t feel like a financial decision — it feels like belonging. But spending to fit in is one of the most expensive habits there is, and it quietly steals both your money and your plan.

    Why it happens

    Humans are wired to care what their group thinks. That wiring kept us alive on the savannah, but it does terrible things to a wallet. The fear isn’t really about the item — it’s about being left out. Once you see that, the whole game changes: the purchase isn’t solving a money problem, it’s solving a belonging problem with money.

    The real cost

    The visible cost is the price tag. The hidden cost is everything it delays: the savings goal, the thing you actually wanted, the freedom of being able to say yes later. And the sneakiest cost is identity — every time you spend to be someone else’s version of you, your own plan gets a little quieter.

    How to resist

    • Decide before the moment. Set your limits when you’re calm, not when everyone’s watching.
    • Use the 24-hour rule. Pressure doesn’t survive a night’s sleep.
    • Practise your no. ‘That’s not in my plan this week’ — said once, firmly, works.
    • Find your people. Friends who respect your money choices are worth more than the ones who don’t.
    • Reframe it. Not buying isn’t missing out — it’s choosing your own bigger yes.

    The quiet confidence

    People who are good with money rarely brag about it, and they rarely argue about it. They just have a plan, and the plan makes the no easy. That quiet confidence is attractive — and it’s earned by exactly the kind of decisions that are hard in the moment and easy to live with later.

    How this lifts your CQ

    Spending habits and lifestyle choices are two levers of your Cash Quotient. Resisting the crowd isn’t about being cheap — it’s about being the author of your own financial story.

    The most expensive word in personal finance isn’t ‘no’. It’s ‘everyone’.

    Run it in class

    Role-play the hard moments: the group pressure to buy, the laugh, the ‘come on’. Practise the one-line responses until they feel natural. Then discuss the difference between fitting in and belonging — the room usually has plenty to say.

    Want to see how these choices move your score? MoneyCQ is a life-sim where your Cash Quotient rises and falls with decisions just like these. The game is live — build a life and watch your CQ move at app.moneycq.com.