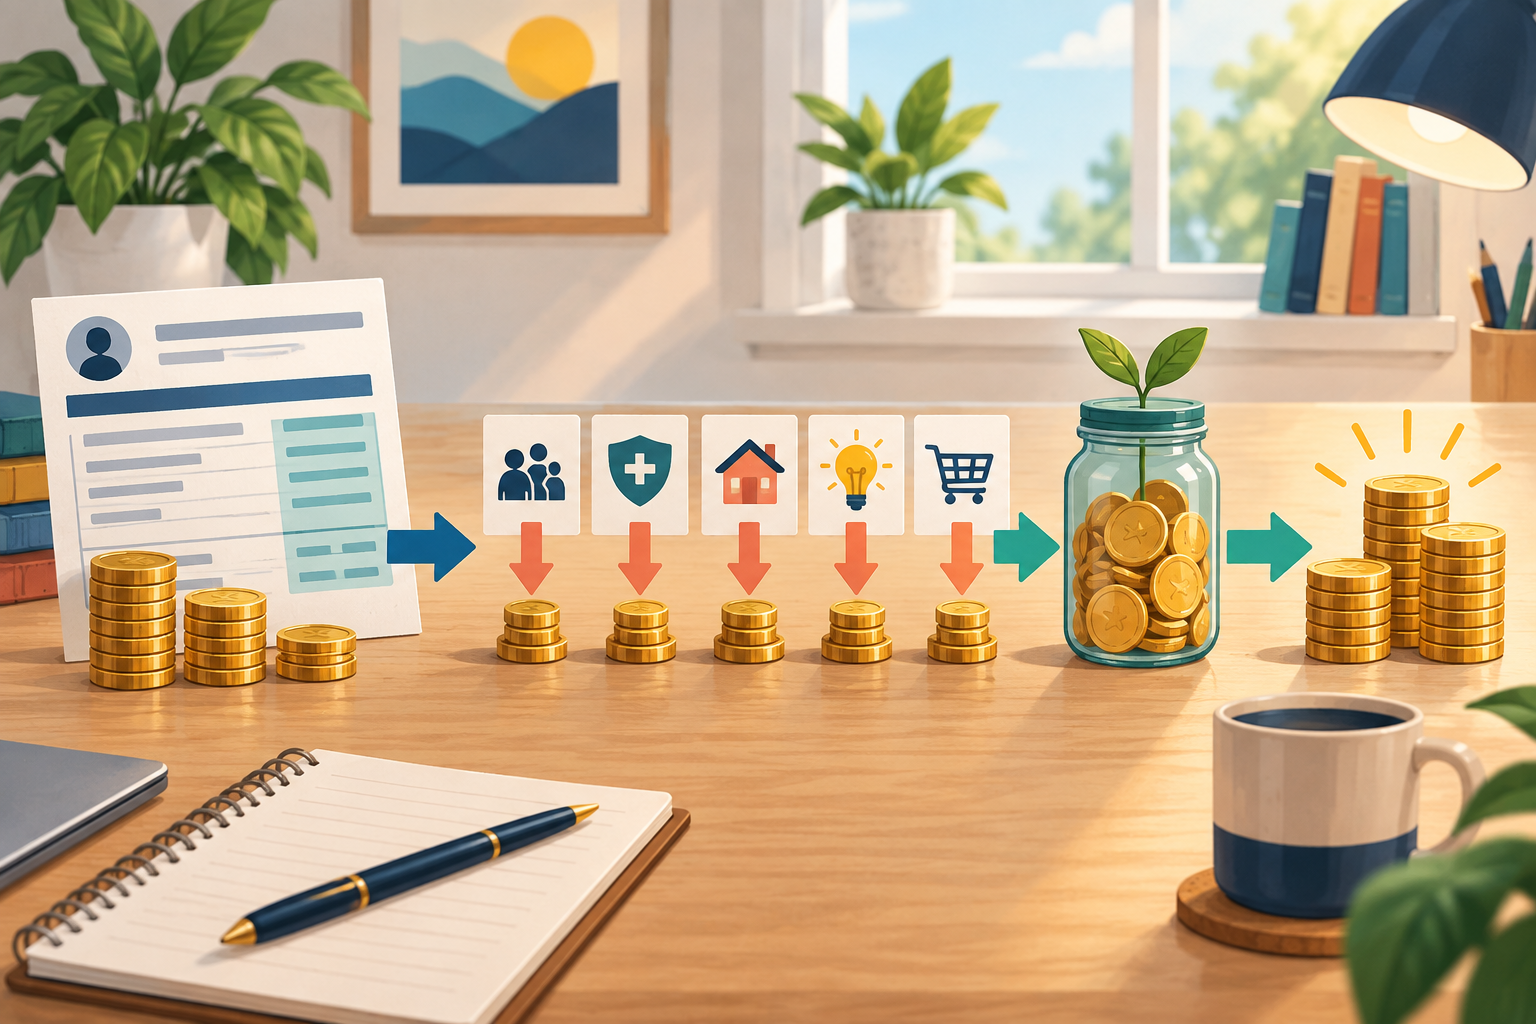
A new job can come with a number that looks wonderfully large. Then payday arrives and the amount in your account is smaller. That is not a trick, and it does not mean someone has lost your money. It means your gross pay has passed through the deductions that apply before you receive your take-home pay.
Understanding the journey from salary to spendable money is one of the most useful money skills you can build. It helps you plan honestly, compare jobs fairly, and make sense of the payslip in MoneyCQ or in real life.
Gross pay is the starting number
Gross pay is the amount agreed before deductions. It might be shown as an annual salary, an hourly rate, or a weekly amount. If a job pays $25 an hour and you work 20 hours, the gross pay for that week is $500 before anything is taken out.
Gross pay is useful for comparing the size of different jobs, but it is not the amount you can automatically spend. A salary offer can look attractive while a different job with better hours, lower travel costs, or more reliable income leaves you with more useful money overall.
Take-home pay is what reaches your account
Take-home pay, sometimes called net pay, is the amount left after the deductions that apply to you. It is the number that should anchor your weekly or monthly spending plan. Rent, food, transport, saving, and fun all have to fit inside this amount.
The exact deductions depend on where you live, your income, your tax settings, and the choices you make. In New Zealand, an employer generally deducts PAYE and the ACC earners’ levy from salary or wages. Other deductions may include KiwiSaver contributions, student-loan repayments, charitable payroll giving, or other authorised amounts. Inland Revenue explains that the tax code supplied to an employer affects how much PAYE is deducted: IRD guidance on salary and wages.
Why the difference matters when you plan
Imagine two people each seeing a gross weekly pay of $900. One has a long commute, a student-loan deduction, and higher insurance costs. The other works close to home and has fewer deductions. Their gross pay is identical, but their available cash is not.
A realistic plan begins with take-home pay. First list regular commitments such as housing, utilities, transport, and debt payments. Then allow for flexible essentials such as groceries. After that, give saving and irregular costs a place. Only then should you decide how much is available for optional spending.
Read a payslip like a money map
When you receive a payslip, look for four landmarks: the pay period, gross earnings, deductions, and net pay. Check whether the hours or salary shown match what you expected. Notice whether deductions are fixed, percentage-based, or changing. If a number is unfamiliar, ask the employer or payroll team rather than guessing.
A payslip is also a record of trade-offs. A retirement contribution may reduce today’s cash while building a locked or long-term balance. A student-loan repayment may feel like a loss from the week’s budget, but it is reducing a liability. Seeing every line helps you understand why your cash flow looks the way it does.
How this appears in MoneyCQ
In MoneyCQ, the payslip flow turns an abstract salary into a lived decision. Gross pay comes in, deductions are shown, and the amount available for the week becomes real. That makes it easier to test choices: Can you afford a higher rent? What happens if you save first? Does a second income stream actually cover the extra costs it creates?
The lesson is simple: build your life around money you can use, not money that only appears at the top of an offer letter. Gross pay tells you the size of the starting pool. Take-home pay tells you what the next decision can actually be.
Sources and further reading
For a New Zealand example of progressive income tax rates and PAYE deductions, see Inland Revenue tax rates. Rules differ by country, so use the official tax authority for the region that applies to you.
FAQs
What is gross pay?
Gross pay is the amount earned before tax and other deductions are taken out.
What is take-home pay?
Take-home pay is the amount left after the deductions that apply to your pay have been made.
Which number should I use for a budget?
Use take-home pay because it is the amount available to cover spending and saving.
Why can two people with the same salary receive different amounts?
Tax settings, retirement contributions, student-loan payments, and other deductions can differ between people.
What should I check on a payslip?
Check the pay period, earnings, deductions, and net amount against what you expected.
Are pay deductions always bad?
No. Some deductions fund taxes, insurance, retirement saving, or debt repayment, even though they reduce the cash available today.
Leave a Reply